In Part I of our interview with Francisco D’Souza, President and CEO of Cognizant, we discussed the rampant growth Cognizant has experienced, the global economic environment as we emerge from the Recession, and Frank’s point of view on the Cloud and the sourcing industry.
Now, in Part II, we get a bit more personal about what makes Frank tick…
HfS Research: Frank – tell us a bit about yourself and your upbringing and how you ended up leading a $4.6 billion global corporation? Did you imagine you’d wind up doing something like this?
Francisco D'Souza, President and CEO of Cognizant (click for bio)
Francisco D’Souza: After finishing my graduate work at Carnegie Mellon University, I took a job as a management associate with Dun & Bradstreet. Early on, I was presented with an opportunity to work with a team to build D&B’s first IT captive in India. I jumped at the opportunity. In 1994, that captive was spun off in to Cognizant and the rest, as they say, is history. I can tell you with a great deal of certainty that I never imagined running a $4.6 billion business! On the contrary, I just focused on doing things along the way that I enjoyed and which provided me opportunities to grow and learn. The rest just happened… I also have to say that we have the best team in the industry at Cognizant and my achievements are a reflection of their work; it was by no means an individual effort.
HfS Research: If you had your time again, would you choose the same path? If you weren’t a techno-preneur what would you choose to be doing?
Francisco D’Souza: I am incredibly happy with where I am today and Cognizant’s trajectory for the future; it is impossible to look back and wish I had taken a different path.
But, if I had to do anything else in life I would have wanted to be an inventor. I am overwhelmed by the power new technologies have on people’s lives – the power to dramatically change people’s levels of productivity or their standard of living. To contribute to that would be incredible. Plus, I love to work with my hands. In my basement, I have a room that’s just for me. Even my wife and kids aren’t allowed in because it’s a mess. I have all sorts of things in there, like a whole collection of old brass telegraph keys that are anywhere from 50 to 150 years old. I love this period; the days of Morse, Marconi and Edison and the beginning of electronic communication.
HfS Research: And finally, being one of the youngest CEOs on the Nasdaq today, what advice do you have to many of us forging our careers in today’s services industry? Are the core traits of success today different than they were 5 years’ ago?
Francisco D’Souza: In my mind, the key to success is the same for anything you do – dedicate yourself to something you love and don’t be afraid to take risks. If it feels like work, or if you are not passionate about what you’re doing, you won’t have the energy to put in the time and effort needed to be successful.
HfS Research: Frank, thanks for your time today – we look forward to sharing this discussion with our readers.
HfS Research VP of Marketing Mark Reed-Edwards got together with HfS Founder and CEO Phil Fersht and Dawn Evans, President and CEO of Sourcing Interests Group, to discuss the new groundbreaking industry research and networking partnership announced on March 8.
Click here to listen in on why on earth they decided to do this:
SourceCorp and HOVS Services are two companies that rarely make the news. These are blue collar outsourcing organizations who have each been in the marketplace for over 20 years with deep specialization in backoffice transaction processing and document management automation.
However, the announced merger of two competitors into a new entity with combined revenues of almost $500m, a strong positive cash flow, 14,200 employees, and a combined customer segment of half the Fortune 50 is intriguing for several reasons.
Have no doubts – this merger is all about synergies, just as we said about the Patni –iGate merger. These are two remarkably similar organizations operating remarkably similar businesses, but with very few shared customers. There is plenty of opportunity to improve profitability of the combined entity. However, for the merger to be successful in the eyes of current and potential customers, the combined organization has to not only eliminate administrative redundancies, it has to rationalize its core transaction processing technologies in a manner that will improve the value of its clients.
From a competition perspective, this merger accomplishes two marketplace changes. First, it eliminates a tough competitor with a similar approach and cost structure. Second, it creates a $500m competitor to Xerox/ACS (itself dealing with post-merger headaches), Accenture and IBM, but with a simpler story to tell, as SourceCorp+HOVS is an accomplished pure play BPO provider and doesn’t have to talk about copy machines, consulting, or software. Importantly, the combined entity earns 27% of its earnings from the healthcare sector, making it a formidable provider for clients to consider. Also, the organization has almost 100 US domestic locations, which is a considerable footprint for regulated clients or clients that need a vendor located close to their operations.
From an industry perspective, there is little doubt that Xerox’s ACS acquisition was a partial impetus for the merger. Surely pure play BPO providers are an important aspect of the marketplace, but clients who have outsourced are now looking for transformation, and the newly combined entity will have to decide whether synergies and scale are sufficient to carve out meaningful market share, or they will need to reinvest savings into creating transformational market offerings that will compete with the big boys and keep existing companies happy.
One more aspect of the industry is worth noting: SourceCorp and HOVS Services have largely focused on transforming printed material into transactional data. As clients increasingly seek to eliminate manual paperwork and automate transactions, the marketplace for the bread and butter of these two companies’ services will erode. So, this merger may offer an insight into the impact clients’ internal investment activities have on the demand for BPO services.
Despite the promise of a strong future, there are plenty of risks. If core synergies are to be obtained, clients have to be migrated to new platforms as old ones are eliminated, and some clients may be resistant or slow to do so (buyers, you know who you are). Less tangibly, management teams that competed head-to-head for many years will need to learn to collaborate and build a new company. Lastly, potential clients may balk at working with a company deeply focused on internal merger.
Latin America really is emerging as a nearshore powerhouse for both IT services and BPO, and we thought it high-time an analyst firm actually took a close-up look at the region. The result is a broad-ranging study, the results of which were distributed by Softtek today.
We’ve got a quick glimpse a the study’s six key findings:
Global IT delivery strategies more frequently include Latin America: The power of a well-crafted global delivery strategy lies beyond labor arbitrage and low-cost offshoring from India. Although most projects featuring a global delivery strategy stick to application development work, there are opportunities for more advanced relationships beyond staff augmentation and software engineering services. New remote infrastructure management offerings and service offerings that focus on niche areas of application expertise now see global delivery locations spread beyond India into Latin America. The region is vast and offers the ingredients to make any nearshore move successful: it has a thriving technology economy, it brings competitive software development rates, it can demonstrate industry innovation, and with vast human capital it has the potential to scale.
Latin American strategies underpin global delivery with increasingly mature services: Firms investigating service delivery from the region like the cultural familiarity bred by the influence of the US and Europe. Customer interviews reveal how distance and time-zone repeatedly offer real-time collaboration opportunities and reduce the burden of oversight and resourcing through physical proximity and better resource alignment. The region continues to offer coding, testing and other IT support but this paper uncovers US firms sourcing niche application services for specific industries (e-banking/gaming), analytics (retail), and bilingual back office support services (finance and accounting). Buyer choice continues to grow as a diverse set of providers continue to invest in new locations in Latin America and customers find more opportunity to realize value as client/vendor relationships develop over time. HfS has developed a location scorecard tool to help buyers assess each country in Latin America as a global delivery destination.
The region offers buyers three routes to value:
Specific skills at lower costs than onshore in the US or Europe. The region still offers labor arbitrage for desirable skills.
Reducing the risk for immature processes. Portfolios of applications that demand more interactions between onsite and offshore teams or that have highly interactive methodologies in play require more oversight especially if their internal processes are weak.
Supporting a broader market move into the region. Engaging with local providers and using local resources demonstrates a broader commitment to the region.
Calculate the true TCO and measure risk: This report finds that rate cards for services don’t tell the whole story. Although the region offers labor arbitrage for desirable skills, it’s fading just as quickly as anywhere else. Pure labor rate comparisons must factor in costs for staffing levels (onsite, offshore, nearshore) during different phases of the relationship, such as knowledge transfer and transition. Clients attest to lower attrition levels and fewer site visits, and when they were required, these site visits as part of the governance were much easier to do—these and other soft factors impact the total cost of ownership. Taking work to Latin America does not guarantee success or drive instant savings however—any move nearshore needs careful consideration against the type of work that needs to be done, the maturity of the internal processes and the challenges it creates for corporate culture.
Build the business case with care—resource levels need careful consideration: Quantifying resource levels on a typical nearshore engagement and comparing this to an offshore engagement from India is difficult to do when firms have to factor in that the number of resources flexes depending on the stakeholders involved and the IT process maturity in play. Highly leveraged offshore relationships may demand the provider lands resources onsite with the client to make the deal work—the net effect could be that highly leveraged offshore relationship costs more when landed resources at the client site are factored into the cost rather than blending of going 90% offshore to India rather than nearshore to Latin America.
Local providers must play the global delivery card too: Outsourcing in Latin America will continue to grow because the region can serve many different types of demand. The business services industry is at a stage of globalization, which means for buyers that it’s really going to be a competition between different providers rather than different countries. This paper recommends buyers conduct due diligence and check what path their prospective providers are following. Do they offer the opportunity (i.e., tools, methodologies, best practices) for more advanced relationships beyond simple staff augmentation services? Local Latin American service providers must operate their own service operations with service delivery mechanisms and capabilities to support their customers as they enter into emerging markets beyond Latin America such as China or Russia.
As customers mature in how they buy their services from providers in the region, so too does the suite of services on offer. As a result, firms can tap into more sophisticated functionality from their nearshore partners—the study found finance transformation and outcome based relationships superseding low-cost staff augmentation.
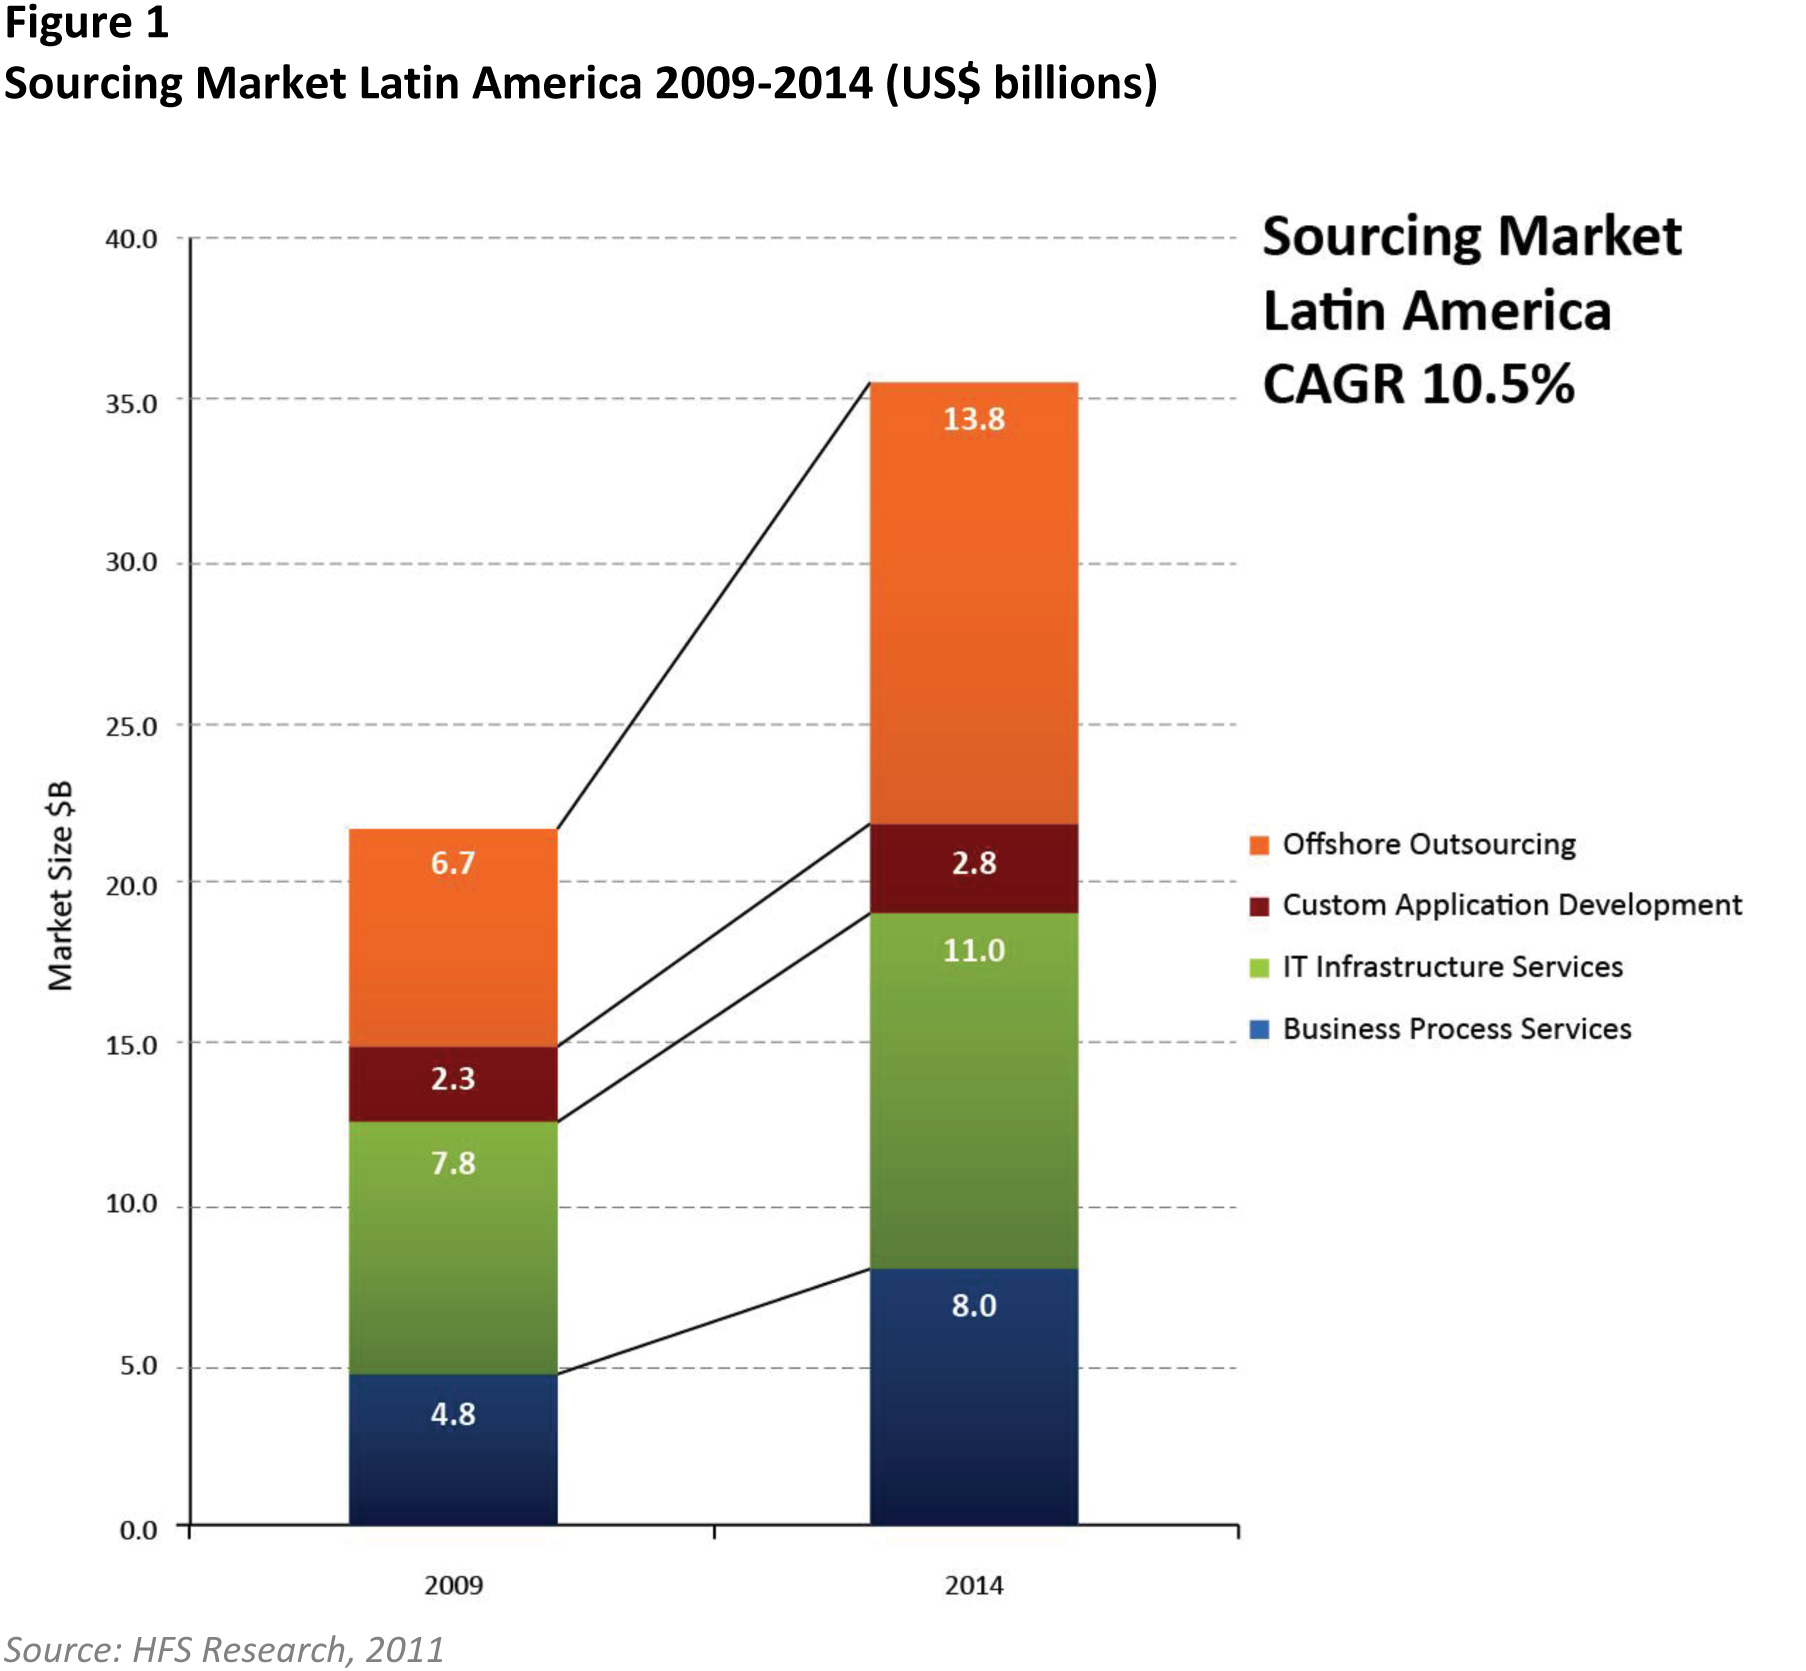
To give you a further glimpse of the report, this figure provides a profile of the projected growth in sourcing services spending by major service category in Latin America from 2009 and 2014. The report also includes forecasts for each region within Latin America.
Click to enlarge
Discover How Latin America Powers Global IT Delivery:
We’re going to release our 2011 Finance and Accounting Outsourcing (FAO) industry landscape next week, and one dynamic that has really stood-out over the last three years, is the different competitive strategies going on at the high-end of the market versus the smaller engagements.
Most striking, are the divergent strategies of the market leaders, Accenture and IBM. While Accenture has consolidated its commanding presence with the large-scale enterprise customers, IBM has determinedly gone after the mid-market.
You may recall we highlighted, back in January, that the average FAO engagement fell below $20m TCV for the first time last year, we also pointed out that those providers with scale and flexibility of delivery resources are those best-positioned to pick up the smaller engagements:
Scaling a global BPO business based on multiple small client engagements is wearing on resources – and profit margins, and the providers scrapping for their share of the smaller business, are faced with a simple choice: Either stick with it and view this as a 10-year journey, or if you simply don’t have the patience or appetite to put in the investment, then get out and refocus your services on other activities. For those who stay the course (and we expect most will), they need to keep putting in the grind to win small engagements, and attempt to scale their BPO delivery resources, while trying to turn some sort of profit.
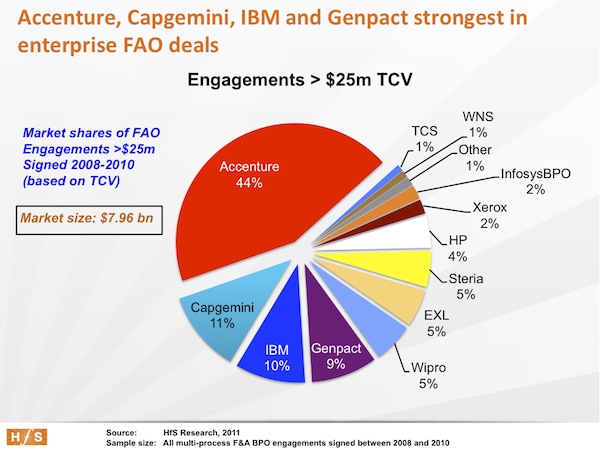
Our deeper-dive analysis shows that exactly this scenario is happening with several providers over the last three years. Let’s contrast both the enterprise-level market performances (engagements over $25m in TCV) and the mid-market (engagements below $25m TCV).
Accenture has developed a commanding position with enterprise engagements, while IBM has gained a lot of ground winning smaller-scale and mid-market clients. As these market share graphs illustrate, all the FAO engagements signed since the beginning of 2008 that have a Total Contract Value (TCV) of more than $25 million, dominate 80% of the total market, with a total expenditure of close to $8 billion. Accenture has been dominant in retaining and developing its client base of enterprise-level engagements, with Capgemini, IBM and Genpact providing the main competition with enterprise-level engagements.
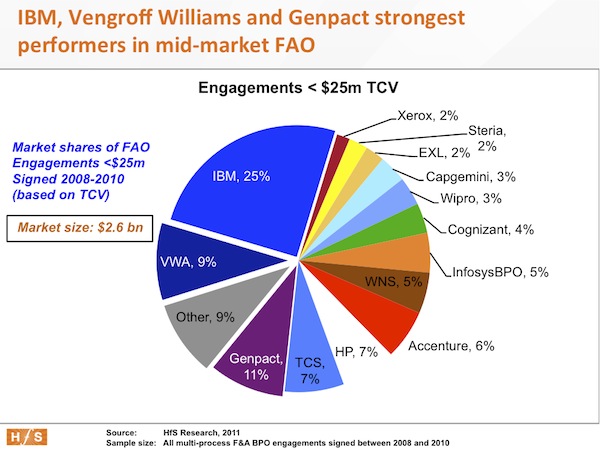
The FAO newcomers, over recent years, have struggled to win many (or, in some cases, any) enterprise-level deals, and have sought to grow their respective market footprints by taking on smaller-sized engagements – many of which fall into the sub-$5m TCV category. The following graphic illustrates the service provider shares of the smaller-scale FAO engagements signed since the beginning of 2008, where the one notable market-mover in the mid-market segment has been IBM, winning the lion’s share of business with a commanding 25% market share.
The onshore order-to-cash specialist, Vengroff Williams and Associates (VWA), also performs strongly in this segment, while there has been a relatively even-spread of business across all the major service providers, such as TCS, WNS, InfosysBPO and Cognizant, in addition to the FAO pure-plays, WNS and EXL. Genpact has proven the most consistent at developing a balanced portfolio of enterprise and mid-market clients over the last three years.
So what do these competitive dynamics mean for the future of the FAO industry?
Essentially, the FAO industry is readying itself for life beyond the simple “lift and shift” deal, where margins were made off labor-scale being shifted offshore. Labor-arbitrage doesn’t amount to nearly as much, when you’re dealing with, for example, a 30 employee transition. What’s more, most of these providers need to start scaling their resources across multiple clients, or face a depressing race to the bottom, where their only real differentiator is their ability to provide low-cost labor. Having scale and flex from ingesting several large-scale clients is extremely valuable for providers, but only if they can leverage those resources to new clients as they take them on, in order to optimize their margins on the new business and remain cost-competitive.
Our take is that providers need a good balance of both large and mid-scale engagements, whereby they can allocate delivery resources and process acumen across their customers in order to develop repeatable process flows with application wrappers to enable them. While small-scale engagements can struggle to be profitable, they do force the provider to develop a utility model that keeps then in the black. Clearly, we’re in a highly-competitive market situation, and this isn’t a market for the faint-hearted.
If you can achieve a smattering of these elements, you might actually return home thinking “that wasn’t such a waste of time and money, now, was it?”
So we were excited to attend the SIG Summit last week–our first event since we signed our partnership. Esteban Herrera, HfS COO, collected his thoughts on how the SIG Summit compared with typical industry shows. Take it away, Esteban…
The SIG Summit in Review
As you might guess, in the analyst world we attend a lot of industry events, but only last week did I get to attend a SIG summit for the first time, to celebrate and introduce our exciting new partnership. I was absolutely not prepared for what I saw. SIG is a true membership organization, whose members are both serious and proud. The “non-commercial” commitment is honored by all attendees. The summit is fun, but real work gets done.
The differences between the typical outsourcing convention and SIG’s Summits are so stark I had to put them in a table:
Typical Industry Show
SIG Summit
Trade show atmosphere with booths, and untold environmental damage caused by hundreds of thousands of pages of brochures nobody will ever read
No booths, no brochures, no selling. Even the event agenda and information is available as an iPhone App—death to the paper program!
Attendees want business, or a new job
Delegates want knowledge and they like their job
Sessions led by salesmen and publicity-seekers
Sessions led by experts
Attendees skip most sessions because there is so little to learn
Delegates plan on attending almost every session, and are genuinely disappointed about the ones they miss
80% Sellers and 20% buyers. Oh, who am I kidding, its more like 97/3, and the 3% buyers are all there because they are speakers (or looking for a new job)
At least 75% of Delegates were buyers
Sometimes I leave these shows feeling dirty
I left feeling enlightened
Sponsorship is King
Content is King
Inevitably, someone on the conference organizer’s staff has a Charlie Sheen-style meltdown
Dawn Tiura Evans and her world-class staff are composed, helpful and run a simply flawless event
Evenings and networking tend to be—ahem—adult oriented
A family-friendly event through and through
Entertainment consists of seeing which young provider sales person will get drunk enough to put his foot in his mouth first
Entertainment consists of a Brian Olsen painting a portrait of John Lennon to his music in real time (as well as Marilyn, Ray Charles and more…) and then raising over $15,000 for a worthwhile charity by auctioning them off
I have to confess it was fun, also, to have so many delegates approach me about getting their hands on our research, the recently published Latin America report in particular. SIG members now get all our behind-the-firewall research as part of their membership.
Whether you are a buyer or provider of outsourcing services, if you appreciate what we do here at HfS Research, you owe it to yourself to check out a SIG membership as well.
We watched this little movie during the “HfS 25” get-together this week in Dallas… sometimes we have to think a bit more laterally about motivating staff – it’s not only about metrics and money. Enjoy.
Everywhere we go lately, we encounter Outsource Magazine editor Jamie Liddell, as the newly-launched publication looks to get serious in the US and European markets.
Most recently, we saw him at SIG’s summit on Amelia Island in Florida, where he successfully flooded the event with copies of his publication before disappearing to the bar, where the real business was conducted. I, personally, have enjoyed reading Jamie’s stuff over the years – he’s one of the few commentators in our industry who injects personality and humor into his craft, and avoids the dry, passionless, jargon-laden and nauseating verbiage to which we are so often subjected.
So, we’re happy to announce that we’ll be seeing even more of each other now: HfS and Outsource Magazine have formed a research-media partnership.
Jamie Liddell, Editor, Outsource Magazine
Here’s how it will work:
Outsource will feature key HfS research and insight in the magazine. In fact, you can see our first contributions right here;
Jamie will contribute a monthly industry column for HfS. “Liddell lifts the Lid” will, in Jamie’s inimitable style, uncover things you might not have thought of. Look for this coming soon. We coined the title, so lids will get lifted…
Outsource Magazine will promote HfS’ key “State of the Outsourcing Industry” survey to its readership;
Outsourcing Magazine team to treat the HfS analyst team to a round of drinks next time we see them;
We probably agreed to some other stuff as well, but these are the main things.
We’re excited to inaugurate this partnership with Outsource and look forward to opening up a dialog with Outsource Magazine subscribers. And we’re anxiously awaiting Jamie’s lid-lifting contributions to HfS Research…
For those of you who’ve been close to the volatile world of HR Outsourcing, since it leapt into life in 1999 when BP and Exult tied the knot with “E-Enabled HR” (ahem) – there haven’t been too many constants.
I can barely recollect all the providers which dipped their toe in the market before either running for the exits kicking and screaming, or selling off dismally-performing business units. I can also barely recall the number of people who came, saw, conquered, and subsequently disappeared from the face of the earth, after dabbling in one of the most contentious areas of outsourcing we’ve witnessed to-date. I also struggle to remember the number of executives whose careers were either made or broken by doubling-down on that wonderful HRO value-proposition.
However, one face that has been ever-truly consistent – and constantly smiling – during this entire roller-coaster of HR navel-gazing… has been Keith Strodtman, who has been the face of global HRO provider Ceridian through so much of this market volatility.
Yes, HRO’s smoothest man has become part of the HfS analyst family to embark upon a brave mission to define, analyze and expound upon the Future of Work, and how HR service delivery needs to rise up the the challenges of a fast-changing global work environment. Of course, that is when he’s not predisposed to feeding the elks at his Dad’s farm… So without further ado, let’s hear from HfS’ new Research Fellow for HR Services and the Future of Work, Keith Strodtman himself…
The Future of Work – Who Will Lead?
For the past several years I have been thinking a lot about the future of work. Then, when Phil Fersht and I started talking about me joining the HfS Research team as a Research Fellow, I figured this was a great opportunity to start a bigger conversation on the topic and its impact on HR departments, service providers, and employers more broadly.
While most of us frequently think about the future, for me, I never really sat back and thought, beyond the obvious, about how or why the world of work was changing. That changed in 2004 when we invited Thomas W. Malone, the Patrick J. McGovern Professor of Management at the MIT Sloan School of Management to give a presentation on the Future of Work at a customer forum. Tom had just released his new book, The Future of Work, which examines the how new technologies enable companies to unleash the creativity and innovation of the people in their organization.
The key technology outcome that Malone was talking about is the falling cost of communication. Just as the lower cost of communication, think the printing press, helped enable the development of decentralized, democratic governments and markets over the past few centuries; today’s technology is lowering the cost of communication and collaboration in business. Companies are deploying technology that makes it easier for employees, customers, and partners to share information and ideas.
Just sharing ideas and information will not produce success. Companies must organize effectively to capture the innovations that come from the improved flow of information and ideas. They must enable workers to make important decisions, respond to customers, and quickly develop products that meet customer needs. Malone argues that a more decentralized organization, or at least decentralized decision-making, supported by technology, is better able to do respond to customers needs more quickly. It seems like a logical argument to me and there are good examples of companies who are doing this today.
Again, many companies are well down the path of evolving the future of work. The outsourcing industry would not be what it is today without technologies that allow us to move information around the world quickly and at low costs. Many companies use social media to promote their products and get customer feedback. Some have even implemented internal social tools to make it easier for employees to find and share information and ideas. Frank D’Souza, CEO of Cognizant, in his recent interview with Phil Fersht, gave an example of a mobile solution that Cognizant developed for a global consumer product company to allow their delivery people to collect competitive information as they delivered products to retail outlets.
Keith Strodtman, HfS Research Fellow for HR Services (Click for bio)
Okay, so I think we can all see how technology can enable changes in the future of work but there are many other drivers of the future of work. Big macro factors like:
Globalization of the world economy
The speed of change
The aging of the workforce
Millennials in the workforce
Flexible work arrangement, free agents, crowdsourcing, etc.
An increased focus on corporate responsibility
And so on.
Each of these topics alone could and have been the topic of many blog posts. Maybe I’ll get to that later. None-the-less, I believe that visionary leaders who organize and engage their companies to take advantage of these factors will become the “company of the future”. The most successful companies will organize in ways that enables them to capture the best information about their customer’s desired outcomes and unleash the innovative talents of their employees and partners to meet those desired outcomes. Today’s technology makes it a lot easier to deploy such and organization.
So what’s next? Companies need leaders to start thinking about the future of work as part of their business planning processes. Given my background in the HR services industry, I am hopeful that HR leaders will play a big role in this thinking. They are well positioned to understand the capability and talent of the organization. They also have access to more enabling technology they ever before to help engage the entire workforce in creating the future of work at their companies. Maybe your HR service providers help you? If HR doesn’t step up, then maybe someone from finance or procurement will (smile).
Keith Strodtman is Research Fellow for HfS Research, with specific focus on the HR services industry and the critical factors that are shaping the future of workforce development in today’s environment. Before joining HfS Research, Keith spent 8 years as the leader of the HR Outsourcing business at Ceridian, one of the largest HR service providers in the world. Prior that he was director of HRO solutions at PricewaterhouseCoopers and was at Fidelity Investments during the launch of their HRO business. You can access Keith’s full bio here and contact him here.