If there’s one person who’s been a consistent figure closely tied to the development of Finance and Accounting sourcing over the last decade, it’s Paul Nowacki (or to those of us know him, simply “Wacki”), who today leads F&A transformation for leading sourcing strategy and implementation consultancy, Everest Group.
Paul’s advised on several of the largest engagements in the business (in fact, I do think he’s worked on the largest) and taught me a lot about the space when I worked with him at Everest a few years’ back. Never afraid to speak his mind, Paul is always a popular figure at industry events to talk about what our industry needs to do to get to that next level of performance. He’s truly a “been there done that guy” who’s seen it all… Anyhow, I managed to drag Paul away from his favorite past-time of tracking global financial indices and stock markets (no joke, he does that for fun) to talk to us for a while about finance transformation and global sourcing:
Phil Fersht (PF): Paul, firstly, what are the main issues you’re hearing from your clients these days? What are the main contrasts between now and before the economic crash last year?
Paul Nowacki (PN): The trend toward smaller deals is accelerating. Cost pressures on the buyer community are so great that companies are evaluating small deals that they did not bother to consider in better times. This in turn is putting new pressure on the supplier community, that is, to find ways to provide cost reduction to buyers and make a profit on ever smaller deals. We are really seeing the envelope pushed on the question of how small is too small. There is also increased focus and pressure on the first year impact of deals. In better times, the focus was on the life of the deal economics, now first year impact is equally important.
PF: How are they approaching F&A transformation? Are they increasing focus on BPO and away from captives?
PN: There is significant growth in captives, for engineering, supply chain, R&D, and a number of other functions, but not for commodity F&A transaction processing. Companies recognize that the suppliers have mature offshore F&A capabilities, so when it comes to the make or buy decision, they are buying. When it comes to transformation, it is being baked into the outsourcing agreement. The old idea of transform it and then outsource it is dying.
PF: We’re hearing a lot more about outcome-based pricing in maturing areas of sourcing, such as IT infrastructure and applications. How is this impacting F&A engagements today, and do you view this as becoming increasingly important?
PN: First of all, the term ‘outcome-based’ is an often misused and misunderstood term. Most people who apply that term are using it broadly to represent both transaction-based pricing and business outcome-based pricing. Gainsharing payments for collections work is an example of business outcome-based pricing. Transaction-based pricing, such as the number of invoices processed, is really output pricing rather than outcome pricing, and it is becoming more important to both buyers and providers. However, both buyers and provides are finding that it is not a simple task to properly calibrate the appropriate unit price for various volumes of activity. What is emerging is a hybrid situation: contracts that call for an initial period of FTE pricing followed by implementation of transaction based pricing which allows both sides to take their time to correctly calibrate the unit pricing.
PF: Do you see genuine opportunities for hybrid BPO-IT offerings in F&A, for example, SAP R/3 financials being delivered in a Platform-BPO engagement model? Or is it simply too challenging / expensive to reconfigure most companies’ general ledger data repositories to move them onto these utility models?
PN: If you have not made a large investment in systems, have been growing from a small company to a mid-size company, are starting to outgrow your systems, and are facing a make or buy decision for new core F&A systems, the platform option is a viable alternative. However, the large established firms have ERP systems that have been heavily invested in for many years and are integrated with every other system in the company. These systems also have interfaces with customers, suppliers, and financial institutions. Given the current state of the art for platform BPO for F&A and the associated switching costs, the vast majority of large established companies will not be platform adopters in the immediate future.
PF: We’ve also seen advisors try and step up and deliver governance services, but many have found this challenging (clients don’t exactly ring up and ask to “buy some governance”). What – in your experience – is working, and what isn’t, in F&A BPO environments?
PN: It is challenging for a couple of reasons. First of all, the true core function of governing (cost stewardship, the alignment of business strategy with service delivery, relationship management, etc.) should never be outsourced, so when we talk about governance services we are talking about the administrative and tactical aspects of governance and the tools that support those tasks. Secondly, the service providers are getting ever more sophisticated in the tools that they provide clients with respect to SLA and metrics dashboards, so the opportunity to add value to buyers with these tools is diminishing over time.
PF: And finally, you’ve been close to many of the largest F&A BPO engagements for many years now. What are the three key developments you expect to see in the next couple of years, based on your vast experience of this industry?
PN: One: platform BPO for F&A will grow in the small and mid-market segments. Two: we will see some supplier rationalization. Currently we are seeing some supplier consolidation due to M&A activity, but new FAO suppliers are being created as fast as or faster than suppliers are being acquired; not all of these new suppliers will be viable long term. Three: we will see a maturing in FAO pricing with fewer input based deals, more transaction based pricing, and a better understanding and standardization of transaction based pricing.
PF: Paul – thanks for sharing your views with us today.
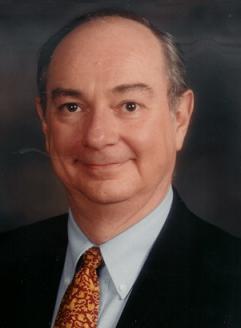
Paul Nowacki (pictured here with wife Kathleen) is Associate Principal for sourcing strategy and implementation consultancy, Everest Group with multiple leadership responsibilities including leadership in finance and accounting consulting advisory services. Prior to Everest, he was a senior operations executive for DuPont. He has over 25 years of professional experience spanning industry, consulting, and Wall Street. Paul has an MBA from the Lerner Business School, University of Delaware.
This truly has been a pivotal quarter for the outsourcing business. As we've discussed several times here, many services contract decisions have been delayed during the economic crisis while organizations worked out the best course of action to get through the downturn.
In Q3 we've started to see definitive action, with many service providers meeting, and some even beating, Wall St. expectations. But while some providers are clearly delivering, others are struggling to compete in this "new normal".
So what is this "new normal"?
Operational service provision is commoditizing and leveling the playing field. Coming out of the recession, there is a backlog of engagements which are largely labor arbitrage-focused and it's often a question of price balanced with the promise of delivery performance for most clients. There isn't a lot of secret sauce these days for what many clients are currently demanding, where in the past, incumbent service providers could play the "capability game". With many of these skills becoming mainstream, the competitive playing field has leveled out.
A not-so-secret sauce is undermining the business models of the old-guard. When selecting a provider in commodity services areas such as ERP software development and maintenance, or transactional accounting processing, it's getting harder and harder for the traditional branded service providers to command higher price-tags against the new breed of offshore service provider. Essentially, everyone's competing for the same pool of talent in commodity areas these days, and for some providers used to commanding higher multiples in the old days, they simply cannot compete effectively anymore. This is especially the case where clients simply want technical support, without significant business transformation.
The recent round of financial results from the service providers is confirming this new reality - and it's happening at a fast-pace in this environment, which is alarming the old-guard. The crux of the matter, coming out of the economic crisis, is that most clients are not yet ready for real business transformation (even though many need it) - that will come further down the road. Their current requirements are to take advantage of operational arbitrage opportunities, and this market is a long way from becoming saturated. For example, 75% of ERP services are still being delivered onshore – hmmm… that's a lot of room for future labor arbitrage.
The winners in the arbitrage game have a future seat at the table for higher end services, but need to reinvest to deliver. Those providers proving operationally-efficient and cost-competitive to win the less sexy work today, will find themselves in a strong positiong to push higher-end business transformational services in the future, because they will already be present within clients delivering operational work. They need to demonstrate they are capable of learning their clients' businesses, in order to move up the value chain to take on more consultative work.
However (and it's a big "however"), in order to move up the services value chain, the winning providers of today need to invest in their talent, their IP, their global delivery platform and their industry acumen to prove they can deliver more innovative services down the road. They need to develop, either through organic investment, or through smart acquisition, this capability to help their clients find the next phase of efficiency gains for themselves and new sources of revenue. Hence, while clients demand cost-arbitrage today, the next wave of efficiency gains can't continue to be found from swapping out higher cost for lower cost (which we discuss here). They're going to come from doing things differently and re-wiring their operations.
The struggle for differentiation. With several providers that can deliver essentially the same service within a narrow price-band, it's getting very tough for some to break out of the pack to prove they warrant being the long-term partner of choice for a client. Simply put, a client needs the following: a provider which is financially sound and is re-investing in its global delivery platform, and has a stellar track record in delivering results for its clients.
Trust trumps brand. Customer references are critical in this business. A consistent voice from multiple customers is now the tell-tale sign as to whether a provider can deliver. In most cases, where a clients have unique requirements, they have to take a leap of faith in whomever they select. It's no longer all about brand and executive relationships for smart customers today; it's about having a unique culture that encourages clients to trust their provider to deliver results and to explore constantly new avenues to make them successful.
All-in-all, as we discussed recently, those business that persist in the old way of doing things will go by the wayside, and the service provider landscape is certainly no different. There's a changing of the old-guard happening, and at a speed which is making it increasingly worried.
Attend any European analyst meeting and there’s one character guaranteed to be propping up the bar. Scratch that, there are normally about 50 analysts propping up the bar. But in the midst of the throng you will undoubtedly find the stolid Euan Davis of Forrester Research.
I recall a conversation with Euan back in '95 when I told him “you should give this analyst lark a try” (If you want to know what he working on in those days, drop me a note…). Anyhow, the story began from there, with Euan rising through the ranks at IDC’s European operation, making a curious detour to Yankee Group, before finally attaining new heights of stardom and adulation with Forrester.
Euan now boasts the words Principal Analyst in his job title and waxes lyrical about IT services in the Eurozone. Ask anyone in the industry and you’ll discover he’s fast becoming one of the most popular analyst figures on the European services circuit. And, despite the fact he once lost to me at tennis (a shameful occurrence for any man or beast), he still warrants an airing on the Horses…
Phil Fersht (PF): Euan, firstly, what are the main issues you’re hearing from your Euro clients these days? What are the main contrasts between now and before the economic crash last year?
Euan Davis (ED): The issues are many and varied but if I was to distill it down to what I see as the issues that clients are facing today then they fall into three categories: Some are “firefighters” and are looking to reduce costs wherever they can, pushing for discounts and getting economies of scale through aggressive supplier consolidation. Others are “explorers” and are directing energies into investigating a host of emerging options for IT service deliver—and business process outsourcing is one such area. The exciting ones to watch for my money are the “builders.” These firms are sinking the foundations that underpin a profound shift in their operating model architecture, IT/business redesign, and supplier engagement models. These firms are building hybrid operating models driven by a structured sourcing frame works, regulated through a retooled service management structure, and connected to a core set of suppliers. And the recession has speeded up the process of change.
PF: With ITO are you seeing more clients moving to broader managed services and away from staff augmentation, or is it the same story of project based spend using offshore resources?
ED: It makes sense for clients new to global delivery or offshore outsourcing to begin on a staff augmentation, time-and-materials basis as a way to gain experience and reduce initial risk. But such relationships have a tendency to stick — conversations with my clients reveal how stakeholders insist on such one-for-one relationships in mainland Europe anyhow before moving to more remote IT delivery models. But I do think this is starting to change. When engagements are based on staff augmentation, little motivation exists for the client and provider to concentrate on improving software development processes, for example, which can potentially have an economic impact greater than the labor arbitrage itself…I see a part of my job is to educate and persuade them otherwise and many are get this.
PF: Which European nations are stepping up sourcing initiatives since the recession? What are the contrasts between the behavior of British, French, German firms? Are other European nations getting more aggressive with BPO/ITO?
ED: The IT services industry in Europe continues to mature, with global delivery strategies superseding traditional offshore approaches—so if I was to characterize sourcing, I would characterize it around the use of global delivery rather than BPO. First, movers with standard IT process models configured for sourcing maturity fully exploited global delivery; but now I see a second generation of clients exploring the services on offer and how these can be tuned to uniquely serve European firms no matter where they are. Skeptical stakeholders are starting to understand the commercial imperatives propelling global delivery forward in the Nordics, Germany, France, Italy etc and how blending global delivery allows deal-makers to hedge its risks. My advice is that European firms need to quantify the interplay between cost and risk and then tune the model around the blend of onshore, nearshore, and offshore resources. They then need to invest in vendor management functions.
PF: Do you see specific industries getting more active across Europe? And how are the European banks approaching sourcing these days – have many put their sourcing plans on the backburner, or are they now stepping up?
ED: Questions fielded by Forrester’s sourcing team have revealed to me what life's like at the sharp end of the banking crisis for an embattled executive. An examination of our inquiry traffic among banking clients highlights three core outsourcing topics that banks are trying to address: offshore, business process outsourcing (BPO), and selecting the correct outsourcing model for their firm. What interests me are the new operating models built by the COO office, the enterprise architects, and strategic sourcing that are beginning to connect siloed divisions together. I fully expect to see new IT services-led consumption models build around an ecosystem of vendors—systematic multisourcing—which will offer a profound shift in technology value.
PF: So what do you see next on European companies’ agendas in the medium term? Is it going to be all about cost-containment, or do you see a greater focus on innovation with their approach to global sourcing?
ED: Depends on how strategic the sourcing function is run: firefighters will be pushing for discounts and cost reduction while those using the recession to deconstruct IT delivery and reconfigure it around innovation. I see my clients setting the parameters for inter-provider collaboration—so across multiple providers and across multiple service towers like the banks in the previous answer. It’s a trend in the outsourcing industry that I have noticed for some time now—this shift from global, single-source deals to a world of multiprovider relationships. What I think you’ll see start to happen is more structured approaches to sourcing as executives work on integrating multiple IT services from their IT providers through overarching governance mechanisms—what I call systematic multisourcing.
PF: And finally, you’ve been an analyst since the heyday of the Internet boom, the onset and maturing of global sourcing, while tackling two recessions. How do you see the analyst and consulting industry evolving? Do you see the impact of social-media (blogs/twitter etc) blowing up the delivery models, or is it just a lot of hype?
ED: Well I am really starting to feel my age when you put it like that Phil! You know what firms need are trusted advisors that can help them in making the right decision about an IT provider, whether to use the cloud, single source versus multisource or whatever. That is the role that I see consultants and the analyst industry should be doing. I also see the value from social media allowing clients to make IT services decisions, inform others of those decisions, execute and monitor the outcomes, and report them to their peers. This is where the power of digital media resides. But the greater power is still vested in the oldest information source open to executives: word of mouth shared with peers and colleagues. IT services market information — whether vendor intelligence, pricing trends, or contracting best practices — comes to those that network for it and that it what an analyst worth his salt should be doing. These emerging social technologies propel these networks forward, adding value at different stages of the outsourcing life cycle.
PF: Spoken like a true analyst, Mr Davis… thanks for your time today
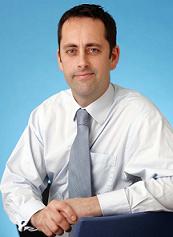
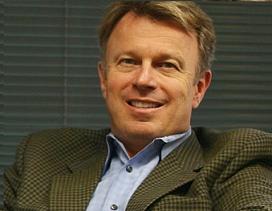
Euan Davis (Pictured) is Principal Analyst for Forrester Research, based in London, where he writes and consults for Forrester's Sourcing & Vendor Management professionals and is recognized as a long-standing expert in IT services and sourcing-related issues. He lives in Cambridge, England, with wife Hannah and two kids, Rosa and Oliver. In spite of his one embarrassment, he is a fine tennis player, avid connoisseur of real ale and cheap wine, and also an accomplished skier.
Our recent discussionon Xerox's acquisition of ACS certainly served up some meaty discussion, and even got picked up by CIO.com, among other media.
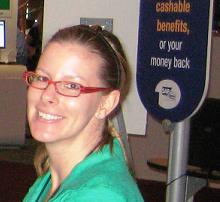
My dear friend, and former colleague at AMR Research, Dana Stiffler(pictured), recently sent us in some of her views on the merger. Dana actually got promoted today to VP and Head of Research for AMR's services research, where she will be offering clients "cashable benefits, or your money back" with her group's output.
Anyhow, thought this a good time to showcase her talent… Over to you, Dana:
Xerox-ACS: Cloud Services Potential, or Dinosaurs Huddling Together for Warmth?
Xerox is the latest in a long line of technology manufacturers to realize that its future lies in services, not products, particularly in the B2B value chain. Once manufacturing and supply chain efficiencies have been wrung out, it’s time to turn to top-line opportunities: services that use product heritage as a foundation. The fastest way to acquire these capabilities is by acquisition. Xerox’s predecessors in this journey include IBM, Fujitsu, Hitachi, HP, and, just recently, Dell, with its acquisition of Perot Systems.
In this case, Xerox’s target is Affiliated Computer Systems (ACS), a $6.5B, Dallas-based outfit best known for its broad set of business process outsourcing (BPO) services. The acquisition makes sense when Xerox and ACS executives talk about synergies in document management and transaction processing, though there’s some distance to travel to put together a viable offering and go-to-market strategy, even for this supposed sweet spot. The two companies’ traditional target prospects appear to reside in different universes: ACS’s in the finance function and strategic sourcing, and Xerox’s in administrative operations and procurement.
Important areas within ACS likely to languish post-transaction include the company’s burgeoning technology outsourcing business, as well as broader, full-scope, back-office offerings like finance and accounting services (the jewel in ACS’s crown) and human resources outsourcing. ACS businesses most likely to retain executive attention and investment are the more targeted processing products in healthcare, government, and financial services. Xerox had already made investments in mortgage processing as well as litigation support.
The combined entity will need to move quickly to prove to Wall Street that the transaction is about delivering industry-focused, asset-based business services (hint: use the word “cloud” a lot—they love that), rather than two dinosaurs huddling together for warmth.
Dana Stiffler (pictured), is Vice President and Head of Research for AMR Research's Global Business & Outsourcing Services Practice
There's little doubt about what's been providing the rocket-fuel behind the rebounding services business: IT outsourcing. Simply put, there are plenty of eager providers to choose between, they have access to most of the technical skills companies need, and their rates are far cheaper than retaining or hiring staff inhouse. Some are also getting pretty handy at becoming consultative business partners, and not simply low-cost body shops. Our recent study tells the real story – 50% of enterprises are either kick-starting, or scaling-up, their ITO right now. "So tell us something new", I hear you groan into your laptop screen…
What's different as we emerge from this crisis, is that the perceptions of IT from the other parts of the business are becoming increasingly cynical in many companies. Many companies are hiring new CIOs with the mandate to "turnover half the department, or outsource it", and IT middle-managers are being seriously questioned about the value they are adding to the business. While much of the bottom-layer of IT has already been contracted out, it's now the middle layer of IT professionals which is under threat. CIOs are under pressure to prove the value of maintaining these heavy middle-layers, or move them out of the organization. Some CIOs are already operating under the strategy of hiring a few people who "genuinely get it" to drive IT value, while outsourcing as much of the operational work as they can.
Remember marketing in the '80s and early '90s, where firms had these bloated marketing departments doing multiplous tasks such as PR, communications, database management, which used to be so critical to keep inhouse etc? Today, nearly all CMOs surround themselves with a handful of folks who "get it" and parse most of the operational work out to agencies. That is the norm today, and no-one questions it.
My fear for IT, is that it's going down a very similar path. Or should this really be "fear"? Maybe this should be "hope" of much-needed change? CIOs can't exactly hire 20 people over night who "get it"; firstly, they may only know a couple of suitable people who'd be prepared to join them, and secondly, they'd likely have a hard time getting the requisitions for a lot of expensive high-end IT talent which can apply innovative-thinking and new technology to source fresh avenues of revenue and productivity for them.
So the middle-layer of IT has a shot at saving itself - their CIOs need to pick talent that can prove their business value to the firm and mould them into the IT engine of the future. I do not believe that IT is going the way marketing did, but it does need to step-up a gear and win-back credibility from the cynics who simply want to offload the excess fat in this economy. That means CIOs need to train their staff to think out-of-the-box, to learn how to work more effectively with the business units, and to bring technologies into the organization that can truly impact the business and the corporate culture, such as virtualization, Cloud, video-conferencing and social media.
I do believe we're genuinely arriving at a critical juncture in the IT world, where it's time for CIOs shape-up their teams, or look outside of the organization to regain the lost credibility.
Before you tuck into your Thanksgiving turkey and guzzle a gallon of bad quality Chardonnay, please take 10 minutes to complete our industry-wide study entitled "The New Normal in Outsourcing Delivery". And if you're in Asia or Europe, currently giving thanks for US declaring itself independent from everyone else, this includes you too.
Anyhow, we are actively seeking the collective opinions and experiences of services customers, providers, and advisors and need 10 minutes of your time to complete this quick survey, designed especially for the patience-challenged, attention-deficit-inclined executive. Simply click on the following link:
All individual responses to the survey will be maintained strictly confidential. In return for your time, you'll receive a free write-up of the survey findings (wow).
We have partnered with the member communities at Global Services Media and the Shared Services & Outsourcing Network to ensure a powerful global participation of decision-makers and senior executives engaged in outsourcing delivery services. Please do participate and help advance our collective understanding of the industry.
Please note that "Horses" is a free resource for the sourcing industry at large, and the purposes of this research are to further all our knowledge and understanding of the direction of the global sourcing industry, whether you buy, sell, advise, criticise, market, commentate or analyse sourcing delivery. And if you do neither of these activities, please seriously question what you're doing here in the first place -:)
For once I am stumped for a title. The one man who had successfully escaped my previous attempts to feature him has finally been caught. Either his career has nose-dived and he's now desperate for some publicity, or the "Horses" now gives that 15-minutes of fame people so badly crave. I hope it's the latter -:)
Yes – we have the one-and-only Lowell Williamsin a two-parter…
Lowell, quite simply, is the most respected practitioner in HR Outsourcing. Not only has he spent many years as an actual HR leader, he also worked for the "original" HRO provider Exult, moved into the sourcing world with TPI, before joining Equaterra in 2004 to head their HRO advisory practice. He has been responsible for many HRO engagements – and he has somehow survived to tell the tale. He also became the HROA's "Person of the Year" in 2008… an honor only bestowed to the most lovable scoundrels in the outsourcing world. So without further ado…
Phil Fersht (PF): Lowell, firstly, what are the main issues you’re hearing from your clients these days? What are the main contrasts between now and before the economic crash last year?
Lowell Williams (LW): We have survived the worst of the crisis, and clients are beginning to plan for the medium term. We are entering the still dangerous waters of post-crash recovery and stabilization, but most executives are no longer poised on the windowsill while updating their designation of beneficiary forms. As they approach having to slim down selling, general and overhead costs, company executives are again turning to shared services and outsourcing, but they are very anxious to have the most rapid payback and to minimize capital outlay. This has led to an explosion of interest in Software as a Service (SaaS) which is a phenomenon not unlike the new Obama national health plan. Everyone is talking about SaaS and software sellers and providers are announcing new alliances and products constantly, but we cannot say that there is a large volume of experience with SaaS out there. SaaS, outsourcing (especially to cost advantaged areas) and shared services are the dominant themes of the post-apocalyptic world.
PF: You’ve been such a consistent figure in the world of HRO over the years, since its early days.. Will we ever see a return to the glory days of end-to-end HRO deals, or is it all going single-process now? What related areas to HRO are we beginning to see developing (for example legal work / compliance)?
LW: If I were willing to sing a tune here, it wouldn’t be “Glory Days” but I wouldn’t turn to the first stanza of Joan Baez’ immortal ballad on aging either: “Today there’s no salvation; the band has packed up and gone . . ..” HRO deals involving 45,000 employees, transition of 15 countries and outsourcing of 15 processes all on a Big Bang cutover date are things of the past. There will continue to be large transactions, but the phasing of transitions and the clustering of related processes and geographies arelogical maturity indicators in this business showing that providers have learned to temper their own ambitions for revenue and to resist client demands to do illogical and highly risky things. One evident process cluster is Core Processes, such as payroll, employee data management, call center, and HRIT. A second cluster groups Human Capital Processes, i.e.,performance, learning, succession, employee development and deployment. The clustering of HR processes with limited geographical footprints for each transition wave is a healthy way forward, and many top tier providers have already converted to this model.
PF: Do you see the more HR work being conducted offshore in today’s climate?
LW: Yes, the inexorable trend is to do more process work offshore. In EQ we track offshore service work using the Advantaged Cost Ratio ™ Index. This index measures the total percentage of services from low cost service areas, such as the Philippines or India, to the total cost of services from all geographic service points for a given client. Outside of limited call services and highly technical areas of benefit and equal opportunity compliance in HR, there is no reason why low cost, stable shared service centers or outsourced service centers that are offshore should not be used. Offshoring is a dominant element of this business and it will continue. There is no economic or political reason to retard or halt the process of offshoring services. Offshoring does impose on clients an absolute need to audit performance and capacity, to ensure that data recovery and business continuity procedures are in place and tested out and to be aggressive in ensuring that systems are backed up and that service centers are located in stable areas with good infrastructure. We believe that some service center developments, including outsourcing centers, have been too opportunistic and have not reflected careful political risk assessment. Political risk and stability of workforce are more important than cost comparison, and those factors should take on an increasingly important role in the choice of service location over the next several years.
In Part II, we will discuss platform BPO, something about governance… and some of Lowell's predictions for the future in our strange little world…
One of the advisors which has really made a strong move in the sourcing business this year is Alsbridge. Much of that has been down to its strong track record with clients, but its also made some canny investments to augment its advisory services. One of these I've had some exposure to is ProBenchmark, which has been running some excellent webcasts looking into how pricing trends and dynamics in IT services.
I caught up with CEO Ben Trowbridge the other day, and he wanted to let us know about a webcast ProBenchmark is running next week – you can register here. Plus – for all you cheapskates… its FREE (Wednesday 10th December at 2.00pm EST).
Anyhow, I managed to drag Ben away from a hunting outing for a few minutes to pose the following questions:
PF: Which IT services have fluctuated in price the most?
Ben Trowbridge: While pricing for most IT services is still in a downward trend, Server and Storages prices dropped dramatically throughout 2009. They declined most rapidly between Q1 and Q3, but in Q4 we are seeing deceleration of this trend which we expect to stabilize by the end of Q1 2010. For pricing intel on 2009 trends and the year ahead, you can attend our webinar on December 10th?
PF: Pricing fact or faux: Are we getting the same service mix?
Ben Trowbridge:That’s a great question. The fact is that prices are dropping and the economic downturn has truly been a catalyst – but buyers are getting less “bang for the buck” than expected. Example: vendors are disaggregating services and creating component-based service structures. When you add the components back to original configurations, the savings are much less than promised or expected.
PF: What do clients need to do to “stay on top”?
Ben Trowbridge: Understanding both market dynamics and details of your service structures is critical for success. It’s not enough to know the pricing trends and expect an X% reduction in the cost of your contract – you have to get into the fine print and match components to components and configurations to configurations. Most companies now use benchmarking throughout the contract term in order to truly match services to reduced market prices.
Firstly: my apologies to everyone for hopping on the perennial "Predictions Bandwagon". One may as well say "Stop press everyone, I'm just such an important smarty-pants you should listen to ME ME ME!" As Newt Gingrich told us earlier this year: "There is not one living being that can accurately predict the outcome of this crisis, all we can do is continue the dialog and the answers will slowly unravel".
Secondly: we've conducted two major studies with outsourcing buyers globally this year (and am currently sifting through 800 responses – and counting - from our current industry study). While we can evangelize, prophecize, pontificate and sermonize, nothing can substitute for real data on what everyone is currently doing and planning to do. We have the platform here to do that, and I personally thank all of you who took a little time out to share their views, actions and intentions.
And Thirdly: I'm just such an important smarty-pants you should listen to ME ME ME!" So maybe I can help with the unraveling?
i) CIOs and CFOs will be uniquely challenged to avoid becoming "Cartoons of the Recession".
Simply put, when there's a serious recession in the works, the job of the CIO is relatively simple – cut costs and squeeze your suppliers using whatever means are at your disposal. CIOs rarely get fired in this scenario, unless they somehow messed up the cost-cutting.
Their real challenge is when we emerge from the recession; the spotlight is firmly on them to deliver value. They are, quite literally, drowning in options, and it's a major challenge to convince their peers they are capable of driving new business value into the organization. CFOs will be similarly challenged by the fact that they are going to have to prioritize investments versus cost-containment initiatives, exacerbated by the realization we're moving into a period of drawn-out economic uncertainty, and not the classic economic recovery-cycle. Their options are as tough, if not tougher in this "New Normal". Outsourcing is one key component to help crystallize these options – driving out cost, while creating new avenues of possibility. The CIOs and CFOs who "get" sourcing will be in the driving seat.
ii) Labor arbitrage will continue to dominate outsourcing, but the smart providers will be focused on providing consultative value to their clients.
Most new outsourcing contracts are still dominated by customers which have got lots more room for maneuver with labor arbitrage. Sadly, this will continue to dominate most of the deals in 2010, and we'll see the tiresome cost-per-FTE price battle continue.
When you consider that 75% of service provider staff for ERP development and support are still onshore, there's a lot more wiggle-room for new and existing clients to cut costs through lifting-and-shifting work offshore. With commodity services areas such as ERP software development and maintenance, and transactional accounting processing, it's getting harder and harder for service providers to command higher price-tags in this New Normal.
Those providers proving operationally-efficient and cost-competitive to win this labor arbitrage work today, will find themselves in a strong position to push higher-end business transformational services in the future, because they will already be present within clients delivering operational work. They need to demonstrate they are capable of learning their clients' businesses, in order to move up the value chain to take on more consultative work. Those providers which only focus on providing cheap body-shopping for commodity services, will get usurped from the market quite quickly. Worst still, not many of the leading providers are likely to acquire competitors which only have a transactional skill-set and low-value client relationships.
iii) Sourcing advisors will increase their influence in the market.
As the analyst business consolidates, many business leaders are looking further afield for inspiration, validation, data and advice. Especially in the sourcing world, where the best advice is often coming from those living the experience in the field. Our forthcoming survey results will reveal this is happening. Business decision-makers today need advice that can be made available in personalized models from experts that can deliver it. The smart advisors are going to be those which can adapt and scale their experienced talent seccessfully in a semi-customizable model.
iv) We'll see at least two mega-mergers among the service provider-base.
We'll see a couple more mergers on a similar-scale to Dell/Perot and Xerox/ACS. Expect at least one involving a traditional incumbent and an Indian-HQ-ed service provider, and at least one other between one of the pure-play BPOs and an IT-centric services provider.
v) BPO will rebound to have its strongest-ever year.
2009's been a somewhat damp-squibb for mega-BPO deals, and while we've seen a lot of small-engagements and a few captive buy-outs, a lot of BPO decisions were delayed due to the crisis. As expected, ITO's been the first to emerge strongly from the recession, as this is the most mature market where deals are transacted fairly quickly today. However, for many companies, especially those which have already outsourced much of their IT, the next wave of obvious cost-savings are to be found in BPO areas.
As our soon-to-be released new survey is revealing, transactional finance and accounting BPO will have a resurgence in 2010, with additional interest in management reporting, and we'll also see a fresh wave or HR outsourcing, which has been quiet for a couple of years now, with new uptake in payroll, benefits admin and recruiting outsourcing. Procure-to-pay outsourcing is poised to accelerate, but we are unlikely to see muchrenewed traction in strategic sourcing services. We'll also see renewed focus in the analytics space across several verticals and horizontal areas.
vi) Cloud will emerge, but its definition and concept will get diluted and confused.
Yes, Cloud is the future and a major game-changer, but - like everything else in the IT world - the definition and meaning will get diluted and confused (remember SOA, EAI, CRM, E-business etc etc). The winners in this game will be those providers which can articulate exactly what Cloud means and how companies can start evaluating Cloud-based delivery models. Cloud will become closely intertwined with outsourcing, and we're already seeing many service providers developing their Cloud-strategies.
vii) The speed of change will become frantic and frightening for many.
While in the good ol' pre-crisis days, firms could take time over major (and sometimes disruptive) business decisions, companies today are having to make them much more quickly, and move much more aggressively to execute on them. This is particularly relevant where outsourcing is concerned.
As we've seen in the past few months, many of those sourcing decisions that were delayed during the first half of the year, quickly came to fruition recently, as firms realized economic armageddon has been averted, and it's time to roll-out the new corporate agenda: quickly and aggressively. 2010 will not be a year for the timid, and we'll have a lot of frantic people trying to grapple with outsourcing - we'll see more political pressure, more negativity, more case-studies, more value propositions, more momentum and more energy than we've seen yet in this crazy industry.
viii) And finally…
I predict England will win the 2010 World Cup. Now you know how accurate I am -:)
So here's the eagerly-awaited second part of the Lowell Williams experience, where we decided to give him 30 minutes of fame. Over to Equattera's HRO mega-star with the handbrake firmly in the off position…
Phil Fersht: Lowell, we’ve had a lot of talk on here about “Platform BPO”, where clients essentially take on a standard SaaS-delivered platform, supported by business processing services delivered by a BPO provider. How do you view these “on-demand” business services? Isn’t this just a win-win for the software providers, with limited value for the BPO provider? How can service providers differentiate their offerings in this type of model?
Lowell Williams: As mentioned above, many HR and IT executives
can no longer justify large capital outlays for classic license and install platforms, nor are they willing to commit the operating capital to maintain such systems. A number of smaller, more flexible, and less ready to customize providers is already discernible in this market space, such as Workday, Northgate-Arinso, Caliber Point and recently” Xercs” (our temporary trade name for the combination of Xerox and ACS). For SaaS to work, however, client companies need to realize that customizations will not be possible to any great degree. SaaS is a truly one-to-many model, and the burden of all customizations will fall back on the client company. In addition, allowing any substantial customization or personalization will degrade the cost curve and performance as well. Not all companies can accept that reality. Embedded in many of our HRIT systems today are routines and programs that we believe give us competitive advantages in employee treatment. If we are going to make SaaS work on a wide scale, we will have to find a way to take those custom elements out of the HRIT system. The largest pure SaaS model today is Workday, and it has just over 100 customers, many of which are not in transition to full service yet, so we have a very long way to go on SaaS. We are also a long way off from being able to compare the Total Cost of Ownership of a classic platform such as SAP with an SaaS model provided by SAP.
Phil Fersht: Are clients getting better at governing BPO these days, or are you seeing them making the same mistakes over and over again? Can service providers do more to help their clients govern sourcing engagements better?
Lowell Williams: Generally clients are refining their approaches to governance, although many of them still try to scale a model that was appropriate for the governance of a health or savings plan to a large scale HRO transaction involving multiple countries. Not enough clients use appropriate toolsets, and thus the client team gets bogged down in building spreadsheets and crunching data rather than automating that function and concentrating on structural trends and major developments in building better relationships. The early promise of best practice flow through outsourcing is still a largely unrealized ambition. While some best practices are actively promoted by the industry, those practice improvements tend to be what is beneficial to the provider’s margins or cost structure. There is very little convergence of academic HR work on best practices and improvements with providers or their clients. For instance, I can only name one or two HRO providers that have a functioning advisory council on HR best practices, and we are missing a major opportunity to develop truly grounded, researched and articulated HR practice appropriate for an outsourced or shared service HR environment. Best practices are as much as a part of governance and relationship management as costs and service level performance. If providers truly want to be partners, governance has to become more about a better mutual mousetrap than about reporting on call center statistics.
Phil Fersht: And finally, what’s next in this strange world of outsourcing? What do you see happening in the next decade? And how will the economic crisis change executive thinking with global sourcing in the long-haul?
Lowell Williams: The new Flat Earth Society will become the dominant mindset. We will have to globalize the sourcing of talent as the OECD nations face the retirement or partial retirement of the Boomers. Visa practices, cross cultural training and learning to segment work tasks around the globe are the dominant themes of the next years in HR services, and for that matter in finance, IT and procurement services. Work flow must be globalized, and the race will be to those companies that master best performance for best price in serving themselves and their customers. You asked earlier about legal service outsourcing. Why should we pay to draft patent claims in Washington, DC when we can get the same services in Cape Town at 1/3 the price? Why should be use actuarial services in Chicago for our pensions when we can buy better services in Kiev or Hyderabad and for a better price? Our corporate production and growth engines must use better work flow, better task sourcing and smarter global sourcing models to direct work to service centers that reflect best site/best service/best practice and best value As executives look to their competitive future, this crash has reminded them that competition for mindshare and walletshare is never-ending, and they must retool their organizations to compete though astute sourcing and shared services on a global basis.
Phil Fersht: Thanks for your time, Lowell. Everyone here will love reading your views.
Lowell Williams (pictured above) brings 30 years of international HR, HRO and HRIT expertise to his role as EquaTerra’s executive director for global HR services. Before joining EquaTerra at its inception, Lowell was an HRO executive at TPI, executive director at Exult, vice president for global HR at Bull Information Systems, and senior vice president and general counsel at Elf Aquitaine. He is very engaged in economic and labor policy, active in religious affairs and local community.


 Paul Nowacki (pictured here with wife Kathleen) is Associate Principal for sourcing strategy and implementation consultancy, Everest Group with multiple leadership responsibilities including leadership in finance and accounting consulting advisory services. Prior to Everest, he was a senior operations executive for DuPont. He has over 25 years of professional experience spanning industry, consulting, and Wall Street. Paul has an MBA from the Lerner Business School, University of Delaware.
 This truly has been a pivotal quarter for the outsourcing business. As we've discussed several times here, many services contract decisions have been delayed during the economic crisis while organizations worked out the best course of action to get through the downturn.

 Firstly: my apologies to everyone for hopping on the perennial "Predictions Bandwagon". One may as well say "Stop press everyone, I'm just such an important smarty-pants you should listen to ME ME ME!" As
 As our soon-to-be released new survey is revealing, transactional finance and accounting BPO will have a resurgence in 2010, with additional interest in management reporting, and we'll also see a fresh wave or HR outsourcing, which has been quiet for a couple of years now, with new uptake in payroll, benefits admin and recruiting outsourcing. Procure-to-pay outsourcing is poised to accelerate, but we are unlikely to see muchrenewed traction in strategic sourcing services. We'll also see renewed focus in the analytics space across several verticals and horizontal areas.


