Remember our mystery blogger who evangelizes on best practices for vendor management? Well that mysterious individual has challenged me to a predictions dual this morning (gasp), where he /she said "I'd be willing to wager a drink on who gets a higher percentage right. After all, I didn't bet on England in the World Cup, so I'm pretty optimistic :)" We'll see about that sunshine…
"After testing outsourcing’s shallow waters, companies new to outsourcing will cliff dive into the deep end without further investment in governance, only to find that pool parties should be supervised by a lifeguard and that the pool is more shallow than they think."
Agree 100%
"Allow me to coin a new term, Vendor Management Organization Outsourcing (VMOO), which also has an easy to pronounce verb version: to “vmoo” or “vmooing.” In 2010, the big outsourcing companies, like Accenture and IBM, will begin to market VMOO solutions. They will explain the incompetence of vendor management organizations (which, I have argued, should not exist), link this incompetence to it’s competitor’s performance, and build the case for managing other vendors for companies. In 2010, someone with a moderately complex, underperforming vendor portfolio will will outsource their VMO – leaving a vendor to manage their vendors and clients. The skeptics will call it a lobotomy."
Hmmm… not too sure about this one. While it could make sense, most sourcing executives will prefer to remain in control of a messy multi-sourced relationship than offload to another party and admit they're struggling. Might start to happen more in 2011 when some CFOs wise up to the fact that their sourcing managers aren't doing the job well enough.
Cloud computing is at its hype cycle zenith. However, for non-core processes, it simply makes sense. HRO, FAO, and Procurement are all prime areas for cloud computing. Companies struggling with justifying capital expense related to purchasing and customizing these systems will seek solace in cloud computing models and vendors in this space will begin to provide software as part of their solution.
Financial systems in most companies simply have to extract too much legacy back-end data to make this financially viable - although it's a great concept. Think it may take more time than a year, but it's definitely the future. HR and procurement? For standard apps such as payroll and indirect procurement, most definitely.
Anyway, thanks mystery person for taking the time to share your views, especially when noone knows who you are -:)
If there was a Nobel Prize for industry analysts, this guy walks away with it – he's super cool, talks a good game, and has done very little beyond, well, be super-cool and super-smart… and with a French accent to boot. So today, I thought we'd give IDC's Sebastien Ruest the chance to prove there's a bit more substance behind the snowboarding, hockey-stick-wielding playboy façade 🙂
Sebastien's proving IDC's nearshore model by leading it's global services research from Canada, and developing a solid reputation in the industry as one of the industry analysts who "gets it". So I thought it time to grab a few minutes with the dude himself…
Phil Fersht: Sebastien, firstly, what are the main issues you’re hearing from your clients these days? What are the main contrasts between now and before the economic crash last year?
Sebastien Ruest: Maybe it is the cynic in me but I don't think the economic crisis has affected or changed what the main issues are inside organizations. I think the economic crisis was the equivalent of a worldwide game of musical chair where the music has been on "pause" for 9 months and participants have been in state of suspended animation, waiting for the music to start again. The business logic is no different, but I think this time around the jukebox have fewer songs. I think the contrast this time is that CEO/CFO are less willing to fund long term projects have a immediate and visible impact on the organizations and I think that projects like Mobility or E-Workplaces or Enterprise Wide ERP, have been the most impacted by this attitude.
Phil Fersht: What’s “shiny and new” in the services world now we’re finally coming out of recession, or has a lot of the sexiness been drained from the industry, and it’s all about cost-containment these days? What glimmers of light do you see on the horizon that can get us excited again?
Sebastien Ruest: I have been talking to many companies since January about their IT & Business Priorities and an interesting thing that comes out of this is that: besides cost containment, being the number one priority, the focus of many is the improvement in asset utilization or Portfolio rationalization. And this new philosophy, driven by Business leaders, is impacting both IT & Business Services. Why is optimization so important? Because they are still plenty of older technologies in place inside organizations layered together in spaghetti like fashion and although they are stable, they are not optimized for competing in the emerging business climate. Fix them first, before you suggest upgrading. We could call this new approach "Techno-MacGyver". On the other hand, Business leaders are facing this "Crisis of Complexity " with the proliferation of devices, applications, connections points, etc. Optimization becomes really important for them in order to deal with the emergence of "newish" technologies and business models (such as Cloud Computing or Web 15.0) and the ongoing presence of older, established technologies that are not easily displaced or replaced.
Phil Fersht: I was an analyst until the recent past, and my biggest frustration from many of the service providers, was that several were struggling to say anything different. It was as if a script had been developed on what to offer and how to sell it, and there was no leeway to do anything different… only a few seemed capable of setting themselves apart. Is anything different happening in this post-recessionary market? Do you see the “men being separated from the boys” in the coming months?
Sebastien Ruest: Yes and no. First, there has been this weird dichotomy that Service providers have had to deal with. On the one hand, the economic crisis gave everyone with some buying or sustains power the ability to displace weaker players or the ability to acquire skills and capabilities that were not previously financially available. We have seen it between Dell and Perot, Xerox and ACS, moving up the Services value chain and numerous others within specific regional or industry niches. But will that be the pay off? The dichotomy is that do you spend to gain, or do you cut/save to survive?
I think that in the coming months will be critical for players with limited portfolios, Unless many more projects get funded, players that are not migrating their portfolios away from traditional outsourcing, or from Fixed T&M and toward the componentized delivery models that break down services into smaller, shorter and more manageable contracts, we may see the consolidation of many more players.
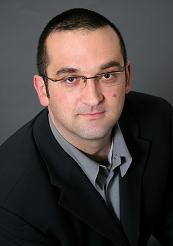
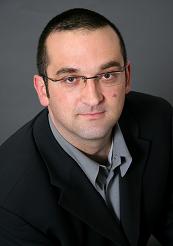
Sebastien Ruest (pictured) is responsible for leading IDC's global research in the Services & Technology marketplace. He also heads IDC's IT service benchmark practice and works with vendors and IT users to measure the efficiencies and cost-effectiveness of service delivery. Prior to joining IDC, Mr. Ruest had close to 10 years experience in corporate strategy, sales & marketing and research at IBM.
Join us for Part II where Sebasten shares his vision for Cloud computing and how it will become integral to the services and outsourcing industry.
Have you ever had such an irresistible request? Well… here's your chance to tour the exquisite delights of the picturesque tree-lined New York suburb, with its manicured lawns, fine eateries and state-of-the-art museums, where you can enjoy the famous hospitality of the jovial, friendly local folk who'll make you feel right at home, shrouded in luxury and fine local culture.
However, sight-seeing in paradise, drenched in lovely winter sunshine, isn't all you can look forward to during this visit of a lifetime… you can also make a sneaky detour to the Global Services Conference, where you can mingle with the hoi-polloi of the services and outsourcing industry, at Jersey City's sumptuous Hyatt Regency hotel on 28-29 January.
And if you enjoyed last years affair, this one promises even more. "Even more?" I hear you ask… yes – even more. Included in this year's line up are Juia Santos, who heads WW outsourcing strategy for J&J, the lovely Linda Tuck Chapman, my boyhood hero Jay Whitehead (yes – he's back!) and some crazy blogger unveiling the survey results from the New Normal in Outsourcing Delivery Survey of more then 1000 key executives in the outsourcing industry.
Anyway, readers of the Horses can enjoy their usual discount by registering at the following link and inputting the discount code "HFSSPL" in the box that says "source code" :
CLICK HERE TO REGISTER FOR THE 2010 GLOBAL SERVICES CONFERENCE
I look forward to meeting many of you here in January 28th…
Most people I speak to can't wait for 2009 to be put to bed. People suddenly awoke to the realization that everything they have grafted so hard to achieve in their lives could be seized from them, because their economy had failed them.
Like everything else in this world, we always wait until its too late before taking drastic action, and 2009 epitomized this reactionary mindset that dominates so much of our society.
However, I did want to sign off from 2009 with a dose of realism… fancy phrases such as "New Normal", or "Preparing for the Recovery" only wash when they attempt to address the question: "How the blimming heck can we radically change our attitudes and actions to save our children from economic and environmental disaster".
But what really gets my goat is that we keep on making the same mistakes over, and over, and over again. One can only hope that the lessons of this year will have broader ramifications than simply learning how to bail out banks and save our stock market from total collapse. Somehow I doubt it; 2009 was just the beginning of the realization that our short-term mentality has to change, but we will – alas – likely need to endure another bout of pain and hardship before we'll eventually do something about it. We got off too easy this time and somehow managed to paper over some pretty cavernous cracks.
For example, the same "boom/bust" cycle seems to be kicking back in. Wall St. realized it was too important to fail, and the taxpayer footed the bill. Now it's starting all over again… the stock market is rising despite uncertain economic conditions and continual rising unemployment. The environment continues to be destroyed and our governments can only (again) paper over the cracks. We've never seen a global response to saving our wealth like this, so why can't we do something to save our world for our children? It seems that as soon as we stabilize our stock market and our house valuations, all is well in the world again.
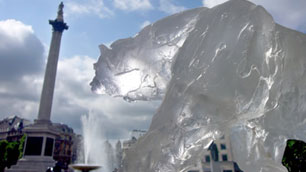
Many of you will recall the emotional rhetoric from earlier in the year when there were calls for fundamental change. There was a sudden realization that this time it was too late… the cracks were too wide to cover… they were becoming as wide as the growing distances polar bears need to swim to find food. Like the polar bear, many of us thought that this time we would start drowning without sight of dry land.
However, our children's' tax burden has saved the day - they have paid for the excesses of today, while we can go on doing things as we were before. All this talk of a New Economy. All sounds good, but without a real change in attitude and a focus on curing long-term ills, we won't really change. We just keep papering over the cracks.
However, some good did come out of all this. For the first time, world leaders came together and acted quickly to salvage a potential disaster. They now know our collective fates, both economically and environmentally, are intertwined. And they should now have worked out better ways to get things done in the future.
While it's likely going to entail more pain, at least we've made some progress at dealing with global issues. Our businesses are now global, our economies international, so now at least our problems are global too… let's cling to the hope that 2009 marked a turning-point in how we stop papering over cracks and start rebuilding a more robust infrastructure where cracks won't keep appearing and getting wider and wider…
The picture above represents an ice sculpture from the Ice Bear Project - a polar bear sculpted out of ice, with a bronze skeleton inside. This was created in Kongens Nytorv Square, Copenhagen, Denmark, close to where nearly 20,000 people attended the United Nations Framework Convention on Climate Change (UNFCCC) during December.
Wouldn't it be refreshing if some outsourcing executives decided to try doing a few things differently this year? Here are some suggestions…
Stop using the word "transformation".
Start trying to be different from the rest of the pack, or at least admit it if you're not really any different (but are probably cheaper, or have a sexier brand, or something).
Stop espousing that you will bring "innovation" to a finance function when you're just lumping the invoice processing offshore.
Stop claiming you're recent infrastructure management deal was a "cloud transformation".
In fact, stop using the word "transformation".
And please stop wheeling out your only client of note as an example of "innovation" and "best practice" when:
1) You bought the deal in the first place,
2) We've heard it 20 times before, and
3) The client hates you anyway.
Stop claiming you do something, when you don't.
Stop claiming you can do something, when you can't.
Stop claiming ERP support is a "scarce expertise" that warrants a higher price-tag.
Stop copying your competitors' slideware.
Stop talking too much and actually listen.
Stop adopting other peoples' buzz phrases as your own.
Stop espousing that you will bring "transformation" to an HR function when you're just processing the payroll checks somewhere cheaper and using some limited piece of software that's only marginally better than the rubbish the client is currently using.
Start demonstrating how you actually did something unique with a client to help them be more efficient or generate more revenue.
Stop using the word "transformation".
Start being realistic.
Stop boring the living daylights out of everyone by tweeting all your press releases and thinking people actually will click on them.
And why not stop having meaningless meetings with sourcing advisors, when you're only going to talk about the same tired old deals everyone already knows about, and the client already knows who they're going to select in any case…
Hmmm… come to think of it, if everyone stuck to those, we probably wouldn't have an outsourcing industry anymore. So please ignore and carry on regardless…
So the "great analyst roll-up" is in full swing, with Gartner's announcement today to acquire another competitor, this time the Burton Group, for 56 big ones. This comes hot on the heels of my former firm, AMR Research, also being acquired by Gartner. I won't go into the details of the mechanics of these mergers, as you can read exhaustive commentary, debate and analysis over at Carter Lusher's blog. However, I did want to discuss what this means to our sourcing industry.
Limited choice for alternative opinions. As most of Gartner's competitors couldn't really compete on brand, they've had to differentiate themselves to survive, and that meant finding areas of coverage that Gartner didn't do (or do well), and having analysts on staff who weren't afraid to rock the apple-cart with edgy, sometimes controversial, opinion and research. While Big G has picked up some superlative minds from its latest acquisitions, its new challenge is going to be maintaining those edgy opinions, and not having them toned down under the glossy corporate veneer of the billion-dollar brand. Whichever way you look at this scenario, we simply have to have more than two analyst voices dominating the opinion and insight of our $850 billion sourcing industry. Why?
Why we need more than two "big" analyst brands. You have to hand it to the Big G. It has dominated the industry for the past two decades, has a great brand, and its "Magic Quadrant" is the envy of all Gartner's competitors. Even if you don't agree with all the placement and positioning, buyers make decisions off that thing, consultants use it to justify their recommendations, and vendors spend a fortune attempting to "influence" their analysts (or at least they like to think they do…). I, personally, have developed much of my career as a competitor of Gartner, working for smaller analyst houses such as IDC and AMR. Most of my clients were also clients of Gartner, and I found they liked to have that extra opinion / validation, and were usually happy to pay for it. They didn't want all their eggs in one basket. I found the analyst industry worked well with several smaller analyst firms operating in competitive harmony with the Big G.
Now, with many of these firms are continually being absorbed under the one common brand, many of these customers are going to look further afield for alternative opinion. They're buying and selling professional services to bring major change to their IT provision and business operations. Sourcing decisions are among the hardest companies will ever have to make, with careers on the line and competitive survival at stake. Having the right validation, advice and opinion has to come from more than one entity.
The new void is created, now who's going to fill it? While Gartner's getting bigger and broader with even greather depth and coverage, the industry needs alternative voices to challenge the industry, to voice public opinion, to "out" poor practices and highlight best practices, warn unsuspecting customers, provide alternative vendor ratings and offer that extra layer of opinion. Forrester's been their natural "big" competitor for sometime now, but the new void is where the edgy little upstarts used to be.
Several of the sourcing advisors have been lending their own weight to generating opinions and some research (for example, Alsbridge, Equaterra, Everest and TPI). They've all, to varying extents, found their voice in the sourcing ecosystem, with some unafraid to challenge the status quo, others preferring more staid, traditional research. There are also other traditional research boutiques that have been around for a while, such as NelsonHall and Ovum (Datamonitor), which also have a unique opportunity to extend themselves into this void. And there are some new-age analyst boutiques embracing blogs and social media, such as Altimeter Group, which could venture into the sourcing sphere to add their tuppence…
One thing's for sure, 2010 will be a pivotal year to see which of these firms will seize the moment and step into the void. We'll just have to see who's going to up the ante…
And now time for the long-awaited second part of our interview with our francophonic snowboarding services stud Sebastien Ruest, IDC's Veep for Global services research. (Vous pouvez accéder à la première partie ici). And ladies, please no more emails asking me whether he's single…
Phil Fersht: Sebastien, let’s talk about Cloud, where you’ve been particularly involved. In a nutshell, can you help us separate the hype from reality, and explain to our readers whether this is just the next buzz-phrase in the IT business, or a genuine way we’re going to access services in the future? Do we have any optimistic IDC projections with cloud-based services?
Sebastien Ruest: In the last few months, I have had the chance to speak with many CIOs and one thing I learned is that the idea of Cloud, this new model of IT and broadly speaking of Business and Consumer delivery through the cloud is of very high interest, to business execs, CIOs in the market right now. But, as you can imagine, Cloud Computing means different things to different people. The cynics will say that it is nothing more than "ASPs on Steroids".
It is very clear that we are approaching a time where we need to not just stay at a high level but we have to get ground level thinking about the cloud and answer some pretty important questions, some very concrete questions: What are they? Why are they important? How Are Enterprises Going to Benefit from the Cloud? And, How much money is going to be spent on this delivery model in the near term and midterm? I don't want to spend too much time on definitional debate but to me this is the simplest, non-techie way to look at them: Cloud Services are really about Consumer and Business services, products and solutions delivered and consumed in real-time over the Internet. The fundamental concept of a cloud services offering is that 1) the services are shared Services (little customization), 2) they are virtualized, at least the management of it, can be scaled up, scaled down and and you can charge per usage, pay as you go.
There are plenty of examples of Cloud Computing already out there: Of course, the easiest, we are seeing in applications, CRM On Demand, Cloud Application Deployment platforms and we are seeing Infrastructure; Server Capacity, in real time, on demand and, the ability to manage IT Assets in the cloud.
But for the time being, the growth is modest. Why is the growth so modest? In my opinion, there are many factors that drive the diffusion of technology into a marketplace and, for whatever reason; there are three that are preventing the adoption of Cloud Computing: 1) Companies are still "Technophobes", They have a high legacy investment in traditional Licence & maintenance 2) There are not been any different market distribution and 3) there has been a lower Sales & Marketing Focus from Cloud Computing Companies. For some strange reason, other than SalesForce.com, no one wants to be "First to Market" with the Cloud Computing phenomenon ?
Phil Fersht: And how do you see Cloud computing impacting the outsourcing industry? Will it drive more cross-specialization mergers between software and services providers?
Sebastien Ruest: I think Cloud computing will force the Services models to change. If you remember the first generation outsourcing deals, were “relationship models where rather than working with a number of specialist firms, you had this "One Stop Shop", “the single point of contact” and the arguments was that although you were not necessarily getting the best solution in every area, there was a more integrated solutions and less finger pointing between the specialist firms. My belief is that ultimately, we are moving to this “Techno-MacGyver model; Where using perhaps Cloud computing, cusotmers will be setting up Services platforms that make it easy for them to access the myriad of services they want from and pay for them in a Utility like model or pay as you go?
As we have seen in the last 12 months, the need for growth will reshape the Services industry into several trends: One is the emergence of a new services model, based on the integration of software and services, and the breaking –up of formerly monolithic business processes into components that can be delivered over the Web. This is what IDC calls "Smartsourcing" which is simply the evolution of services delivery from the Tactical Outsourcing world of Mega Deals that used the static procurement model where the Service Provider played the role of Infrastructure Aggregator. The Service model was static because Assets and People were transferred and contracts were customized for each engagement. At the end of the spectrum Services Delivery model is moving to the world of Smartsourcing where customers seek mega-flexibility through a Dynamic "long tail" model of services delivery where customers look to optimize their assets or rationalize their portfolio without transferring assets or people and by trying to minimize the customization that traditional outsourcing typically require. Service provider will be forced to play the role of Aggregators of Services by connecting different delivery agents. (SaaS or Managed Services as two examples of alternative models that will be impacting the way people "source" services). They are models of Smartsourcing that are occurring, but that can be a topic of a next discussion. ;P
Phil Fersht: And finally, how do you see the global landscape playing out over the next few years? Will the Chinese continue to outplace the rest of the developing world, or do you see other emerging regions such as Latin America and Russia getting a strong share of sourcing work? Do you see more work coming back to the US?
Sebastien Ruest: Tough Question. Again, there is a dichotomy between 1) the need to control and contain costs, and the appeal of many of these so-called "low cost locals" and 2) the growing protectionism movement in North America and Europe. Companies are looking at the tradeoff between risk and cost and locations like Latin America, which has spent the last decade cleaning up its economy, its trade policies and its educational system, become very appealing as Nearshore alternatives in time of conservatism and protectionism. However, let's not kid ourselves, global sourcing of IT work is not just a passing fad. It is well established and integrated in most deals. And not only IT jobs can be moved offshore. Any knowledge-based function that does not require direct personal interaction is a candidate. Also, not only routine jobs are being relocated.
Although, China may not be at the same level in terms of English language capabilities, there are 227M students, in China alone, with half of them still in primary schools, which will become available in the next 10 years. So this shift will continue to intensify.
Sebastien, thanks for your time today.
Sebastien Ruest (pictured) is responsible for leading IDC's global research in the Services & Technology marketplace. He also heads IDC's IT service benchmark practice and works with vendors and IT users to measure the efficiencies and cost-effectiveness of service delivery. Prior to joining IDC, Mr. Ruest had close to 10 years experience in corporate strategy, sales & marketing and research at IBM.
Right on cue with our discussion earlier this week, the "void" just got bigger as software analyst legend, Bruce Richardson, announced his departure from the analyst community to take on the role of Chief Strategy Officer at software giant Infor.
Known in the industry as "Mr AMR", Bruce has entertained us for years with his famous "First Thing Monday" newsletter and blog. I, personally, have Bruce to thank for bringing me back to the analyst fold with AMR in 2007, and being a guide and mentor to myself and many other analysts during his role as Chief Research Officer.
Like everyone else in the industry, I am hoping – and expecting - Bruce to continue enlightening us all with his weekly musings from the vendor side. And I am sure even SAP and Oracle won't begrudge him what has become industry-standard with our Monday-morning espresso. Who said you can't blog from the dark side?


 Remember our mystery blogger who evangelizes on best practices for vendor management? Well that mysterious individual has challenged me to a predictions dual this morning (gasp), where he /she said "I'd be willing to wager a drink on who gets a higher percentage right. After all, I didn't bet on England in the World Cup, so I'm pretty optimistic :)" We'll see about that sunshine…


 Right on cue with


