Wow – HfS’ Peter Ackerson completes the hat-trick. So without further ado, here is the final installment…
The famous Mary Sue Rogers practically invented HR Outsourcing with IBM, before outsourcing herself to Australia with Talent2
Contrary to Mr. Fersht’s implications that any analyst would desert his/her post before an event is concluded, this analyst was there at 8:00 AM for Mark Hurd’s (Oracle) presentation and remained there until 12:30 for one last discussion. Hopefully my (modest) fee will be doubled for this dedication.
Payroll Gurus speak
For those of you who don’t know me, I am one of those rare individuals who likes payroll as a delivered service. Other than that aberration, I’m a fairly balanced person. So to have the opportunity to talk to senior leaders from ADP and Talent2 was a great event. Well, maybe not great, but at least interesting. This will be a brief recap as I intend to cover payroll as an outsourced service in greater detail at a later time.
ADP
Don Weinstein, SVP- Product Management met with us to give an overview of their model and plans. ADP has broadened their offerings over the last few years through acquisitions as well as organic growth. What they want to be known for is as a provider of Global HCM, with three major offerings: Payroll/Time; HR; and Talent. GlobalView, their SaaS offering based on SAP, will continue to be the growth engine. Of the 80+ countries served by ADP, ~40 are using localized GlobalView. ADP has always been SaaS oriented, even before the term existed. There is more to the story, but that will follow later. One tidbit of interest was the PEO business is growing at a substantial rate. The growth is tied to organizations wanting three deliverables: Healthcare cost arbitrage, risk management, and HR administration/compliance.
Talent2
I must admit I had not heard of Talent2 until recently. However with Mary Sue Rogers, late of Big Blue, as Global Managing Director, it was only a matter of time until Talent2 had more visibility in the US – (you can read a great interview here between she and Bill Kutik last year). Talent2, based in Australia, is a major player in the Asia-Pacific area with a significant number of their clients being US and Western Europe multi-nationals. Their primary offerings include payroll, learning administration, recruiting, and advisory. With service centers across the region, they appear to have significant knowledge of legal requirements and compliance. They serve the entire region with the exception of North Korea. We will be interested in following their progress.
Last comments…on the conference
General feedback was fairly positive…Bill and David did well on this event. We have not seen the final attendee count yet, but assume it will be significant. Next year’s conference will be in Las Vegas. Some of the exhibitors privately expressed concern as Las Vegas has far more distractions that Chicago. Let’s face it, when you’re at McCormick Place in Chicago, you are there for the day unless you want to invest in taxis.
If any of you who attended or exhibited would like to comment, please feel free to contact me.
Peter Ackerson is Research Fellow for HR Outsourcing and Shared Services at HfS.
Welcome back to our interview with KPMG’s Captain Cliff who has proclaimed the Death of Outsourcing in a recent white paper. So without further ado…
Captain Cliff Justice, who happens to be Partner and U.S. Leader, Shared Services and Outsourcing Advisory at KPMG
Phil Fersht (HfS): You’ve spent a good part of your career in the outsourcing business yourself. What inspired you to coin the headline and write a paper entitled the “Death of Outsourcing”?
Cliff Justice (KPMG): Outsourcing has changed dramatically in the last five years. When we saw the megadeal declining, we started asking why. The answer: Companies had become more sophisticated in how they deployed their third-party service provider relationships. When companies were outsourcing everything, they just moved out large parts of their organization, handing them over to third parties to operate. Some of those were successful and achieved the goal, which was pure cost reduction. Labor arbitrage became truly feasible and economical when markets like India became a prime outsourcing destination with the acceptance of offshoring around 2001.
Phil: What changed?
Cliff: Over time, companies realized that the value they can gain from using a service provider extends beyond just labor cost reduction. By offshoring you get a lot more than labor arbitrage. You get good talent and providers with advanced processes that would have been difficult to source domestically under a traditional structure.
Phil: How has the rising cost in emerging markets affected this equation?
Cliff: Today, there is still labor arbitrage. But year-over-year wage inflation of 10-15 percent has started to have a material impact on the business case. There will be a day when we reach an equilibrium. I don’t know if that will be five or 15 years from now. Companies have to start looking at how they get the long-term value out of their service delivery organization. Is labor arbitrage going to be the sustainable answer?
Phil: What are your clients doing?
Cliff: Many of our clients see it as unsustainable. They are now looking at their services more holistically. They look at their suppliers in a different way, too, not just as a means to lift and shift resources but as a means to add value to their businesses. We work with hundreds of leading organizations and we also work closely with service providers.
Phil: So what part of outsourcing is dead?
Cliff: The traditional perception that outsourcing is purely about offshore labor arbitrage, or simply a race to the bottom. The death of outsourcing as I define it is the death of the simple, traditional, lift and shift offshore outsourcing. That is still going on and there is still a part of the outsourcing community where that is their value proposition. But we’re seeing a major shift in how the entire service delivery model is deployed which is much broader and delivers more value
Phil: How are companies using outsourcing providers instead?
Cliff: Companies are using third parties in a more sophisticated way to drive value. Outsourcing is now shifting to a race to improve value through the use ofthird parties. Now labor arbitrage is just a part of that. Enterprises are still interested in reducing cost. But now they are looking for cost reduction through other mechanisms such as technology enablement through the cloud (which they do through a third party). They are also using their own captives and shared services capabilities, then augmenting those capabilities with third parties to improve processes.
Phil: In this brave new outsourcing world, what do the relationships look like?
Cliff: They are beginning to look more and more like true partnerships where both parties share objectives. The service providers win because they are developing depth and breadth in an industry. They are strengthening their long-term relationships and moving up the value chain into business outcome objectives with their clients. They are entering areas of the business that can move stock prices and improve the value of that organization. In the same instance, they are improving their own value.
You can see this by looking at where service providers are moving in their clients’ organizations. Look where their focus is. You can see the satisfaction of the clients themselves. We’re fortunate to see a wide range of these relationships. The way to get true, long-term sustainable value is getting the partnership to align with the business objectives. Labor arbitrage by definition is temporary, so the unsustainable relationships are those that are in the traditional category of “your mess for less.”
Stay tuned for Part III where Cliff shares his views on whether we should drop the “O” Word, among other things…
Cliff Justice (pictured above) is Partner and U.S. Leader, Shared Services and Outsourcing Advisory at KPMG LLP.
Have you been observing the fascinating scramble going on over in India for supremacy in the IT services space? By the time this year is out, it’s highly likely that Cognizant will have leapfrogged both Infosys and Wipro to take the number two spot behind TCS:
So what’s driving this shifting landscape?
Let’s take a look at the key market-makers to understand who is breaking out of the pack…
Cognizant
Cognizant’s revenues are being fuelled by organic growth and its ability to penetrate the middle-market. For new business acquisition, we are even seeing it frequently under-pricing Tier 2 providers. Bottom-line, Cognizant targets the business it wants and sacrifices its margins, when necessary, to win the business. It has always operated this way and continues to do so, despite its rapidly-expanding size. And it currently has the best sales engine of all the India-centric providers… which kinda helps a lot.
Moreover, having its leadership stationed in the US keeps it closer to the clients, when it comes to marketing, selling and pricing services, in addition to structuring and organizing its operations. While there are some super-talented leaders based India-side, being so far away from the clients is clearly hurting Cognizant’s competitors in today’s hyper-competitive market. I can’t tell you how much talent has left Cognizant’s competitors, because they weren’t allowed to take on leadership roles in the US.
That being said, Cognizant’s growth is still (by and large) directly proportional to FTEs, and it still hasn’t quite unbundled this link, which will likely hamper future growth. In needs to “change the wheels of the car while driving” and figure out how to delineate butts-on-seats from client pricing, if it wants to continue this rapid growth story into 2013. Having said that, we do believe Cognizant is figuring out the connections for the business side with IT solutions quicker than its competitors which are still slow to the game.
TCS
Conversely to Cognizant, market leader TCS probably has the least effective sales forces in the big-ticket outsourcing market. However, once you get past the shaky front-end, the firm has one of the strongest service delivery infrastructure of any of these providers – if something blows up, its teams will be all over it, and will leave no stone unturned to bring it back on track. However, if the client doesn’t ask, TCS doesn’t react. Of the five, it is frequently the the most flexible on pricing and terms, and can probably win any deal anywhere in the world at any price, if it really wants: it depends on what its leadership thinks is important, what its perception of the market is, and what it needs to tell its stock-holders. TCS is perceived by many today as an alternative provider to the Western Tier 1s, that can come in and fix messy contracts and implementations ; they will pick up a lot of the low margin, low value work that seemingly every Western Tier 1 wants out of.
Not only that, TCS is having much more success de-linking the direct correlation of revenues from FTEs: the firm has a laser-sharp focus on managed services, fixed price projects and has successfully monetized its product group. The sheer size of its referenceable client base and the executive connections of its leadership, is a huge strength. In addition, its tunnel-vision on developing its platform-based solutions is really helping the firm move gradually away from the FTE-pricing model.
Wipro and Infosys
Wipro and Infosys, on the other hand, seem to have just lost their mojo over the last couple of years, which is directly linked to the changes at their top, and the time needed to development its new leadership talent to take them forward. In addition, many new customers are saying “Why do we need the Cadillac when a regular Chevy will do just fine?”. A lot of client requirements are straightforward and easy-to-service with low-cost resources.
In short, both have struggled to articulate a renewed vision for the future of IT services to encourage clients to choose them over some very, very aggressive competitors. However, we at HfS have noticed marked attempts by both firms to bolster their fortunes with a much more assertive series of communications to market. There is a clear determination to roll out new platform solutions, and a more consultative client approach that can move them up that value pyramid, which comes in so many nice new colors and 3D views, in the new version of PowerPoint. I would also point out that these providers are not doing badly – they are simply being outpaced by the Cognizant and TCS machines, in a commoditizing market that is slowly losing steam.
HCL
HCL is the proverbial odd one out in all of this – it had lost its focus on outsourcing until about 3-5 years when it hired in some new leaders to refocus the company. Its clear strength is in infrastructure services – borne from its past relationship with HP. Today, the firm is growing largely due to the sheer number of unconventional deals it is contracting, in addition to its aggressive pricing which is becoming a popular topic of discussion between sourcing heads. Plus, the firm has a very aggressive sales engine. It kinda reminds me somewhat of Cognizant five years’ ago in terms if its size, thin management layer, and incredibly personal approach to client service – from the CEO and his immediate team.
HCL is another example of an Indian-HQed firm that will pick up on the poor quality provided by WesternTier 1s. However, the firm does need focus, polish and business development leadership to get to the table. Its operations and infrastructure team resonates well with clients, but tends to get way too far in the weeds during initial sales pitches. It needs to avoid trying to solve all the client’s problems within the first 30 seconds of meeting them.
The Final Word: The IT services industry has reached a bifurcation point and not everyone will stay the pace
Ask an analyst to write about what differentiates IT services providers in today’s market and you have to get right into the weeds to come up with the answers. My conclusion is simple: both Cognizant and TCS are outpacing the Indian-centric IT services market. And both are very different firms – Cog very sales and pricing focused, TCS very solution focused. They’ve left Wipro and Infy a little stunned, to be honest, and they are having to go though some major changes internally to try and keep pace. However, the market at the low-end is very commodity driven these days, and there simply isn’t the room for all these providers, let alone the dozen other major providers, HQ-ed outside of India.
Everyone wants to grow exponentially at 20%+ a year without having to make radical changes to their business models. I predict the future is going to be less about selling the low-end work, but the more complex IT-enabled business processes that are specific to industries. Hence, the investments the providers need to make are going to be in more consultative talent and specific technology IP. And you can’t find all of that for cheap rates in a third-tier Indian city… these guys are going to have to look at more inorganic growth in onshore providers, clients and technology firms. The bifurcation point has now been reached, it’s time for these providers to make the necessary investments to continue their growth journey, or they can start look at some rather interesting case studies of providers in the Western world who failed to keep up with the times.
Imagine running a business where you have no accountability for cost control, achieving your stated objectives and are completely paralyzed to change anything.
And when you do try and change something, half the organization refuses to even contemplate change? Welcome to government.inc. The impossible organization.
And, let’s face it, many of today’s clunky, oversized enterprises aren’t a helluva lot better.
When we look ahead ten years, the successful businesses will be a lot smaller, more agile, and much more focused. Processes that bring no competitive advantage are likely to be sourced, and consumers via a “pay per use” model. Boxes of IT hardware will likely be extinct, along with the staff who maintained them. Delivery centers that house hoards of costly staff with the sole focus on maintaining low-value work will likely be long shut-down, or absorbed into service provider organizations.
We know where the world is headed. The unknown factor is the time it will take to get there.
While we are caught up in this election furore – one thing is abundantly clear: whomever gets elected is going to have to contend with the continual paralysis and painful increments of the necessary change needed, to keep the country (and most likely most of the world) somehow functioning.
However, most of today’s enterprises do not have the luxury of paralysis.
Far too many of today’s business are dragging around these clunking, inefficient infrastructures, that often resemble the workings of government, when you get under the covers. Teams of corporate politicians lobby to maintain the status quo, raising issues about security, about political risk, about poor quality services from third parties… about anything that can prevent the one thing the company needs to embrace… CHANGE.
However, these enterprise beasts don’t all have the luxury of the government – one day their shareholders will run out of patience and demand CHANGE (gasp). This is not an eternal spiral of endless-do-nothingness – there will come a point where enterprises will have to embrace change, or simply limp away to the corporate cemetery, where many failed business are fondly remembered – or simply forgotten. We can even reel off lists of enterprises today shedding swathes of staff or lumbering on Chapter 11 life-support, desperate for something to happen to divert their seemingly inexorable descent into corporate oblivion… you know who there are!
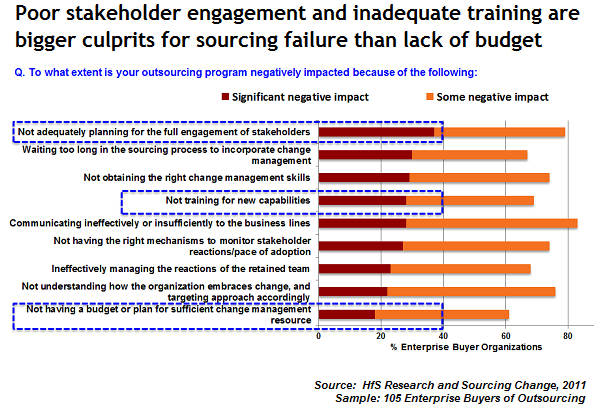
So this drew me back to a critical piece of data we pulled together last year with Sourcing Change, where we asked 105 post-outsourcing enterprise buyers what was (really) preventing them from achieving success with their outsourcing programs:
The “Lack of Budget” excuse doesn’t wash anymore – it’s the “Lack of Executive Will” that’s the real impediment, when it comes to changing the status quo
Simply put, “lack of budget to plan for change” was least negative factor impacting enterprises’ outsourcing programs. However, poor planning to engage all the right statekolders is the most significant impediment – by a considerable margin. And coupled with this is a lack of training, poor communication, and any sort of manageable change process to ensure these outsourcing programs are working effectively.
And this is where I draw my comparisons with Washington – throwing money at a problem is never the issue – the real solution is pulling all the key stakeholders together and getting them to agree on the right way forward for the organization. Here are some tried and trusted steps to follow… if anyone really cares:
Avoid “analysis paralysis” – The financial payback times can be quite long -therefore this can delay making the decision to actually do something
Avoid stagnation – It is also much easier and “safer” to do nothing – a lack of will
Use “real” communication – Overcome the lack of trust in “Corporate” – the only real course is honesty and clarity
Agree to disagree – Consensus is important and any significant change program should encourage constructive criticism, but eventually stakeholders must make a decision and support it. If everyone has to be happy before anything is done, then nothing will get done!
Stay focused on the ultimate goals – Identify who is in which bracket, be honest and clear and support the change, but not be railroaded from the ultimate goal, which will ultimately impact people, by design and necessity
A room packed full of buyers and providers… and very little powerpoint
During the first day (buyers only) we revisited the Four Industry Challenges to take the discussions into the weeds of how to address them.
Day two, the providers rolled in to join the discussion – and they quickly dropped their sales facades to get stuck into some great debate and conversation around what we can do as a group to shift the focus of this industry away from its cost-obsession and towards its need to develop its talent.
On day three, we concluded the discussions by peering into the global operating model of the future, before we went Gangnam Style (stay tuned…).
We can’t wait to synthesize our findings with the group and share the definitive Blueprint roadmap. Watch this space.
NV "Tiger" Tyagarajan is President and CEO, Genpact (click for bio)
If you thought the business services industry was hurtling along at break-neck speed, read our first-ever blog post over 5 years’ ago entitled “Beyond Labor Arbitrage: The New F&A BPO Frontier”. However, while it does sometimes feel like it’s taking an age for this industry to progress, we have to remember that the widespread adoption of global process sourcing, incorporating remote delivery from offshore and nearshore locations, is barely a decade old.
The good news is that the conversation has clearly advanced, and services buyers today are much, much more in tune with their needs and desired outcomes from business services, than they were in the aftermath of the 2008 crash. Anyone attending last week’s HfS 50 Blueprint Sessions in Boston was blown away by the intense level of dialog from 35 leading enterprise buyers, brought together by the common desire to improve their talent and define their careers, move beyond a cost-centric delivery model, and work more effectively with their sourcing partner to foster innovations for themselves.
So…where is the future of business services heading?
Well… now is a great time to reconnect with one of the great pioneers of the global business services model. This chap has been personally involved in many of the largest engagements this industry has seen over the past decade and beyond. Noone has been closer to the buyers over the years to observe the changing conversations, the growing awareness of their needs and apply these to the ever-competitive provider marketplace. Yes, it’s time to touchbase with NV “Tiger” Tyagarajan, now 18 months into his tenure as CEO of Genpact.
Tiger is now settled back into New York – a short train ride from his son’s university in Georgetown, Washington D.C., and also within easy reach of the Wall Street analysts, eager to fathom how his upstart firm continues to outpace the leading providers in the business services industry, with consistent annual growth at the 20% level and shortly going to surpass the $2 billion revenue mark…
Phil Fersht (CEO, HfS Research): Good morning Tiger. It’s been well over a year in the hot seat. What’s it been like? And did you always want to be a CEO?
NV “Tiger” Tyagarajan (CEO, Genpact): Phil, it doesn’t seem like more than a year has already passed! It seems like just yesterday that I took over. But other times it feels like I have been here forever. After all, this is my 15th year in the company; 19 years with GE. I have now gone through seven quarters announcing results. The world has continued to evolve and change throughout this time. These have been interesting times.
Phil: You’ve had a really colorful career. Where did you start out in life and how did you end up leading this $2 billion company?
Tiger: I started 27 years back in sales at Unilever selling soaps, detergents and cosmetics in India after I got my MBA. It was all about execution, daily action and real-time monitoring sales and salespeople. I learned a lot from that results-and-action-oriented company.
Then I worked for Citibank for three years on the consumer lending side. I had six jobs in three years. The consumer banking industry in India was going through turbulence and change. Delinquencies and losses happened in a short span.
I was one of the first employees of GE Capital to set up the consumer financing business. As part of the regular leadership rotation, I joined GE Capital and Financial Services, which had 300 people. It was a fascinating run. By 2002 we had 14,000 people in 3.5 years.
I wanted to commercialize the business but GE said no because they wanted us to focus on serving GE’s businesses. So I came to the US to work for GE Commercial Lending as a global leader.
Then, three years later, when GE spun off the division, I came back. I have always loved this business and the people. I believed this would change how companies would run in the future. I came back as the head of sales and marketing; I had to set up the function. Then, three and half years later, I became the COO; it was a grooming ground.
Sometimes my career was a natural progression and sometimes it just happened. I wanted to take over the job when Pramod Bhasin retired, but things like that are never given in a public company.
Phil: What kind of skills did you have to develop as a CEO that you didn’t expect when you took on the role?
Tiger: I was involved in every strategic decision and direction that we took. I had the advantage of being in marketing and sales. So I had the market feedback and direction; I knew what clients and customers were saying. I knew operations inside out because I had run that segment of the business earlier. And I knew all the people even though I was in the US.
Pramod (read earlier post) and I ran the business as a partnership even though he was the boss. In many areas I ran it on my own and he didn’t interfere. To some extent I had the luxury of the last seven years where I wasn’t the CEO but it was just a shade different. I have been doing the job in any case. That made it easy for me to step into the job. So what’s different?
What’s different is clearly I can’t delegate the decision-making to someone else. That hits you when you are at crunch time and have to make a decision. Should you go right or left? You are looking at an acquisition and everyone has put everything on the table and you turn to the team and they say what they think. But you have to decide.
Given the fact we are now so global with global operations, clients and investors, it makes it tough to manage your time. How can you be in all places at all times? How do you use technology to connect? Particularly in our business where holding one culture and being felt and seen the same by our clients is so important. This is important since culture is a big differentiator to us.
How do I deal with the Street? It takes time to do a deal. It takes time to get revenue. But the Street unfortunately functions quarter by quarter. So, how do you manage the long and short term?
Phil: When we look back to the 2008 crash, what does it look like from a provider perspective? Do you feel clients’ needs have changed radically in the last four years?
Tiger: Yes. I see three changes. First, there has been a natural evolution as more and more clients see examples of where outsourcing works. Therefore they have a higher degree of comfort that it can be done. Now the conversation is less about “Can you do this?” especially in traditional areas and more about “How are you going to do this? What do I have to do?”
The other thing [second] that has changed: a lot of clients understand this is not just about labor arbitrage or efficiency. It’s also about effectiveness; how do you drive better outcomes? Clients are more educated. We have been educational in this journey.
The third thing is the recession. It has changed the lens people use. Earlier, it was “Let’s do the whole thing in a three-year journey.” Now it is: “Yes, I want to undertake that journey. I am going to evaluate you on whether you can handle that whole journey. But I am going to break it up into three parts because I want an immediate payback.” That’s the tough part.
Today, large corporations are dividing up the work to get a faster payback. They want a bigger bang for the buck.
A lot more companies that have never outsourced before are jumping in, especially in Europe where people have been pushed to the wall. Companies that wouldn’t have thought about outsourcing in the normal course of affairs are thinking about it now and want to do it.
There is a range of changes in client expectations and how suppliers are providing solutions. Clients are now cleverer. Many more people know how it works. This is still a small group. Sometimes they undertake this key journey with outsourcing advisors. That can be good or bad. It’s bad when it takes a long time.
Our focus is: How do we get maximum value and outcomes for our client using end-to-end and smart enterprise processes? It has made a huge difference about how we think about what we do. It’s made an even bigger difference in how clients think about their journey. It’s taken on a different transformational agenda.
Phil: We have been through so many secular changes. When we look out to 2020, what do you think the world will look like? What will our industry look like?
Tiger: The fundamental belief we have—which is why the industry is so exciting—is this a long term, secular direction where most global corporations are going. They are asking: What are the core competencies and intellectual capital I need to hold on to? What are the things I don’t need to do?
This is no different than the transformation that manufacturing did 20 years back. Now most manufacturers don’t make all things that go in an automobile or an iPhone. Today Apple does the intellectual capital of the what, the how and the design. They also do sales and marketing. But not much else.
I think services are going in the same direction. But it will be a long journey. Today we do complex work for some clients, but some clients are not there. We think the world will get to a situation where services are bought and sold between corporations where each has a core competency around a set of services that it sells. Those corporations are focused on their own intellectual capital.
A focus on outcomes and business income will soon gather momentum. It will be how expectations are set. It will take time to really be the way that services are sold and delivered.
This is a very segmented industry today. But there will be some bigger winners. But it won’t happen in a hurry. There is such a wide range of services, industries and geographies. Consolidation isn’t going to happen in a hurry. It’s just too nascent. But it will happen at some point. The strong will become stronger.
This will change the way companies compete. There are companies we deal with in emerging markets. They have an invention that they want to start selling. They want to focus on that product and keep improving it. They want to buy everything else from someone else. They buy best of class from day one. They go to the cloud because they don’t have any legacy IT. They have incredible speed because they are not hampered by finance, HR, IT or procurement. They become a highly virtual organization.
This gives these new incumbents in certain industries structural advantages older companies don’t have. New incumbents in emerging markets and new incumbents in established markets with new technologies will aggressively take out the older companies in a far faster cycle.
Data. The ability to capture it, keep it and use it will get better and better. Then the question is: How do you get insights from it? How do you help corporations make better decisions? Some companies are going to get much smarter at making decisions using these insights.
Some companies will use all these as levers to become far more successful than others. This will benefit them hugely. For us, it’s important to position ourselves in some of these services and be part of the solution and be part of the innovation in the space. We need to be the reason to drive this change. This will also change the way companies run.
Stay tuned for Part II, where we delve deeper into the pace of change in today’s sourcing industry…
NV “Tiger” Tyagarajan (pictured) is Chief Executive Officer for Genpact. You can view his full bio by clicking here
When better than Halloween, than for HfS Research to – yet again – spook the analyst industry by winning the new “Innovative Analyst Firm of the Year Award for 2012” by the International Institute of Analyst Relations, ahead of the likes of Gartner, Forrester and IDC.
And not only that, we finished third among independent analyst firms as Analyst Firm of the Year. I managed to get our hands on the top 10 list so share with you all – and a big shout out to my good friend Zeus Kerravala, whose firm ZK Research, a specialist in communications technologies, topped the 2012 charts. HfS managed to beat out all the other sourcing and services research firms – most of whom were hawking their wares a decade before HfS even existed:
Outsourcing has always been about people, process and technology. Scratch that. It’s about process and technology, with people an optional extra. So without any further explanation of this amazing trend where people will no longer be needed, let’s dig into to this new phenomenon: Robotic Automation.
“Listen and understand. Robots are out there. They can’t be bargained with. They can’t be reasoned with. They don’t feel pity, or remorse, or fear. And they absolutely will not stop, ever, until you have knocked another 50% off your outsourced labor costs.” (With apologies to James Cameron.)
Stop me if you’ve heard this one before:
“Chief, I need to add ten FTEs to handle the additional order-entry and logistics workload we anticipate once our new product launches in six months.”
“Oy. You know we don’t have the budget for that. What about automating the process?”
“IT quoted it at 18 months and $1M to do under their standard SOA and BPM development approach. Even if we had the money, that wouldn’t come close to meeting our launch deadline.”
“So what are our sourcing options?”
“We can hire 10 FTEs for $800K in the States, or $300K India.”
“Right, India it is.”
“Actually, I have one other option. We can do it for $120K in Robotistan”
“Robotistan? Where the hell is that?”
“It’s right here. I’m going to have my own business process analysts create software robots to do the work. We can get the robots up and running in five months. The robots will do the work for less than half the cost of Indian FTEs. And nobody’s job gets shipped offshore.”
Oh, you hadn’t heard that one? Neither had HfS until recently, when we started researching a UK startup by the name of Blue Prism. It makes a software development toolkit and methodology that lets non-engineers quickly create software robots to automate rules-driven business processes.
Think about this for a moment. If you were a buyer, how fast would you jump at the option to hire FTEs at rates that undercut the Indian body shops by 50% — without sending jobs offshore? (“Hire” isn’t the right word, of course: it’s “create”.) If you were a BPO services provider, how would you like to build a software robot to automate a business process for one client, and then resell copies of that robot to a dozen other clients in the same vertical? If you were an Indian outsourcer, how great would it be to hand off your dullest, most rote outsourcing work to robots so your human workers could take on more engaging tasks, thereby reducing your horrific churn rate – and by the way, undercutting your competitors on price?
Naturally, there are caveats. Not every business process is going to be well-suited to robotic automation: the more rules-driven it is, the better. Think of any rote, repetitive back-office process that does not require human judgment or much exception handling: swivel-chair data entry into multiple systems, account review and maintenance, creation of online access credentials (user IDs and passwords), general ledger account maintenance.
Furthermore, you’re going to need some buy-in from IT, and they may find the project a little fishy: what are business process analysts doing developing software? You may have to build a modest pilot first to convince them it works, as you’ll need their help with necessities like putting together a virtual machine cluster to run the robots on. (Getting your executives on board should be considerably easier once you show them the eye-popping business case in which not only does nobody’s job get shipped to India, but you may save enough to protect some onshore jobs or reshore some higher-value work.)
There is a learning curve on the environment, typically two to four months to master the tools to model, automate, test and optimize your new robots. But after the initial ramp-up, development time drops dramatically for each new business process, in part because new robots may be able to reuse components created for earlier ones.
Naturally, HfS didn’t take Blue Prism’s word for it: we studied two of its early adopters, a large wireless carrier and a major BPO services provider. Having successfully built very cheap robots to automate a variety of business processes, these people are true believers, avidly looking for new processes to automate. We outline their experiences in the report “Robotic Automation Emerges as a Threat to Traditional Low-Cost Outsourcing”.
In it, we take a long look at the business cases that led these well-known companies to explore the technology, the obstacles they faced selling it to internal stakeholders, how they identified suitable processes for robots to do, what learning the Blue Prism tools and methodology was like for their business-unit staffers, and how the resulting robots now fit into their existing IT and security infrastructure and governance.
We also make some predictions about how this technology has the potential to dramatically shake up the outsourcing industry, especially those players whose value proposition largely rests on labor arbitrage. The workers of Robotistan have arrived, and they have the potential to thump their human counterparts at their own game. HfS urges BPO buyers, services providers and advisors alike to look at the jaw-dropping economics of robotic automation, and put together a strategy to accommodate and exploit it today.
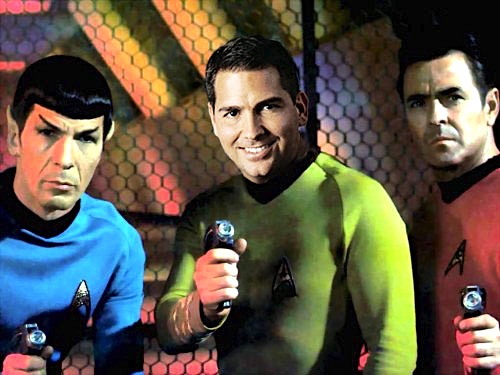
Captain Cliff Justice in action as Partner and U.S. Leader, Shared Services and Outsourcing Advisory at KPMG (pictured center)
Welcome back to the Captain Cliff chronicles. And since Part II, we have actually witnessed Cliff speak for a whole hour at an outsourcing conference and manage not to mention the “O” word once. That’s quite a feat, so let’s find out why…
Phil Fersht (HfS): Cliff, we’ve had a lot of debate, and even conducted a survey, on whether the term “outsourcing” should be forcibly removed from business vernacular, because it doesn’t make sense anymore. Is that something you would support? Do you think it conveys the right message about the industry?
Cliff Justice (KPMG): Outsourcing is a term that has been abused and politicized. It doesn’t have the same meaning to the general population as it does to those who are close to it. So I would certainly propose the industry find a different term for the use of third parties to create partnerships to provide services.
Phil: Would it be possible to take it away? We talk about the political damage it causes but you and I have been in situations with clients where people view any type of activity which involves global resources as outsourcing. Is it going to be possible even if we make a considerable effort to get away from the political ramifications of the globalization of business?
Cliff: I think over time it will. Globalization is a reality that will add and grow in popularity. The fact is globalization isn’t going away. Companies are starting to look at their third-party partnerships as a way to improve their businesses, their images and the value to their companies and shareholders. A term is not going to make or break that trend. You have the best-respected companies in the world deploying outsourcing agreements and they are not engaged in the political wrestling that goes on.
A lot of the politicization is how a company handles the outsourcing image. You can change any politicized term to something that seems innocuous today and then that term can be politicized tomorrow.
Phil: We’ve been getting a lot of questions from our clients around their global distribution of operations. Some particularly large organizations are starting to question whether they have too many resources based out in locations such as India and the Philippines. Is that consistent with what you are hearing from companies in general or is this just a general feeling that has been going on for awhile?
Cliff: I think that’s true, especially in the manufacturing sector.
Actually, it is not location specific; it’s more about control. Some of that has to do with proximity to leadership and where the company’s innovation cluster is. In the manufacturing sector we are talking to CIOs who are focused on bringing their innovation capabilities closer to the vest. Today, if their innovation capabilities reside with third parties in remote locations, those CIOs are starting to say they need them closer to the cluster they’ve established. If that cluster is in the US, then that means bringing some of that back to the US.
As the business needs change, these portfolios are going to change. Companies that are becoming more mature in this extended enterprise model have the ability to manage these services like a portfolio; when their needs change, they shift a little bit on the portfolio.
I don’t see a radical trend to bring everything back in house or onshore. It’s going to be like adjusting your financial portfolio as your business needs change. A lot of third party service providers are able to give companies capacity they would never have otherwise. So the CIOs and CEOs are looking at their overall portfolio of capabilities and sourcing those capabilities appropriately whether it is internal or external.
Stay Tuned for Part IV, The Final Frontier…. coming soon
Cliff Justice (pictured above) is Partner and U.S. Leader, Shared Services and Outsourcing Advisory at KPMG LLP.
During Part I of our interview with Genpact’s CEO NV “Tiger” Tyagarajan, we compared the metamorphosis being experienced today’s by today’s business services industry with that of manufacuring 20 years ago:
Now most manufacturers don’t make all things that go in an automobile or an iPhone. Today, Apple does the intellectual capital of the what, the how and the design. They also do sales and marketing. But not much else. I think services are going in the same direction.
NV “Tiger” Tyagarajan, President and CEO of Genpact, October 2012
In Part II, we discuss the bifurcation occurring between the sourcing approaches of small and mid-sized organizations and today’s large enterprises… and the pace of change we can expect in today’s environment. So without further ado, let’s go back to Tiger’s Tales…
NV “Tiger” Tyagarajan is President and CEO, Genpact (click for bio)
Phil Fersht (CEO, HfS Research): Tiger, do you see bifurcation happening in the sourcing industry? We have a lot of small-to-medium-sized businesses quickly evolving, where IT is in the cloud; everything is outsourced unless they actually want to keep it in house, and many are morphing into increasingly virtual environments Then there are the larger enterprises which are moving at a snail’s pace – they don’t want to change, they seem to becoming more risk-averse, if anything. When we look ten years out, we’ll clearly have have a lot of smaller, more nimble companies, but will the enterprises really have changed all that much? How does a business services company like Genpact evolve in this type of environment?
NV “Tiger” Tyagarajan (CEO, Genpact): Phil – it’s a great question. Smaller companies are able to attack larger companies because they are structured differently. We have worked with a large UK healthcare provider for seven years. Two years back they decided to come to India and set up an insurance business. They formed a JV and set up the business.
The insurance market in India was new, young and growing with very large competitors with client bases of 20-30 million people each. This company decided they wanted to grow at rocket speed. And they needed a cost advantage that is incredibly crazy.
Insurance companies take time to break even because there are a lot of upfront costs that you recover much later. They decided they wanted a variable cost from day one. They just wanted to own their sales force, their product, their consumer, their policy and their intellectual capital. That’s it.
We set up their operation from scratch. We started with two people. They did everything on the cloud. Today, we have 200 people serving them. They have a CEO and a CFO, product designers, marketing people and a sales force. That’s it.
The result: They are the fastest growing insurance company in India for the last two year by factor of two to three X. They have a cost structure radically different from everyone else. We think this is an incredibly crazy model. What is fascinating is their competitors, even in a developing market like India, have 15,000 people with a legacy system with 15 million accounts.
How can the big companies compete with these guys? I think they have a chance because they are growing 25 percent. But what about a US insurance company growing at 1.5 percent? They will have to evolve. It will be a combination of data, technology and process. Companies like us have to be the solution providers to make these companies successful.
There will still be Wells Fargo, Procter & Gamble, Unilever. We will have to pick and choose who we want to work with. Who will change? Who will move fast? Who is the most innovative? Who will take the tough action?
Phil: Do you think companies will decide overnight they’ve had enough of clunky infrastructure and operations, enough of these tired old ways of doing things; that it’s time to change. Or, do you think this is a gradual, generational shift into the new way of doing business?
Tiger: It will vary company by company, which is fascinating because it shouldn’t. It won’t even be industry by industry. In each industry we see some companies move much faster. They create a burning platform to drive change. Sometimes it’s because a new leadership team comes in and rocks the boat. Or because they get pushed to the wall. It’s completely dependent upon leadership and the leadership’s ability to drive change. It’s about the confidence they have, the risk they want to take and what they have at stake.
But it is also industry dependent. Some industries are going to get pushed far harder to change faster. Look at the pharma companies. For so long they have done nothing. And why would they? They have had 85 percent gross margins in the last three years. But even now that’s not enough. Some of them still live in a fool’s world. Their profits are rapidly declining; last year it was 70 percent. But that’s not three percent!
Our view is it’s important to understand industry dynamics and the company’s cultural dynamics. It’s important to latch on to those companies that can move rapidly.
As we look across the IT landscape, especially the mature IT landscape, some are doing so well and some aren’t. I think part of the reason is their clients. I would argue some companies have chosen to play in industry verticals and client organizations that by definition drive change faster and harder, which enables them to grow. Other companies, unfortunately, have industries and clients that are not like that. They are stuck with them. When you go through turbulent times, they don’t grow.
We are big believers in selecting your clients properly. You can help clients change when they are able to drive change hard. We watch when companies undergo leadership changes. Because often it’s the leader. They come in with a fresh view. They have no legacy. They have no fear. Often they have a mandate to change. No one will really question them.
Stay tuned for Part III, where we’ll talk about how well providers understand their clients’ businesses…
NV “Tiger” Tyagarajan (pictured) is Chief Executive Officer for Genpact. You can view his full bio by clicking here




 Imagine running a business where you have no accountability for cost control, achieving your stated objectives and are completely paralyzed to change anything.