One of the most prominent industry analysts in sourcing over the last decade-plus has been Stephanie Moore. Steph started out at Gartner, before spending time at Giga, and most recently Forrester Research, where she built an industry-wide reputation as an outspoken and respected figurehead of the IT services and outsourcing world.
Earlier this year, Steph made her first venture over to the service provider side, and when she's not busy entertaining her three kids, sailing around the Westport beaches, or regaling stories of her junior golf open triumph (she swears they had color-TV back then…), Steph assumes the role of Chief Marketing Officer for IT services firm, UST Global. I thought I'd take this oppountunity to grab a few words with Steph to share some of her views on where the industry is headed, and how she's finding life on the vendor-side of the fence…
PF: Stephanie, how has the world of offshoring changed over the last decade?
SM: Phil, it has changed dramatically. In 1999, people were using offshore outsourcing to save money, but also to execute on very low-value tasks. There were also a lot of people scrambling to fix the Y2K problem. Today, it couldn’t
be more different. People are using offshore outsourcing for absolutely everything. It isn't even thought of as offshore outsourcing any more, it's simply global sourcing. Whereas ten years ago talking to a CIO about outsourcing was a little bit "bleeding edge" and a bit politically incorrect, today it is an imperative. Every Fortune 500 CIO understands the benefits and risks, and whether or not it makes sense for them.
The other major difference in the last decade is the customers, who have become unbelievably sophisticated. The sourcing and vendor management executive—a role that did not exist ten years ago—has emerged as an extremely important person within most Global 500 IT organizations. Those folks understand how to manage vendors. They understand how to write contracts, and they understand what structure needs to be put in place within their companies to make outsourcing work. So not only has the perception of offshore outsourcing changed, but both the vendors delivering services and the customers buying services have matured very dramatically.
PF: Would you say the day of the offshore captive is now over, or can you see this revitalizing in this post-recessionary market?
SM: I would say that the day of the offshore captive is over. As companies mature in terms of their outlook and understanding of outsourcing, they understand the benefits. One of the benefits is flexibility — flexible capacity and access to the very highly skilled technical resources that they may not have access to internally or may not need to staff internally. With a captive you don't get either of those. You also don't get predictability in terms of cost. A company with a captive in India for the past four-to-five years has seen their cost base rise and fall. Also, costs associated with training, recruiting, and marketing are really huge. Mature companies realize that it is much less valuable to invest in a captive, not only because of the hard dollars but because of the [lack of] ultimate value they are going to get from that captive. So as companies turn more towards outsourcing everything that is not core to their business and focus only on their core activities, the captive will become less and less attractive.
PF: How are your customers at UST Global approaching ITO today? Do you see any marked differences since the days before the economic downturn?
SM: If by ITO you mean IT outsourcing, then customers are continuing to be more selective in terms of the providers they use. They are unwilling to outsource everything to a single provider. They have sophisticated sourcing executives. They have more sophisticated internal business customers who understand that if they rely on one provider to support all of their applications and infrastructure, their leverage, negotiating power and service levels are more limited. The economic downturn has forced sourcing executives to be even more vigilant in terms of selecting the right providers for the right kinds of services and getting the right deal.
If by ITO you mean outsourcing in general, then obviously interest in outsourcing has picked up again, fairly dramatically, and I think where you see the real interest is the folks who have never done outsourcing before. When you look at financial services and insurance companies, for example, their consumption of outsourcing has slowed little bit as they begin to rationalize their spend and rationalize their internal IT costs. But folks who have never done any outsourcing before are realizing that this is a great way to save money, and they are more interested now than ever. So the short answer, Phil, is that the economic downturn has really spurred interest in outsourcing. That is the trend in general when the economy tanks.
PF: How can ITO providers differentiate themselves in today’s market? Is it by vertical focus, or other elements?
SM: That's a great question, Phil. Especially before customers get to know their service provider, the provider's vertical capability is absolutely the critical differentiator. That is what gives the provider the ability to convince the customer that they understand their industry, therefore they understand their systems, their needs, their requirements, and their specifications. I think that in some specific cases a service provider’s horizontal capability is important but just with customers with very leading-edge technology requirements, since most large ITO providers have a full complement of horizontal capabilities. But I think that once customers know their service providers, either through a very long RFP process or because they have worked with multiple providers for a long time, the largest differentiator is the vendor's ability to provide customer service, customer intimacy, and their ability to help the customer be successful. Without mentioning any names, the vendors who are the most popular and who have succeeded are those who can not only provide vertical domain expertise and horizontal technology expertise, but they have been able to embed themselves in the client environment and help their clients become successful; not only with outsourcing, but with their business strategies and business goals. Ultimately, that becomes the major differentiator.
PF : How about BPO – how do you see this market developing, and are you seeing the worlds of BPO/ITO coming closer together? Can you see more of the IT-centric service providers such as UST Global developing more BPO-centric services?
SM: That's another really good question. I think that as we get into the next decade, companies are realizing that technology is not as differentiating as we once thought it was. With the advances in bandwidth, we are going to see the cloud come into play much, much more. I think that if you talk to the analysts at Forrester or Gartner, they'll talk about the cloud and how everything is going to be in the cloud. Ultimately that is probably true, but I think that in the next five years or so, customers are going to get there through what looks a little bit more like PBO than like software-as-a-service. If you look at UST, for example, we have lots of customers for whom we do technology work: we support their applications, we support their infrastructure. We haven't really focused on BPO. Our small BPO division is specifically within financial services in the mortgage processing area. We have gotten into BPO in a rather large way, however, through our relationships with clients because they have said, "Look, you are supporting our applications, you are supporting our infrastructure, can you take over our business processes as well?" It's very opportunistic in terms of our approach but it is also very opportunistic in terms of the customer's approach. That is going to be more and more the future of the way IT services are delivered. Ultimately, the technology—the application, the infrastructure, and the processes—will be delivered through a cloud configuration, if you will. In the next five years or so, however, I think you are going to see business process outsourcing evolve to become more closely aligned to application and infrastructure outsourcing. So, yes, I do see a greater alignment of BPO/ITO, but not in the way that we traditionally thought about business process outsourcing three-to-five years ago when companies just outsourced all their F&A or outsourced their HR. I think ultimately that will have changed.
PF: And finally, after being an analyst for so many years, how’s life on the service provider side? What have you learned that has surprised you?
SM: – First of all, I love being on the service provider side, although it was something that I was a little bit nervous about. For such a long time, I really took great pleasure in helping both customers and vendors succeed in their relationships. So on the vendor side, I felt a little like I was going to the "dark side." But I must say that after six months or so here at UST I am so thrilled that I made the switch. In terms of things that I have learned, there is a lot about the vendor's side of the story and the vendor's positioning, but I have also learned even more how I can help make the customer and the vendor successful at their craft and execute on these deals. There is also much that I did not know as an analyst that I now know as a vendor. Ultimately, I think my work life is much richer by combining my experience as an analyst with my new experiences in the vendor world.
PF: Steph, thanks so much for sharing your views and experiences with us – and best wishes on the service provider side
Stephanie Moore (pictured) is Chief Marketing Officer of UST Global
Mark Stelzner roused some passions last week with a great blog post discussing how some traditional media are highlighting the need to regulate bloggers with possible "conflicts of interest". For example, Workforce Magazine's online article discusses the impact of controversial HR bloggers, such as Cheezhead's Joel Cheesman.
At the heart of the debate are the issues surrounding which industry entities are more credible for regaling information to the marketplace. My take is that
everyone has potential conflicts of interest, and blogging has leveled the playing field across industry entities (journalists, consultants, analysts / marketeers, vendors and buyers).
While, in the past, analysts and journalists ruled the roost when delivering controversial and impactful information to the world, the new crowd of industry bloggers are taking their share of the spotlight, once they have successfully leveraged their industry network into a social-media setting. And while there is a real case to be concerned about the odd manipulative blogger furthering their own specific agenda, my take is that we're in a new media world, where bloggers are earning trust and credibility over time with their respective audiences. Let's be honest here – every corner of the industry is potentially conflicted – here are some examples:
1. Magazines which sell advertising space to vendors adjacent to favorable articles that hightlight their products and services. This has been commonplace for decades;
2. Analysts that produce case studies, or favorable write-ups, of their paying vendor clients (gasp!);
3. Consultants that take money from vendors for consulting or research work, and still run vendor-selection evaluations that involved those from whom they take money (shock! horror!);
4. Vendors which leverage compelling rose-tinted content to sell their own products (how could I dare suggest that?);
5. Buyers that have been influenced by their own past or present vendor relationships and lack a broader view of their industry (c'mon… we've all seen this).
Bloggers are appearing from all these five mediums, and it doesn't matter so much what they do for a day job – what matters is the credibility and style with which they deliver their blog-talk. For example, when I began this blog, I worked for a management consultant, and since switching over to the analyst world two years' ago, have seen very little difference with the audience regularly visiting here, or the tone of debate. If anything, working for a reputable analyst brand can sometime hold you back from far-reaching opinions, if you're not always backed up by some sort of datapoint.
Most successful bloggers today seem to be coming out of consulting businesses (for example Deal Architect, Human Capitalist, Inflexion Point, Software Insider and SpendMatters) than any other business. The next challenge is for some of the leading minds in vendors to use the blog-platform more effectively to air industry issues, not to mention experienced practitioners. If anything, vendors are the least conflicted, as you know exactly what their agenda is. When dealing with other entities, their agendas are not always so obvious, and you just have to roll with your own trust of the writer.
All-in-all, the judgment over the credibility of a blog is tied more to that individual airing his/her views, as opposed to their day-job. If a blogger is judged to be overly-biased, or obviously conflicted, other bloggers are always quick to point this out and challenge that blogger's credibility. Credibility is in the eye of the beholder, and bloggers who've earned their chops put theirs' on the line every time they post.
ABSORB INFORMATION ON THIS BLOG AT YOUR OWN DISCRETION. THERE ARE NO GUARANTEES OF COMPLETENESS, CORRECTNESS OR APPROPRIATENESS TO YOUR INTENDED PURPOSE OTHER THAN YOUR EVALUATION OF THE WRITER AND MEDIUM’S INTEGRITY.
So Dell finally made its major play into the IT services enterprise arena announcing a $3.9bn deal for the Texas-based Perot Systems. Unlike the HP/EDS mega-merger of last year, there is a lot less overlap between the merging entities, however, you have to assume this is more of a play by Dell to transform its commodity hardware business by refocusing its future strategy on services-led engagements.
However, while there isn't much overlap, there also isn't a lot of synergy. Why should Perot customers want to buy Dell equipment all of a sudden? Most CIOs today are looking to move away from hardware-centric IT delivery models, and onto more on-demand cloud computing models. If anything, it's more of a play for Perot to push services onto Dell's customer-base. It also opens up the lucrative healthcare IT market to the newly-merged entity.
While I applaud a bold move by Dell to transform its business model, work has yet to be done to elevate Perot's IT/BPO services business to the top echelon of service providers at a global level. Namely, Perot hasn't yet fully exploited its presence in healthcare to position leading edge IT/BPO offerings in that space, especially with the market ripe for exploitation in light of the new government initiatives, namely ICD-10 compliance and digitization of patient records. If Dell can quickly leverage this merger to make a further strategic acquisition in this space, then you can see a new player emerging. However, if they spend a whole year trying to restructure these firms and take their eye off the ball with regards to broadening the service offerings, this could present a window for several of Perot's services competitors in the healthcare space to step in…
You also have to wonder whether the largely US-dominated vendors are going to continue to consolidate in light of fierce competition from the Indian-dominated global providers. ACS-CSC anyone?
As a wise man once told me, "there's nothing quite like visiting Tampa in late October". Many years on, his prophecy is coming true, with the second annual North American "FAO Summit", being held in the Saddlebrook resort, 20-22nd October.
Anyhow, come and meet a compeling line-up of speakers, panelists, hobnobbers and politicians that include several outsourcing PMOs (for some strange reason they managed to attract several from beverage producers…), former senator John Sununu (one of the five panel members responsible for the oversight of TARP funds), a bunch of advisors, service providers and some crazed blogger.
As usual, a large discount is offered to the cheapskates who visit here, so click on the icon to the left to register quoting the code "FERSHT2". If you are on the buyside and evaluating BPO strategy, drop me a note.
We inspired a lot of offline debate when we discussed the challenges facing BPO providers delivering so-called “Platform BPO” solutions. Bottom-line, if BPO service providers are competing for commodity services engagements which are underpinned by software platforms that are widely deployed by several other service providers, they face a major challenge of differentiating themselves to win new clients and avoid a price-war for new business.
At the enterprise level, selecting a BPO provider to process transactional business services for a major Oracle or SAP-based engagement is dependent on the providers’ global scale, brand and competency. For these large-scale transactional BPO engagements (i.e. accounts payable, payroll etc), it’s largely a commodity market these days. However, the battle is on to provide industry-specific solutions, such as health insurance processing and revenue-cycle management, banking-specific services (i.e. netting, lock-box services), retail merchandising, legal services, healthcare informatics etc etc.
For example, I had a great conversation last week with Mark Stiffler, CEO of sales compensation provider Synygy. He was faced with two choices for his business: either to provide an on-demand managed service to his clients, or license his software through BPOs in the channel. Sales compensation is an area that can be delivered on a set of standard processes, with some unique personalization to the client. It’s also an area where there’s a hell of a lot of value an outsourcing provider can add to optimize their clients’ sales performance management processes. Hosting the software provides the utility offering that can enable a high-value growth engine for the business. However, when enabling clients to make the most of out these services, they need some quality support that understands both their industry and their business. How many times have you heard of clients who buy a software package and only use a fraction of its functionality? The BPO channel should be there to enable clients to maximize the process flows on offer.
While Mark has pursued this managed services (BPO) strategy, some of his nearest competitors have opted to pull-back from a services-delivery model and push their software package through BPOs in non-exclusive agreements. While the latter strategy might make sense for the software vendor in reducing its own cost-of-sales, the BPO providers are unlikely to invest a great deal of money in high-quality support for a standard software package they don’t own. They’ll simply add the hosted software into a broad portfolio of adjunct services.
Today, we don’t know whether Mark’s strategy will ultimately win out in his market, but sales compensation is an area where most clients need quality support, so you have to assume Synygy will continue to grow organically as a managed services provider, and could ultimately become an attractive acquisition candidate for one of the BPOs. You have to applaud Mark’s firm for making a successful transition from a software to a managed services provider. Too many other software providers simply find that shift in business model too much of a cultural change, and often too much of an initial investment to stomach. My fear is many software providers will go out of business if they fail to choose the right managed services strategy for themselves and invest in making that cultural shift.
In commodity markets, such as payroll, the scale-game through the BPO channel is clearly the way forward (for example ADP/SAP) because the managed service will normally cover all the key areas the client needs for successful delivery. Once you have your payroll and accounts payable up and running, how much “innovation” do you really need, if you’re happy with the performance and price?
However, for business areas where clients really could really benefit from best practices, especially when they can be tied to industry-specific scenarios, the “Business Cloud” model is clearly the way to go, where the provider can deploy the computing, business support and alignment services its clients need to maximize the use of the software in a on-demand model. And will we be even be talking about “software” in a few years? It’s the process IP that software supports which is really what’s at stake here.
Is there a recurring theme here? US-based giants with faltering commodity business models from yesteryear, making very late plays to get into the IT-BPO services business?
While I could see some synergies between Dell and Perot, this one's even tougher to fathom, unless Xerox has further plans to marry ACS with a stellar IT services acquisition.
ACS was one of the early darlings of BPO, and was right at the top of the competitive tree in the early 2000's whenever a large Finance & Accounting, HR or call center deal was up for grabs. It would always give Accenture and IBM a run for their money in BPO pursuits, and had a compeling culture and engagement methodology for many of the old world BPO engagements (i.e. a lot of lift and shift and staff re-badging).
Sadly, ACS has rather fallen away in recent times, and has struggled to cope with the aggressive entry of the Indian-centric global competitors into the BPO space. The new generation of global services providers are bringing passion and combined IT-BPO prowess into the mix, in addition to global sourcing models that are driving down the price-points.
Xerox, on the other hand, has been eyeing broader business services for a while, and I can see why they'd find part of the ACS portfolio attractive – a broader client-base, great presence in healthcare, government, hi-tech and consumer business, a strong BPO brand and global delivery presence. ACS also has a strong IT services business, but not on the same scale as the top tier.
The real challenge for this combined entity, is to cope with the new throng of competitors in this space: Cognizant, Genpact, Infosys, TCS et al., and not solely the incumbents such as Accenture, Capgemini and IBM. The combined Xerox-ACS business will have a short-term potential to consolidate a commanding position in back-office BPO areas such as document management, call center, payroll, benefits admin and accounts payable.
However, clients today are spoiled for choice with other service providers which can offer the same services at lower cost. Xerox also needs to make a quick move to push a utility delivery model, based on common processes and standards, with compeling industry-alignment. Continuing to push old-world BPO, where the customer shifts existing processes with limited transformation, is not a recipe for success.
My take? If this combined entity were to merge with a strong IT services provider and develop a coherent IT-BPO strategy, then we really have something to talk about. Funnily enough, if you combined the new Xerox with the new Dell, then you'd be looking at a company with a lot of future potential…
As many of you close to me already know, after 14 years in the analyst and management consulting community, I am going to take a little break and make a few changes.
I'd like to thank publicly AMR Research for a wonderful couple of years, where I got to spar with some great people, service more clients that I care to remember, and have a lot of fun bantering with so many of you who frequent the Horses. I'd especially like to mention some great analysts with whom I'd had the pleasure of working: Dana Stiffler, John Hagerty, Simon Jacobson, Bruce Richardson and Mickey North-Rizza – a real credit to the analyst industry (and will, hopefully, be featured here in the future). I'd also like to thank Helen Scott for her sheer perseverance…
If you're wondering how to get hold of me, you can always mail me here. Onwards and upwards my friends -:)


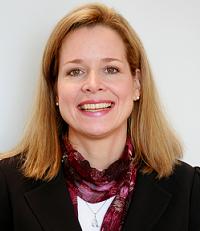 One of the most prominent industry analysts in sourcing over the last decade-plus has been Stephanie Moore. Steph started out at Gartner, before spending time at Giga, and most recently Forrester Research, where she built an industry-wide reputation as an outspoken and respected figurehead of the IT services and outsourcing world.
 Mark Stelzner roused some passions last week with a