One of the grandfathers of the outsourcing industry is Peter Allen (see his recent interview with us), who has established himself over the years as one of the pre-eminent thought-leaders, practitioners and faces of the industry. Peter has also been one of my closest industry companions in blogging on global sourcing issues, with his popular "Consider the Source" blog-journal. He has also been the consistent face of leading sourcing advisor TPI.
Yesterday, Peter resigned from TPI to pursue other opportunities in the industry, after many years with the firm. There is no shortage of suitors for his services… and I look forward to hearing where he lands. Peter wanted to share his personal thoughts with Horses readers at this time:
"The global outsourcing and offshoring industry needs to step up to a new level of performance. The sources of leverage that can bring value to companies far transcend wage arbitrage. I want to help bring to reality a new class of leverage – of investments, platforms, and solutions."
"It has been a privilege to work alongside my colleagues at TPI. A twenty-year record of great outcomes for clients and providers alike is the product of commitment to a culture of value creation for all participants. We do that."
"The current global recession is an awakening for the industry – as much opportunity for redefinition as it is risk of irrelevance. I really believe that the winning equation is one that maximizes the power of leverage to the benefit of productivity. That means that buyers and providers adopt new models for partnership to weather variances in economic conditions."
These are critical times for the outsourcing advisors. The process of managing outsourcing transactions has increasingly commodotized over the last couple of years, and the recession has only exacerbated this issue. The sourcing advisors need to focus on helping clients disrupt their current global business infrastructures, help them execute after the transaction and manage the ongoing outsourced environment.
People like Peter understand this, and I hope advisory firms like TPI continue the work he has done in helping drive these new areas of competency, and hiring consultants who have other skills than solely deal negotiation. Those that focus purely on cranking out transactions will struggle to grow in this new environment.
Good luck Peter - I know many people in the industry join me in wishing you well on your future journey.
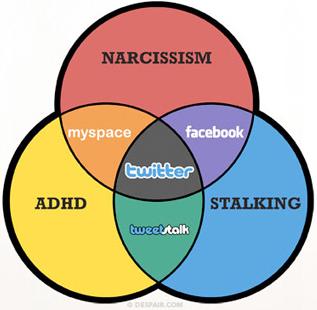
After our recent banter surrounding Executive ADD, I thought I'd share this hilarious venn diagram from Despair.com's blog on social media:
"A gorgeous, 8-color masterpiece which captures ever so brilliantly the three behavioral disorders propelling the continued phenomenal growth of today’s most widely-trafficked social media sites. And at the intersection of the dysfunctional forces of Narcissism, ADHD, and Stalking resides today’s fastest growing social media experiment of all- Twitter…"
I was having a little joke yesterday, where the premise was: "So what do we do once all the jobs have been offshored?" My initial solution was: "That's easy - we create great low-cost skills here, and we bring them all back". The other partaker in the mirth added: "Wrong – we will still be offshoring, as all our business headquarters are moving out too. In effect, we'll be offshoring jobs to America".
As we rolled around on the floor in uncontrollable laughter (OK, it wasn't that funny), it did hit home how unattractive the US is becoming for businesses.
US corporate taxes are among the highest in the world.
The cost of living and wages in business centers such as New York, Philadelphia and Chicago is off-the-scale.
The cost of healthcare is a killer – and, despite the excellent intentions of this new proposed healthcare reform, the tax burden on the US business is going to get even worse. For the cost of one years' benefits package in the States, you can hire a full-time ABAP programmer in your offshore captive for that entire year, or pay for half of one (for the entire year) with a service provider.
Other Western countries are far more corporate-friendly. I was helping a friend with a business plan the other day, and the cost of hiring qualified graduates in London (yes, London) is half that of New York (and getting even cheaper in this market). Why even consider setting up a global business in the US these days in this virtual environment?
As much as I admire all the efforts of President Obama to drive reform and economic stimulus into the US economy, I just don't see the environment for the US business to thrive and create new jobs being created. I'd like to see stimulus money being allocated to helping businesses create new knowledge-jobs that are competitive with those on offer from India, Europe, China etc. The way things currently stand, the US business environment has never been so ripe for outsourcing – not just for accessing lower-cost skills, but also for our businesses themselves.
The industry's next phase of growth is unlikely to be dominated by the mega-mergers of the past (DEC/Compaq, HP/EDS etc.). It's going to be focused on service providers moving into partnership engagements with clients, where they can develop specific IP and industry process competence.
I see this trend escalating in the application development arena, as this area is now approaching significant scale and maturity, but also believe this will pave the way for future BPO development, as service providers find new opportunities to layer on business process services that compliment their application development work. It's really about learning specific industry process, how they can be enabled and optimized by smart applications, and processed by smart people who add value.
This isn't simply lift and shift where the service provider does the same with less – it's where the service provider brings specific expertise to the table that allows the client to scale its business globally. It allows the client to focus more heavily on its core competencies, which provide the real value for its own growth. And it allows the service provider to develop specific industry process knowledge of its client's industry that is can replicate across its own knowledge workers. The maturity of the application outsourcing marketplace is now going down this path, where the leading service providers have the lions' share of the talent – and the scale – to provide the technology development services that allow clients to invest in their core industry services that make up core value proposition. Why invest their scarce resources in IT development when they can find a third-party to do this for them and invest in areas that will improve the front-end of their business?
One prime example of this is the new partnership between UK-based industrials magnate Invensys and service provider Cognizant. Invensys wants to focus on on its core competency of product definition and architecture and developing its industrial automation platform, with Cognizant being its technology partner for product development.
Invensys can focus on where it's best, and Cognizant can make a surge into the manufacturing industry. Invensys will learn from Cognizant's technology skills and Cognizant from Invensys' manufacturing process and operations prowess. Jobs are not lost, and existing employees are going to enhance their careers with new industry and technology knowledge. If this partnership works, both firms will end up creating more jobs to support their expanding business portfolios.
And just when you thought you were in the clear, here's another webinar for you…
In recognition of recent shifts in the global economy many global sourcing executives have determined a more “risk averse” approach toward their global outsourcing portfolio is a prudent and necessary means to ensure supplier stability, less volatility in certain markets and enhanced skill-set options vis-à-vis regional workforces.
Many executives are asking, what are the Near-shoring advantages? What are the trends in Outsourcing and how are emerging destinations (such as Brazil) affecting this landscape?
Join us for an insightful and interactive discussion where we will discuss Latin America, and how a near-shoring strategy in an emerging destination will benefit your IT Outsourcing portfolio.
Date: August 4th, 2009 Time: 11.00 AM PDT / 2.00 PM EDT
Analysts Phil Fersht and Dana Stiffler, ITO & BPO Services, AMR Research, will join Mr. Bob Mejerle, VP – Outsourcing Practice, North America of Politec Global IT Services to on this LIVE Executive webinar.
We’ll also be joined by our Moderator, Frank Casale, who will host an open Q & A session after the briefing. If you are a C-level Executive, Vice President and Line of Business Owners responsible for: Global Sourcing, Program Management, Finance, Information Technology and Operations, then this webinar is for you.
My definition of corporate failure in this market: "We're gonna ride out 2009 and go for it next year." What are you going for? What are you riding out? If you want to remain successful, you better get your act together now and formulate a game plan.
Too many firms are sticking to their old business models, in denial that they need to do anything different (besides firing a few people), and cling to the vein hope that their fortunes will dramatically turn around in 2010…by doing NOTHING. And I can be 100% sure that everyone reading this is either working for a firm with that attitude, or knows someone who is. Smart executives sense stagnation, and a lot of top talent is re-thinking whether their current employer has what it takes to prosper in a post-recessionary economy. (P.S. a prize is available for the first person to reveal this icon of executive innovation from the '80s…).
And the top tier isn't always offering the most appealing place to work in this market – am seeing several top executives broadening their horizons for unique companies geared for growth in this new economy. Start-ups and small companies, for example, which are plugged into the new economy are becoming vogue. Many people are realizing that no job is particularly secure anymore, so if you're going to take a risk, why not now?
We're now seeing the fog lift, and several smart service providers are dipping into the market to pick up top talent… and naturally this starts with sales execs. In industries such as payroll and HR outsourcing, it's all about relationships, and the recent hiring of Kephanie Landess by British upstart HRO service provider Patersons, is an example of top talent focusing on joining upcoming providers with a unique vision.
Kephanie could have handpicked many of the leading HR services or software brands for her next career move, but she chose a firm that isn't that well-known, but has great potential for future growth in this market. I keep a close eye on the payroll/HRMS outsourcing market and have been initially impressed by Paterson's SaaS-based multi-tenant HRO solution, with the firm beating out tier 1 competition to win new business with major corporations such as Wachovia, Interdean and Henderson. With 10% of mid-large firms looking to move onto managed payroll outsourcing services over the next year, this is not a bad market to be in. You just need to make sure you're working for one which can service clients globally, and has a proven Opex-based model that doesn't necessitate huge upfront transformation costs.
I asked Kephanie to let readers here know why she made this decision. Over to you Kephanie:
"Here is a quick summary (well I intended it to be quick) of why I joined Patersons:
"I wanted to work for a company that is not “set in their ways” and have ability to make an impact in moving from status quo offering in market to what the market requires;
"I wanted to work for a company that is not “set in their ways” and have ability to make an impact in moving from status quo offering in market to what the market requires Work for a company that is focused on critical niche solution as opposed to “jack of all trades” approach;
"I have been seeing an increasing trend of organizations trying to act like global organizations due to the increasing demand of having employees stretch globally, but didn’t have the means necessary to support all populations as it relates to Payroll & HR (the market has tried and tested what's out there and it's not adequate);
"I was looking for an organization that is proactively responding to the needs of the market for a truly global Payroll & HR technology (need alternative to other providers–which can meet needs of certain segments, locations, solution tiers, but not holistic approach to all global HR & Payroll needs);
"The market requires the same single provider that can offer global integrated Payroll & HR solutions whether they have one employee in one country and 10000 in another country and scalability for growth strategy– (other providers can offer bits and pieces to accommodate various populations but not single solution across whatever populations/countries necessary)."
In case Kephanie's boss, Karen Paterson, reads this, I can assure her that Kephanie contributed about 10 further points attempting to justify why Patersons is the greatest offering since the feeding of the 5000, but I do have to draw the line somewhere 🙂
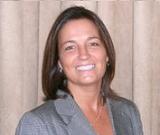
Kephanie Landess (pictured) is Vice President of Sales for Americas for global HR services provider Patersons. She can be contacted here if you want to buy some SaaS…
Anyone from the world of HR, who cares about the impact technology has on their existence, is congregating at the infamous HR Technology show in Chicago on September 30-October 2, hosted by the legendary columnist Bill Kutik (pictured), the undisputed captain of HR controversy.
It is the world’s leading event in the HR sector, and each year attracts 2,000+ high-level HR practitioners, software and service vendor CEOs. In addition, most of the HR sector's industry analysts, bloggers and foghorns will be there - including such celebrities as Jason Corsello, Mark Stelzner, Naomi Bloom and Vinnie Mirchandani. They come for the excellent no-sales-hype conference sessions, the largest show floor of 250 exhibitors, and Bill Kutik’s signature vendor Shootout session, which this year features software giants SAP and Lawson taking on their smaller rivals Salary.com and Plateau. I am also assured that the word "Cloud" is to be officially banned from the festivities…
Here’s how you can get the $470 discount off the $1,645 regular registration rate:
The new wave of BPO deployment has arrived quicker than many of us anticipated. The recession has driven some common-sense into a BPO value-proposition that was previously centered predominantly on some form of labor arbitrage, with many service providers muddling their way through to attempt to run their clients' process for less cost – and make some sort of profit. Sometimes they pulled it off, other times they failed. Many are currently in a state of semi-transition, with the success of their BPO engagement still hanging in the balance.
Now we've clearly arrived at a turning point in BPO development, which we can put into the following three categories:
1) Straight Lift and Shift: the antiquated form of BPO where client takes "as-is" processes, hands them off to a provider, which subsequently attempts to run with lower staff costs. In many cases it's a simple "re-badge" of existing personnel, with the provider simply employing smaller numbers of the existing delivery team to make a profit on the deal. In most modern cases, the provider will supplement onshore staff with offshore. There is little (or no) enhancement of software applications to standardize workflows and add a modicum of transformation into the engagement.
Likely outcome: Inefficiencies with processes are magnified considerably, change-orders and procedural changes are cumbersome and expensive, client finds it challenging to reduce onshore headcount, and anticipated cost-reduction is not reached.
2) Lift, Shift and Transform: Same as Lift and Shift, but the client and service provider work together to re-map existing processes onto a pre-defined new set of processes.
These can often be standard and may adhere to a particular ERP template, of could be customized to requirements specific to the customer. The client and provider need to determine the incremental transformation costs and price them accordingly over the course of the contract (or as a single fixed fee).
Likely outcome: Initial challenges as processes are moved offshore, but standardization on new technology should create new efficiencies and the opportunity to eliminate unnecessary process steps. Initial cost savings may not be as much as a pure process play, but the aggregated savings over a multi-year period are almost always greater.
3) Tranform onto a standard offering with some degree of personalization: My good friend at SAP, Gianni Giacomelli, sent me in some of his thoughts on this standardization/personalization balance, so am going to hand you over for his thoughts here. Over to you Gianni:
I argue that a few service providers can and should get smarter at executing on the key vision the industry was built on: service provider being better (read: cost, quality, risk) than each individual client because it syndicates practices and scale across customers.
Trouble is, this is not “business as usual” for many service providers with a technology system-integration background, where you get paid for the extra frills you do on each customer. And it is not easy for those coming from small-scope services, who struggle with the intricacies of a consultative value-sale cycle. It will take guts and smarts, but it can be done – like it has been done in many industries where process and technology maturation suddenly help business models change. Here are some key tenets.
Decide scientifically what scope you really want
Here the concept is simple but the analysis is not banal – which means that the right people, if well determined, can build a competitive advantage out of this.
Scope decisions mean analyzing which processes benefit from standardization, i.e. for which ones the cost per unit decreases when volume goes up, or which ones can be optimized from “typical practice” to “best practice” even if at the same level of scale. In both cases providers need to standardize the way they do certain things – otherwise they do not attain the required scale, or are not able to achieve the transformation required to reach “best practice”.
Standardization can happen along two dimensions: processes (e.g. invoice management, dunning, garnishments, …) or delivery layers (automation tools, self-services, tier-1 contact centers, tier-2 global experts, tier-3 local experts). There are methodologies that can help this exercise – again concepts are simple, but implementation not trivial. First, identify what is material: forget about the “long tail” of small subprocesses, especially the ones you know are guarded by anxious stakeholders, as they might distract you from the big picture. This is not banal, as often the cost of service delivery is not well understood at single-process level. Effectively, the provider will need to perform a BPO-specific activity-based costing (ABC) of the design, build, run phases of the service.
Then: providers can start top-down with benchmark-type data to determine the economic behavior of such processes/layers when scale or best practices are applied, or (if you suspect external benchmarks are inappropriate) they can benchmark different client organizational units of the same company and ultimately get to the same result; alternatively, they can work bottom-up and identify processes where resource utilization is poor because of demand volatility (a perfect candidate for pooling resources, thereby increasing utilization), or where fixed costs (e.g. automation, implementation of self-service portals, setting up physical facilities) are substantial and therefore scale becomes key.
This exercise will also help pinning down what should NOT be standardized, and either left to the client retained organization or kept in the outsourced scope but allowed to be personalized. While these processes may dilute the overall “provider advantage”, they can be valuable for horse-trading when it comes to agreeing with the client.
Gianni Giacomelli (pictured) is Head of Strategy and Marketing for SAP’s BPO business unit.


 One of the grandfathers of the outsourcing industry is Peter Allen (see his recent interview with us), who has established himself over the years as one of the pre-eminent thought-leaders, practitioners and faces of the industry. Peter has also been one of my closest industry companions in blogging on global sourcing issues, with his popular "Consider the Source" blog-journal. He has also been the consistent face of leading sourcing advisor TPI.
 I was having a little joke yesterday, where the premise was: "So what do we do once all the jobs have been offshored?" My initial solution was: "That's easy - we create great low-cost skills here, and we bring them all back". The other partaker in the mirth added: "Wrong – we will still be offshoring, as all our business headquarters are moving out too. In effect, we'll be offshoring jobs to America".
 My definition of corporate failure in this market: "We're gonna ride out 2009 and go for it next year." What are you going for? What are you riding out? If you want to remain successful, you better get your act together now and formulate a game plan.
 In case Kephanie's boss, Karen Paterson, reads this, I can assure her that Kephanie contributed about 10 further points attempting to justify why Patersons is the greatest offering since the feeding of the 5000, but I do have to draw the line somewhere 🙂
 The new wave of BPO deployment has arrived quicker than many of us anticipated. The recession has driven some common-sense into a BPO value-proposition that was previously centered predominantly on some form of labor arbitrage, with many service providers muddling their way through to attempt to run their clients' process for less cost – and make some sort of profit. Sometimes they pulled it off, other times they failed. Many are currently in a state of semi-transition, with the success of their BPO engagement still hanging in the balance.