What are you desperately seeking? Rosanna was Desperately Seeking Susan. Phil and Esteban? If you know them like we do, you know they’re Desperately Seeking Innovation.
So, as official provider of research and insight for SSON’s premium buy-side members, Phil and Esteban are teaming up to lead a session for the entire HfS Research and SSON communities:
Desperately Seeking Innovation in BPO Tuesday, 9th November 2010 3:00 PM GMT 10:00 AM ET Register here.
The session, being made available to all HfS Research and SSON members this time only, will be based on the recent HfS Research study, Desperately Seeking Innovation in Business Process Outsourcing: Enterprises Speak Out. The report discovered most buyers of BPO services alike trimming 30% of their costs on one process–at the start–then 50% on another. But once those costs disappear from the balance sheet, they are quickly seeking new initiatives to attain new thresholds of productivity or revenue growth: what we terms “innovation.” In the call, we’ll share the views of the nearly 600 shared services and outsourcing executives who we surveyed as part of the report.
This call is part of a series of of Group Member calls we’ll be hosting specifically designed for SSON premium members. We’ll explore the experiences and expectations of today’s enterprise buyers when it comes to achieving innovation and we’ll offer actionable recommendations for devising a strategy to improve your innovation agenda.
Desperately Seeking Innovation in BPO
Phil Fersht, HfS Research Founder and CEO
Esteban Herrera, HfS Research Senior VP
Guy Fawkes ponders service integration strategy and blowing up the outsource model
Euan Davis, Managing Director of HfS Research’s European Practice, lives in the UK, and has the pleasure of celebrating Guy Fawkes’ Night ever year, where they burn an effigy of the man who tried to blow-up Parliament in true paganist style… accompanied by fireworks.
Curious, as I’m sure anyone who tries to blow-up Congress would likely be hero-worshiped stateside, or asked to join the Tea Party or something…. anyway, it’s as close as the Brits ever get to Disney.
Today, as Euan readies for his annual trip to a bonfire, he muses on fireworks–municipal ones and the type he expected at a session about service integration last night, at PA Consulting Group’s SSON networking evening. Take it away, Euan…
Service Integration: Guy Fawkes Fireworks or Damp Squib?
Friday, November 5 is Bonfire Night over here in the UK. Like many others I will be heading down to our local municipal bonfire to watch a proxy “Guy” thrown on top of it followed by some great fireworks—some towns really go for it and burn effigies of our politicians or pond-life celebrities. Trying to explain the concept to my kids (especially the burning of the catholic at the stake thing) is always tricky but as they get older and learn more history at school they start to get it (I hope). So I was expecting fireworks when I attended attend PA Consulting Group’s SSON networking evening to talk about how UK energy firm Centrica was tackling service integration, a topic close to my analyst heart…
Unfortunately the executive in charge of shared services at Centrica wasn’t able to attend so we didn’t get to hear how the company managed its many IT suppliers and IT contracts and connected them to its overall business performance. There is a great story here at Centrica I suspect as I’ve heard rumblings of multisourcing and systematic deal-making over there for some time and I know of several other energy and utility firms investigating systematic multisourcing models. What we did hear last night was PA Consulting outline its new service line focused on Service Integration and Optimization—it’s in the right direction but I am curious to see how this works in practice and if they can actually sell it. They made the point that it’s the dynamic people that pull the levers around service integration who really make it work. But my thinking is they need a structure within which they can operate. So key questions I want to ask is around ownership: who owns the contract? Who owns the overall program management? Who owns the interface to the internal stakeholders? Where do the red lines sit between a customer and its service integrator?
I do foresee demand for specialized “service integrators” growing and not only for running and enhancing an existing set of contracts, but also for setting the terms of play with an ecosystem of providers. These best of breed providers will stretch between business processes, applications and infrastructure and pull together around clear business outcomes—see my thoughts on CSC’s position here.
The question in my mind is would firms like Centrica want to do this role themselves or are they rethinking how some of the red-lines fall between their internal governance teams and an external service integrator because there simply not enough dynamic people to do it. Are they really prepared to let the fireworks off, rethink their sourcing models and use best in class service management to couple service delivery to business outcomes, drive cross provider innovations to improve processes and reduce cost? I can’t wait to find out.
Always happy to discuss further – you can email me at euan dot davis at hfsresearch dot com
The "B" issue in outsourcing: always invited to the party, but rarely adds much value…
Anyone close to the world of outsourcing deal-brokering and performance measurement has been exposed to the infamous “B” issue.
I recall a debate with several experienced buyers, who had anything from 250 to 1500 benchmarked line-items in their respective service level agreements. When I asked them how many of these they actually cared about, no-one could think of more than a dozen… Over to our roving expert in sourcing best practice, Esteban Herrera to discuss the matter further…
Benchmarker Beware! How to use Benchmarking Successfully in Outsourcing
Benchmarking is a misused and misunderstood tool in outsourcing. Almost everybody’s contract has a provision for benchmarking, and in almost all cases it drives the wrong behavior for both parties. A good benchmark (and there aren’t many good ones out there) can be a valuable tool to start a conversation, yet our industry tends to use them as the end of a conversation. Benchmarking data is only useful in the context of a Market Intelligence Program. HfS Research defines a Market Intelligence Program as a coordinated set of insights, professional networks data sources, industry research, and processes that give outsourcing buyers a complete, accurate view of their deal relative to the industry.
Unfortunately, I’ve seen clients artfully leverage expensive benchmarks to unwittingly reduce the value proposition they are receiving from their providers. I’ve seen well-intentioned providers ruin large relationships over benchmarking result disputes. Most often, I see the clause that cost hundreds of hours and thousands of dollars to negotiate be ignored in full or in part. So clients and providers spend lots of time and money (and “relationship capital”) arguing over the minutiae of a provision that isn’t likely to ever be used, and is even less likely to be implemented if it ever is used, and if accepted could have the exact opposite result it was intended to have!
The obscure methods of the benchmarking industry and the motivation of some individuals or groups to debunk results do little to help. Credibility of benchmark results seems to be at an all time low, and nobody seems to be capable of accurate BPO benchmarking. For these and many other reasons, users must tread carefully to get value from their efforts.
HfS Research has spoken to hundreds of client and provider teams to determine the proper way to leverage benchmarking, and to help clients determine whether benchmarking is even appropriate for their situation. You can get some pragmatic benchmarking advice in our HfS Rapid Insight piece Benchmarker Beware: How to use Benchmarking Successfully in Outsourcing, or by contacting your local HfS Research analyst at 1-800-BENCHMARKS-NOW-PLEASE
Folks – I’ve made no secret of my admiration for analyst-extraordinaire, Ray Wang, who is a true dynamo in the world of software. You can read a great dialog we had with Ray earlier this year.
Ray (view bio here) has made his name as a superior analyst at Forrester Research, with spells at PeopleSoft, Oracle and E&Y, before co-founding advisory firm Altimeter Group. He also has an industry-standard blog “A Software Insider’s Point of View“. Plus, he doesn’t have a single gray hair for a 38-year old workaholic insomniac…
Today, Ray announced the launch of a very exciting new research venture entitled Constellation Research, which comprises a collection of really smart and remarkable individuals and friends who are – quite literally – changing the way market research, commentary and insight is being served up to the technology buyer.
HfS Research is delighted to be the alliance partner for IT sourcing and BPO research to Constellation’s buy-side community, where we’ll be cross-pollinating some research with each other and collaborating to help educate the sourcing buyer make smarter decisions.
I, personally, have really enjoyed my interactions with folks such as Vinnie Mirchandani and Dennis Howlett over several years (in fact, Dennis remembers me when I was still in my analyst nappies back in ’95). We’re honored at HfS to get the chance to work with such a stellar collection of cosmic energy!
If you have any questions regarding the research alliance, please drop us a line at [email protected]
While the rest of the outsourcing world has been carrying on through challenging times, the most challenged of its citizens, Mahindra Satyam, has been quietly rebuilding a global business under the charismatic and candid leadership of Atul Kunwar.
A no-nonsense leader with a strong M&A background, he has charted a course to more than double the size of Mahindra Satyam and its sister company Tech Mahindra in three years. HfS would normally be skeptical of such a claim, but there is compelling evidence that this is a reachable stretch target.
In the unlikely event you have not heard of what caused the former Satyam’s challenges, here is the short version: In late 2008 and early 2009, it became known that the company’s chairman and founder and his brother had inflated profits and more as importantly, cash, for years, to the tune of almost $2 billion. At the time, the company was India’s fourth largest IT services provider and had an enviable portfolio of big-brand clients. After a brief period under government control, the Mahindra group stepped in to rescue it and turn it around, assuming its large and previously under-reported debt.
While investors suffered immensely as a result of the fraud, customers were relatively unharmed, as operations continued without interruption in most cases.
Today the company has completed a difficult stabilization period and is adding new logos, while pursuing growth in four key foundational segments:
End to End Manufacturing
Telecom
Enterprise Services
Vertical BPO
This Rapid Insight Report offers HfS Research’s take on Mahindra Satyam’s strategy and what it might mean to enterprise customers who consider working with the company.
HfS Research and The Outsourcing Unit at the London School of Economics have surveyed 1053 organizations on the future of Cloud Business Service
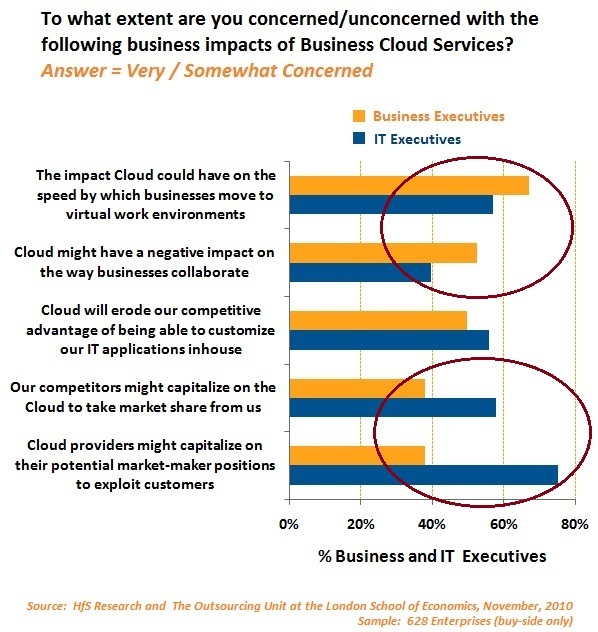
The colossus Cloud Business Services study we just conducted, in conjunction with the Outsourcing Unit at the London School of Economics, has served up some contrasting concerns that business executives are having versus their IT counterparts: Cloud’s potential impact on work culture versus its impact on the value of the today’s IT department.
Essentially, two-thirds of business executives have expressed concern over the impact Cloud business services could have on the speed by which they could be driven to operate in virtual environments. Moreover, a similar number expressed concerns over Cloud impeding their ability to collaborate with other businesses.
Conversely, IT executives are hugely worried (80%) by the potential for Cloud providers to exploit customers, but contradict these fears by also worrying about competitors leveraging Cloud to steal competitive advantage from them:
The bottom-line: when the business execs look at Cloud, they sense a major cultural change in the way they work, while IT executives are terrified by the potential curtailment of their value as the technology-enabler of core business processes.
The fact that the IT side of the house recognizes the competitive advantages Cloud can give business (see Part I), creates a massive challenge to the CIO today: how can their IT department become a vehicle for helping their organization find competitive value from Cloud. Because if the CIO fails to deliver this value, the business side will be forced to look at alternative avenues. We’ll talk about the business transformation implications of Cloud shortly. Stay tuned for more…
Still struggling to find that right governance model? Well you’ll probably still be after listening to this, but they’ll at least validate all the things that you should be doing, which you know you should probably doing, and are probably not, for whatever reason, but would love to if you could just get your boss to listen to you.
Or maybe your didn’t know what you were supposed to be doing, and will be guided down the path of enlightenment when you listen to HfS Research’s Esteban Herrera and Stan Lepeak from our research partner, EquaTerra, when they discuss “Outsourcing Governance Models: Which One Fits Your Needs?”
Click to hear Lepeak and Herrera's Podcast – "Outsourcing Governance Models: Which One Fits Your Needs?"
No one single provider can claim to have impacted the world of BPO with such verve and focus over the last five years, than that of Genpact.
During the “boom” years of Finance and Accounting BPO adoption, between 2005 and 2008, the Gurgaon-headquartered firm aggressively pursued nearly every large deal on the table, with a no-nonsense approach of lift-shift-transform BPO at aggressive pricing, bolstered by the GE Six-sigma and LEAN heritage and branding. However, the mindset-shifts of the Recession, combined with a more knowledgeable buyer, more credible competitors, and the ability of several Indian-headquartered and Western providers to compete more aggressively on price, have conspired to create a much more challenging environment for any provider competing for BPO business.
Most importantly, serious questions are now being asked of the leading service providers jostling for marketshare and position in the BPO business. Some providers are growing frustrated, and beginning to question whether they got their approach to BPO right. And the current speculation over Genpact ‘s future is forcing many of the BPO wannabes to gaze deeply into their navels to decide whether they want to get really serious about BPO. There’s been a lot of chest-beating, a lot of marketing, a lot of huff and puff right across the industry… now’s the time to see who’s really going to step it up.
Our view at HfS Research is that if any of the emerging service providers want to have a billion-dollar-plus BPO business that touches all industries, horizontal processes and provides a platform for that next phase of growth, once the low-hanging IT projects start to dry-up, they need to decide whether they have the appetite to swap-out a sizeable portion of their stock to acquire Genpact. Because if they don’t, another party eventually will, and there aren’t too many billion-dollar BPO firms left which will provide instant top-tier status and massive BPO global scale.
And if that acquirer doesn’t come from the sub-continent, if could well eventually come from a Japanese, European, or a Western business.
Here’s why the issue over Genpact’s future is so important to the future direction of the BPO industry:
Recent BPO market entrants are primarily IT services providers, which focus on rapid “penetrate and radiate” strategies. They are approaching BPO with the same strategy, and finding it much more resource-intensive, slower-going and lower-margin work.
When you look at the huge success of the leading offshore providers in the IT services market over the last decade, they based their growth strategy on starting small and doing whatever the client wanted to grow their “real-estate” within their back office. IT services providers such as Cognizant, Infosys, TCS et al. would quickly increase their presence within major global enterprises from 10 to 50 to 200 to 500 to even 1000 FTEs working on software support and development work – and with alarming pace. These providers were smart enough to realize they would quickly gain institutional knowledge of their clients’ processes and make it almost impossible to be displaced in the future. They brought offshore IT work into the corporate mainstream and branded India as the leading destination for low-cost programming work. To quote the CIO from a large German corporation recently “Ve prefer to use Indian firms for programming – that’s vot they do”. Kind of sums it up, right? However, BPO’s different…
The leading offshore IT providers are quickly realizing BPO’s a very different ball-game and may be forced into making a much larger investment than they ever intended, if they want to develop any BPO business of significant scale.
With the exception of a few transactional-based processes such as invoice and payables processing, order management, indirect procurement, the growth in future BPO areas is dependent on talent that can’t be picked up a en-masse from University training programs, or from infiltrating the campuses of neighboring lower-tier competitors with drive-by recruiting sweeps. With much of today’s BPO engagements, providers are creeping from 5 to10 to 15 to 20 staff in their clients… it’s at a completely different pace and scale, as the requirements are often more customized, more specific and it’s simply harder to find, train and retain the talent they need. They are simply not finding anything like the margins and growth that their IT business have enjoyed over the years. However, if they want to have a shot at winning the larger-scale engagements today, they will simply finding themselves running out of time to get a foothold in that game, if they persist with a “penetrate and radiate really slowly” strategy.
The Bottom-line: There aren’t many entry points left to get into the top-rung of the BPO business. Genpact may well be the last lever to pull.
All the leading providers have, or claim to have, both horizontal and vertical BPO capability. They know that having deep processing competency is incredibly “sticky” for growing deeper client footprints, and can help them develop institutional knowledge and comfort with clients, to remain with them for many years to come.
However, gaining BPO competency and scale isn’t like IT – there simply aren’t the hoards of dying European and tier 2 providers eager to get picked up. There’s really only Genpact left standing at the top-end, Xchanging and WNS in the mid-tier, and EXL, OPI and a few select others as the only really viable pureplays that will give an immediate leg-up in terms of immediate BPO scale and competency. Moreover, the old “let’s hang around and pick up a juicy captive” won’t wash anymore. Everyone’s run the rule-book over all of these, and there aren’t many worth considering, that make a lot of financial sense or provide suitable client scalability.
So this brings us back to price-tags and sensible investments. There haven’t been many past BPO investments that have been very successful – all have involved painful transition and slower-than-expected business growth – a fact that has put off a lot of firms making aggressive acquisitive BPO plays in recent years.
However, Genpact is another proposition entirely. It has massive BPO footprints across many major enterprise clients. It has global scale, industry competency and a good operational track record with clients. It really does represent one of the last major entry points for ambitious providers to make a “big bang” play into the BPO space. The big question we ask now is – who has the appetite, and who is serious enough about this business, to make it.
This morning I nearly choked on my cornflakes to the incredible revelation on CIO.com from analyst firm, Gartner Group, that outsourcing doesn’t save money. Everything I thought I’d learned over the last 15 years suddenly went up in smoke:
In Sydney for the Gartner Symposium, analyst Linda Cohen spoke to CIO Australia and said the idea that outsourcing is a problem solver is not always the case.
“We ask our CIO clients to consider outsourcing as an operating strategy rather than a problem solver,” she said. “Historically, outsourcing has been a bandaid and a way to fix the problem.”
Cohen said another misconception CIOs may have about outsourcing is that it will save the business money over a period of time.
“The number one reason they choose to outsource is this theory that they can lower their costs… honestly, history tells us the act of outsourcing doesn’t save money,” Cohen said. “The real problem is how do you sustain the lower cost to operate?”
So, let me get this straight, you do receive a lower cost to operate when you outsource, but face a challenge to sustain it? That’s a little strange, because when we spoke with 50 of the largest enterprises across the US, Europe and Australia recently, they all outsourced IT to save a lot of money, and the majority were looking aggressively at increasing their outsource scope to find further savings, while others were pretty content with the status quo. Noone felt their firm hadn’t benefited financially from the exercise, and those that had initial teething problems had largely got on top of them. And most of them actually liked the value and the access to specific software expertise they received from some of their providers – and their only real complaint was that they wanted more.
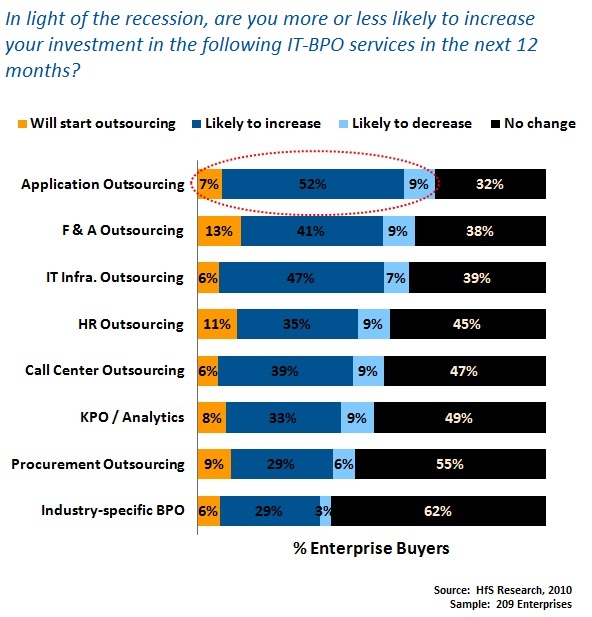
Moreover, when we spoke to another 209 enterprises earlier this year, 52% were planning to increase their application outsourcing scope this year, which also jives with the stellar growth results of many of the leading IT services providers this year:
In all honesty, I know where Linda Cohen was going with this, but – c’mon – most enterprises moved a good chunk of their operational ADM work to low-cost locations years and years ago, and are way beyond saving money on the operational stuff. Their challenge is to align innovative IT with the business to drive productivity and revenue, to explore Cloud Computing and smarter governance / multi-sourcing models. To advise CIOs that “the act of outsourcing doesn’t save money” is simply WRONG. Honestly, Linda…
Who has much time these days to read big clunky whitepapers, or (dare we admit it), long-winded esoteric research reports?
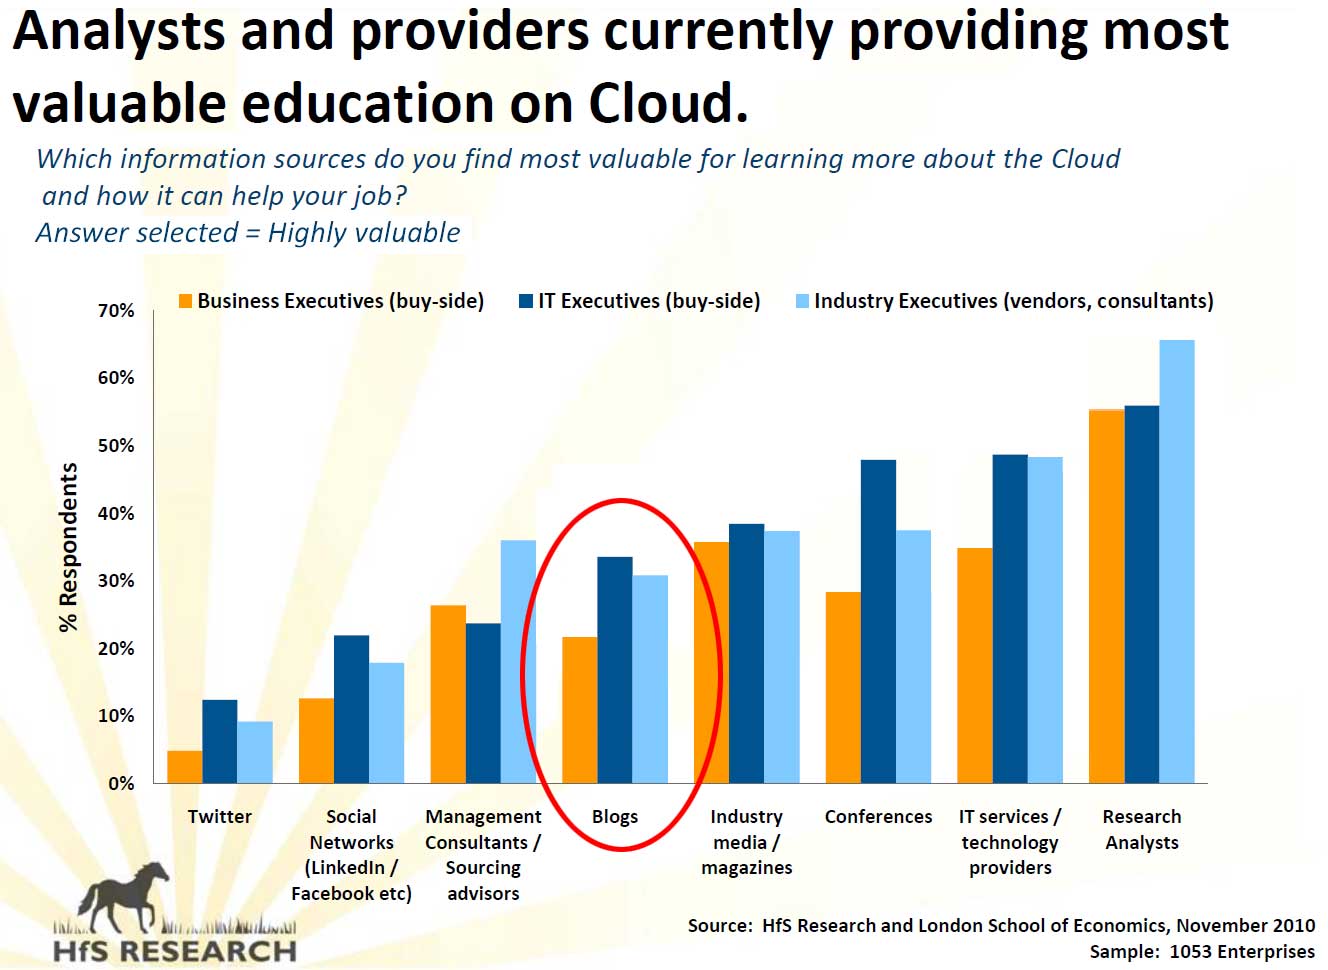
People are increasingly demanding their daily serving of content served up in more digestible and less headache-inducing chunks, as our latest industry-wide study reveals, where more than 1000 study participants across the sourcing industry have voiced the increasing importance of blogs and social media as one of their preferred learning tools for Cloud Business Services.
Lisa Ross, our Senior Vice President, Market Development & Operations, has done a lot of thinking about what we call “social sourcing.” So we thought there was no better place than here on the blog to have her air her views about the importance of blogs and social media to the sourcing industry. Lisa, take it away…
The Social Sourcing train is leaving the station. Are you on it?
The proof really is in the pudding for us all to see –just ask the professionals who recently took part in the Cloud Business Services study we ran jointly with The Outsourcing Unit at the London School of Economics. As this graphic shows, blogs, especially, are already mainstream social mediums for education to guide major strategic investments. And analysts are the most sought-after information sources too. (Good thing that we, at HfS Research, have both a media brand and a research powerhouse – lucky break!).
Click chart to enlarge
In our industry, advisors, providers, and other analyst firms are trying to hop on the social bandwagon – visit many of their websites and you’ll find all sorts of takes on social sourcing reality, like Share, Stay Connected, etc.
The huge challenge, however, is that they continue to struggle with positioning themselves as thought leaders: What should I say? How often should I say it? Who am I even talking to? Will anyone read past the title? And…in the end, will anyone really care (especially sourcing buyers)???
Having the courage (operative word!) to say what you mean, the conviction to back up your perspectives, the intelligence to make a bit of sense, a twist of humor, and the audience that really pays attention (easy to analyze via analytics) are challenges that Horses for Sources / HfS Research has conquered – and an additional reason why I joined here. I see huge benefits in sharing energy, innovation, collegiality…and a bit of smarts sprinkled in…all feelings of “fitting in” to a larger whole that HfS’s social networking scene has created. Having a voice, a collective platform, a safe environment, and a listening ear – with a global reach – is something that no other firm in our industry has been able to crack. The last time I looked, 37,000 others agreed and opted to sign on here!
You can ignore it, rebel against it, say you have no time for it, or think it’s just plain dumb. BUT…c’mon, the reality is that you can choose to either accept our pop culture reality and be part of a broader community than just your own, or you can run from it back to your nest. The data doesn’t lie, and it’s clear which industry stakeholders are struggling to reach their audiences, and those which are getting the message across. Clearly consultants and advisors, whom I have had extensive experience with during my career, need to do a much better job of educating both the IT and business buyer, when it comes to leading edge issues, such as the Cloud.
Yes, you can run and hide OR try to go it solo, but, at the end of the day, when you ask yourself “what did I do today to make the world a better place?” you ought to consider having tapped into a larger social network – at least once – to find the answer. I’ll bet once won’t be enough.
Lisa M. Ross is SVP, Market Development & Operations at HfS Research. You can reach her at lisa dot ross at hfsresearch dot com and Tweet her at @LisaRossHfS