Charles Sutherland is Chief Research Officer for HfS. (click for bio)
Amidst all the feverish talk of acquisitions and divestitures in the services industry of late, spare a thought for one dynamic service provider focusing its growth the organic way: Genpact. The business process service giant has been stealthily hiring talent left right and center in recent times – mainly from its competitors – as it sharpens its focus on operations services in the finance, procurement and supply chain business services markets.
And we’re impressed with its latest deal – the absorption of respected procurement consulting firm Strategic Sourcing Excellence (SSE), which propels Genpact’s procurement-as-a-service capability to the forefront of the market – at a time when procurement BPO decisions are increasingly being made by the CFO, which is where Genpact rules the roost. Hence a timely move and a smart play to really get to grips on this market. So who better than our own procurement guru, Charles Sutherland, to take a closer look at this integrative move and its impact on the global procurement-as-a-service market space…
Movin’ On Up In Procurement Outsourcing
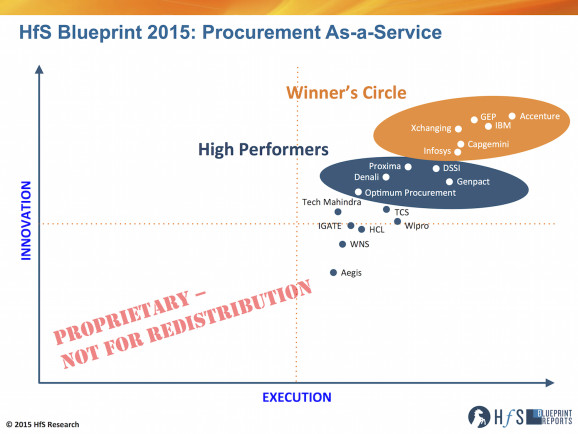
In June of 2015, we published our HfS Blueprint on Procurement As-a-Service which the continued evolution of this market around end to end and modular solutions enabled by cloud technologies and supported by ever deeper category management expertise. At that time, we placed Genpact as one of our “High Performers” with strengths in transactional procurement, process automation, geographic reach and a focus on continuous improvement. But we also felt that by comparison to the market leader Accenture, Genpact still had to further develop capabilities in category management, market intelligence and transformational procurement consulting to challenge for a leading position across the entire market.
We thought that Genpact would likely combine an inorganic acquisition strategy with organic activities such as the aggressive recruitment of category managers and rolling out new technology investment to make a push to move into our Procurement “Winner’s Circle” in 2016. And while we saw signs of the organic activities from Genpact in the 2H of 2015 as some of the other service providers stayed put, we kept waiting to see a coordinated inorganic play as well as 2015 came to a close.
So, now it’s here, the announcement that Genpact has pulled off a combined inorganic and organic play with the announcement of the integration of the transformational procurement consultancy of Strategic Sourcing Excellence (SSE) led by former Astra Zeneca CPO, Jon Kirby. Jon will be joining as the new lead for source to pay services within the CFO Services and Consulting Groups led by Shantanu Ghosh.
The Bottom Line: This may not be a “bet the farm” deal monetarily, but it does show Genpact’s determination to deliver transformational procurement and compete in the HfS “Winner’s Circle” in a market, where access to experienced talent is critical
As we have noted for the last several years, it’s a continuing struggle for all of the major procurement service providers to attract and retain sourcing and category management experts. It’s a “seller’s market for procurement buyers” if you will. Since consulting skills and category management talent are what is key to driving benefits for enterprise clients in procurement outsourcing, they have to be sourced. Hiring individual talent is a time consuming and risk strategy but it’s also easy to over-pay for talent in an acquisition who might not be properly incented to stick around after the deal is done. So there’s an inherent logic to buying just enough talent and leadership to then accelerate the effectiveness of the organic investments as well, which is what we believe Genpact has decided to do.
Genpact can make it into the HfS Winner’s Circle for Procurement As-a-Service in 2016 if Shantanu and Jon use this investment to enhance Genpact’s existing procurement capabilities in the following ways:
Drive the further adoption of As-a-Service solutions and commercial models and to move Genpact away from its historic focus in transactional procurement deals that were build around FTE or transaction based pricing alone.
Respond to the demand from clients for greater depth in category management (on-shore and off-shore) both in broad indirect categories of spend and in niche areas where the long tail of spend in a client creates cost and operating challenges today.
Retain the recent category talent and create momentum for new talent to pick Genpact (rather than other service providers) as a first choice for procurement career development
Reinforce the existing investments in spend analytics and operating insights with a greater business results orientation rather than performance management analytics alone.
Expand the investment in process automation and cognitive tools to replace human agent involvement in procurement processing as well as in sourcing and category management tasks.
Maintain the incumbent relationships for transformational consulting skills with third parties such as AT Kearney to supplement the still growing reach of the source to pay team inside Genpact.
Develop both end to end transformational consulting based solutions for enterprise clients in key verticals while also allowing clients to source more modular, technology and expertise based offerings as required.
The procurement outsourcing market is already one of the most “as-a-service” of markets today but it continues to evolve rapidly and in that time of change there is a real opportunity for change in the structure of the market leaders. The time is now in the adapted words of ‘70s TV character George Jefferson to be “…movin’ on up … to a deluxe position in the Winner’s Circle.. we finally got a piece of the pie”,
In November 2014, we released the industry’s Maturity Model for Robotic Process Automation deployments. The model provided a guide for what service providers and enterprise clients must do to become proficient and scaled in achieving the efficiency and cost benefits that this technology can provide in business processes and IT delivery.
Author of the RPA Maturity Model, Charles Sutherland, is Chief Research Officer at HfS (Click for bio)
Now Charles Sutherland has updated the RPA Maturity Model and has created a service provider-specific version. Soon he’ll publish a version specific to the enterprise environment as to highlight the differences but also to recognize some of the commonalities in strategy and operations between the two as well.
The RPA Maturity Model is designed around two different components. The first component is comprised of 17 elements, each of which covers different aspects of RPA strategy or RPA operations that have come out of the dozens and dozens of discussions, briefings and site visits over the last 3 years. The second component is the levels of RPA Maturity that can be used to assess comparative states of RPA maturity across the Elements.
There are now four Levels of RPA Maturity, three of which are uniquely defined based on the requirements of each of service providers and enterprises and one of which is a shared Level for the integration of RPA between service providers and enterprises across the same business and IT processes.
Following on from our recent discussion on Social Intelligence, I drew some real inspiration from this recent speech from Bollywood actor R. Madhavan, who touches on three critical elements for success (combined with your sheer determination to succeed and to seize opportunities):
Situational Awareness: Being completely aware of everything that is going on around you at all times;
Good Manners: Being courteous and pleasant at all times really helps makes the most out of opportunities when they come along;
Strong Communication: Being able to express your desires, capabilities and determination to be successful will help you maximize opportunities when they come knocking.
Unprecedented pressure being applied to operations leaders to drive more value, without huge investment increases, is forging a dire need for the vast majority of service buyers and their providers to change how they work together. The legacy model of “we pay, and you deliver for cheap and we don’t really want you getting involved with helping us do things better” has to change. Otherwise, enterprise leadership will find new service partners and operations heads to take them forward.
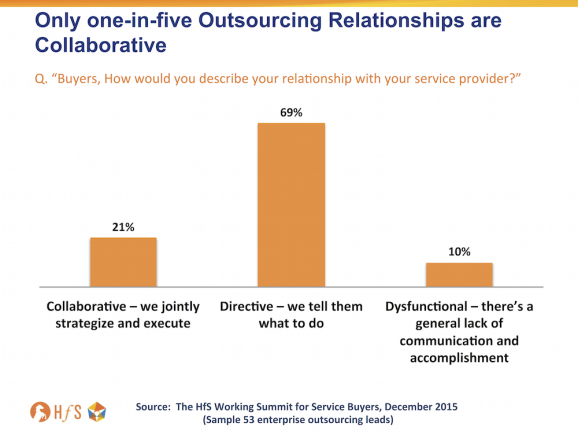
The simple fact that 80% of services buyers simply aren’t engaging with their providers in a collaborative way, as revealed at last month’s buyers working summit in Harvard, emphasizes how critical it is to infuse the methods of Design Thinking into most of today’s flagging engagements:
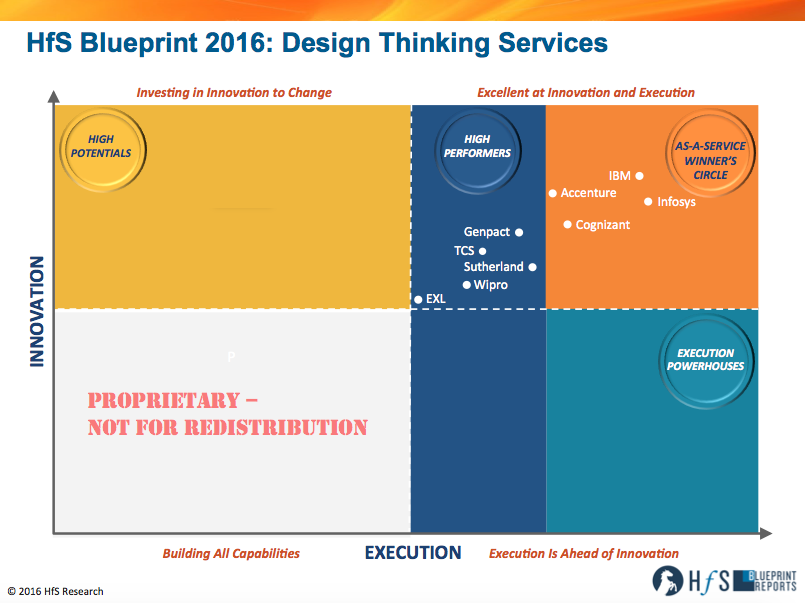
So we set out on a unique Blueprint research exercise, led by myself (Phil Fersht) and supported by HfS analyst Hema Santosh, where we interviewed a host of enterprise clients on their experiences with Design Thinking exercises with their service providers, using our new Blueprint Methodology to assess their innovation and execution performances. Many of these clients were not the usual rose-tinted reference clients heavily wined and dined by the providers – they were from the HfS buyer community, who could give us an unvarnished, honest appraisal of their Design Thinking exploits.
We focused on those leading service providers, currently involved with Design Thinking as a key component of their As-a-Service delivery model. While we acknowledge there are many design boutiques and consultancies out there, we specifically focused this Blueprint on the capabilities of the leading outsourcing service providers.
And this is how the emerging service provider landscape is taking shape:
Click to Enlarge
Phil, why is Design Thinking so relevant to the future of outsourcing?
Most of the outsourcing industry is still trying to figure out what’s possible beyond doing labor arbitrage really well – because that’s what we do. Sorry, but there I said it – we officially have an identity crisis.
We’re trying to forge a new identity for ourselves and re-imagine what our careers, our services and our platforms could be like if we only figured out how we can define, prioritize and realize business outcomes that are valuable, as opposed to merely keeping the same old factory ticking over at the lowest possible cost.
Digital technologies, robotics software, analytics tools, BPaaS platforms and artificial intelligence can only be effective and impactful once enterprises have re-designed their processes in a way that drives them towards their desired business outcomes. This has always been the case with (now legacy) ERP implementations, where thousands of clients have blown billions of dollars on enterprise software they simply never could mold effectively to their businesses. They weren’t finding problems to solve, they were creating new ones they didn’t need in the first place.
It’s the same with the next wave of As-a-Service solutions – they will fail without the right approach to designing processes that produce the desired results. In short, “As-a-Service” is about a business model transformation – and how it can be empowered by digital technology, made more effective and intelligent by automation and cognitive computing, made possible by smart change management and made trustable by proactive security deployment. Hence the need to design this seismic change, in terms of both talent and solutions, is what holds the keys to the promised kingdom.
Without Design Thinking, enterprises are really just retrofitting expensive solutions into legacy processes and likely wasting a whole load of time, resources and money. It all starts with Design Thinking.
Design Thinking, and new creations of Design Thinking-eque collaborative methods, are increasingly important ways to bring together new concepts and ideas, better teamwork, and ways to design outcomes jointly that can incorporate investments from both sides.
Design Thinking is helping several relationships inject lateral thinking and renewed motivation to work together, not only in the customer-facing front office, but also in the back office operational functions. Design Thinking in services is based, primarily, on both service buyer and provider coming together to create business outcomes that are mutually beneficial – and motivational – for both parties. However, this must be established as ongoing collaboration across all key relationship stakeholders, and not simply two days of senior management putting sticky notes on each others’ foreheads. There must be senior pressure and buy-in to adopt Design Thinking as a means to move away from Six Sigma-obsessed old world models, and really change the way the service buyer and provider teams work together.
What are you seeing on the service provider side for engaging with clients with a design mindset?
We’re seeing encouraging signs from several providers aggressively promoting Design Thinking techniques, such as our early leaders Infosys, IBM, Cognizant and Accenture (see above), into their engagements, but this is still restricted to far too few a number of buyers at this stage.
We have been impressed by the focus from Infosys, where their CEO has personally hired a team under Sanjay Rajagopalan to train all staff on Design Thinking methods and embed it into all RFPs over $50m in value and drive some significant engagements worldwide across both IT and business process areas. IBM has made significant investments in its global centers, with over 600 designers working in 20 schools worldwide and has engaged its entire leadership team in Design Thinking workshops internally. Cognizant impressed us greatly as a firm where a design mentality is native to its hyper-development and growth in recent years – and its determined focus on digital has Design Thinking at its core. Accenture has made recent investments to infuse Design Thinking into its engagements, which is a unique challenge for a firm that has evolved with a client/partner model, but we were, nevertheless, encouraged by the significant investments being set aside by its operations group, with specific focus from its strategy lead, Michael Corcoran, to As-a-Service model with a Design Thinking ethos.
We also saw determined efforts to develop a Design Thinking mindset from other leading service providers during our study, such as Genpact in F&A and its Lean Digital approach, which has a real tie-in to Design Thinking. Infusing design concepts into a function as slow-moving as F&A is challenging, but Genpact is one of the most proactive providers in the market in pushing its clients hard to re-imagine their finance and procurement processes to be more effective. Wipro‘s acquisition of Designit has advanced its Design Capabilities in digital areas and its new CEO, Abid Neemuchwala has come from a heritage of rethinking roles and capabilities from his time building up the TCS BPS business.
Sutherland Global Services‘ focus on providing Design Thinking engagements in marketing and customer support areas has been impressive, which includes two of the largest technology firms in the world. In addition, TCS has been pushing various flavors of Design Thinking for sometime, especially with financial services clients, while EXL‘s EXLerator framework incorporates elements of Design Thinking and promotes the mindset with its ambitious clients. Other providers we expect to see emerge in the future include Concentrix, an innovative leader in the contact center space and Capgemini, which is busily integrating its IGATE acquisition, but has some real potential, especially with its global process model and robotic process automation.
And where does Design Thinking fit into the As-a-Service continuum, Phil?
Being successful in the As-a-Service Economy requires ambitious service providers to make fundamental changes to their whole approach to service design and delivery. At the heart of this evolution, is a shift to service solutions being designed with real business context, as opposed to simply “looking at a process”. This involves a genuine focus on approaching and interpreting a client’s challenges, identifying and experimenting with opportunities, and ultimately evolving these approaches into the service delivery.
HfS believes that “traditional” capabilities, such as Six Sigma-based process design and execution, while essential to delivering the efficiency benefits of traditional sourcing, are today standard, commodity-based capabilities embedded into any standard service delivery model. We believe that a new Design Thinking methodology must be front-and-center that imbues the full spectrum of human-centric design ethos. HfS’ Design Thinking methodology is based upon a more responsive relationship between the service buyer and the provider, one that is open, empathetic, experimental and yet efficient.
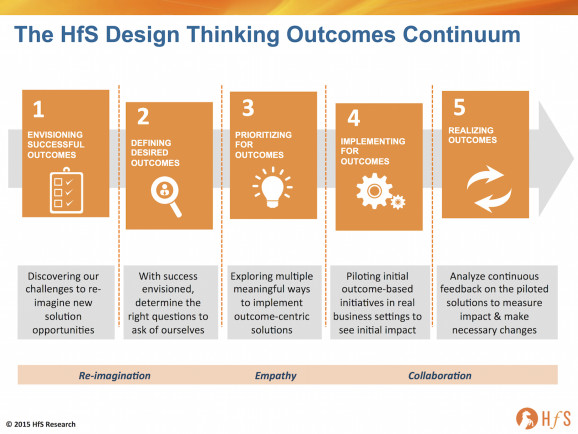
There is no one best way to apply Design Thinking, but there are useful starting points, and we believe the HfS Design Thinking for Outcomes Continuum to be a valuable and meaningful way to think about how to solve problems in designing services for the As-a-Service Economy:
We firmly believe 2016 to be the year in which Design Thinking comes to the forefront of the sourcing and services market. It will be the time during which service provider leadership teams are sent to design camps, and a whole new set of conferences and workshops feature Design Thinking as their theme of the moment. Some of that may be hype or even unnecessary, but at the root of it, the arrival of Design Thinking into the mainstream of the IT and BPO services world makes sense to us as a way to re-imagine more effective process-based solutions for this increasingly digitized As-a-Service world.
So what are the key takeaways you would like to leave people with, before they download the report?
Design Thinking for outcomes is a real methodology that enterprises can understand and embrace today, as opposed to five years’ time. However, while we believe Design Thinking will firmly take root in IT and business services in 2016 as a methodology to drive genuine collaboration and creative ideas, at the end of the day, it is still just another tool. What you make of it depends on the intent and practices of its users, whether individuals or organizations.
This approach will not be easy for some legacy service providers who cannot yet see how the world is changing – or can see it but are paralyzed to do anything about it. For those service providers and their enterprise clients which can see that thriving in the As-a-Service Economy requires new approaches and capabilities, we see a real potential to use Design Thinking in the move from the present into the future.
Getting new digital processes and services right from the perspective of their end users is critical, especially as this is really about a business model transformation that is enabled by digital technologies. Design Thinking, which is about context and empathy for the user, can facilitate this focus. It will be an integral part of the emerging As-a-Service provider offerings, many of whom are already rapidly emerging to redefine the market.
This company may have its digital transformation strategy spot-on, but it could definitely benefit from some Design Thinking to maximize its brand opportunities and re-imagine its customer experience:
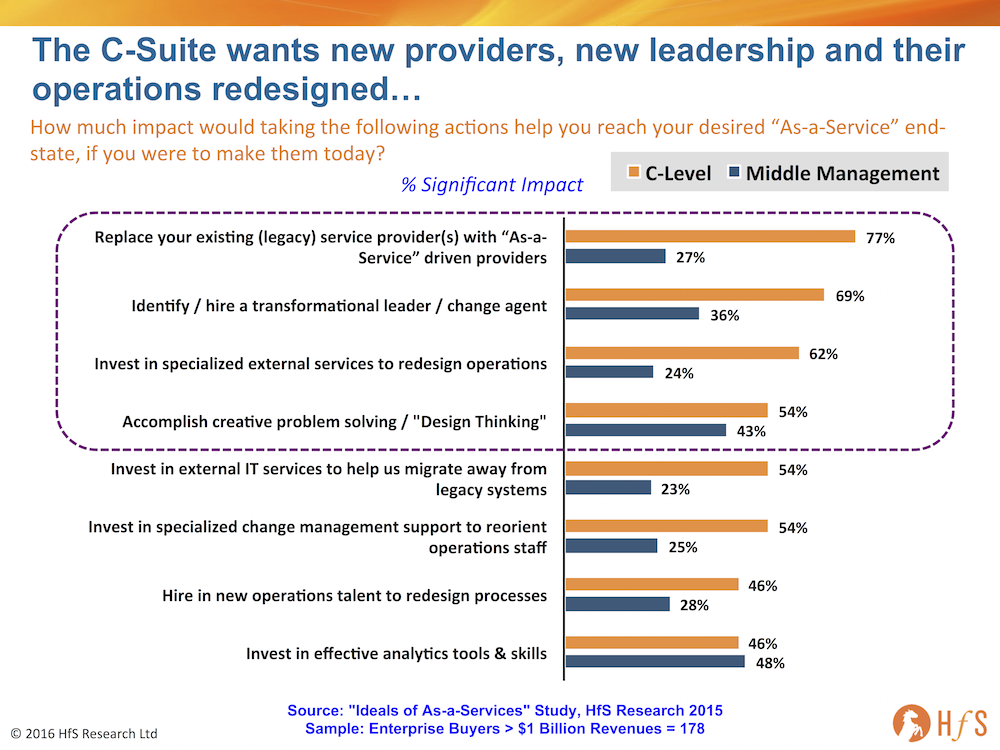
Revisiting our As-a-Service study from late last year (click here to download your copy if you somehow missed it), we realized 10% of the respondents were in C-level positions. So we thought it worth comparing the C-Suite’s views on what would significantly impact their firm’s As-a-Service journey, when compared to their middle-management layer:
Click to Enlarge
Provider-replacement therapy popular among three-quarters of the C-Suite. A staggering 77% of leadership want to see their legacy service providers replaced, compared with only 27% of their middle management. This is because corporate leaders have reaped the labor arbitrage fruits from legacy outsourcing, and know their middle layer is getting fat-and-happy meeting their SLAs and performance metrics. Nothing will change without forcing the issue – the incumbent provider has little interest reducing the predictable headcount-based revenue it is serving up, and automation threatens both the provider’s margins and the middle management’s job security. Ripping out the legacy is the only sure-fire cure to breaking the inertia cycle. Provider-replacement therapy worked when the C-Suite demanded the expensive ITOs were kicked out for the hungry India-centric providers (remember all that fuss the fat-and-fluffy middle then made about the perils of offshoring). Now, the C-Suite wants to replace this new legacy with automation-driven service solutions. This is a continuous cycle of cost take-out and better effectiveness and now we’re onto the next wave….The As-a-Service Economy.
The C-Suite want to bring in transformational leadership to be the change agent to redesign their operations. Clearly, the C-Suite recognize the inertia below them, with close to seven-out-of-ten strongly believing that appointing a transformational leader would have a significant impact. Only 36% of the middle later believe that bringing in someone to shake things up would have a real impact on their enterprise… they probably think they are already doing a great job and some big swinging exec wielding a Harvard MBA would fail to get into the real weeds of their operations.
Outsourcing is very much the direction the C-Suite wants to take to do the redesigning. 62% see a genuine need to bring in external specialists to redesign their operations, compared to only 24% of their middle layer. Clearly, leadership realizes their existing team just doesn’t have what it takes to do much more than keep the same old widgets turning. Hiring external help to force the change-cycle is clearly the path most companies are going to take. This is great news for service providers geared up to deliver As-a-Service capability, which have the desire – and investment chops – to hijack legacy deals from legacy competitors upon re-bid.
Both C-Suite and middle management view Design Thinking as a powerful method to drive creative change. This is the one area where both camps are in alignment, with roughly half seeing Design Thinking as having a significant impact. This is because Design Thinking is a collaborative vehicle and most people, believe it or not, actually like to collaborate to get things done better. Design Thinking provides a mechanism to drive creative problem solving (and problem finding), and the more this is embedded into service engagements, the more it involves both leadership and middle management, the more impactful it will be. Expect to see the Design Thinking paradigm grow in traction and momentum over the course of this year.
The Bottom-Line: We’re in a new services cycle, where it’s now time for the C-Suite to step back in to broker that next wave of services transformation
What’s startlingly apparent, is that the C-Suite is clearly ready to make real impactful changes to their organizations to drive out more cost and really look to design their business operations more intelligently. It’s also very obvious that most know they can’t change what they have with their current middle layer and legacy service provider relationships. The only way to do this is to entertain competitive rebids that are radical – and include real change parameters, such as an effective Robotic Process Automation strategy, a genuine focus on self-learning and Cognitive Computing and to leverage Design Thinking to understand truly how business models can be transformed to take advantage of Digital technologies.
People often complain the C-Suite only get involved when deals are brokered and then they retreat to let their middle management run the operations… well, people, now is the time for the C-Suite to step back in to broker than next wave of services transformation.
Derk Erbé is Research Managing Director covering Digital Business Transformation and Energy, Utilities and Resource Industries for HfS (click for bio)
You may have noticed we’ve been doing a little expansion at HfS recently… And a big part of this was building out our European presence and adding more industries to our research coverage.
One industry we’ve always been passionate about is energy, and how that sector is dealing with huge regulatory impact post the Paris Climate Agreement – where both energy providers need to rip up their operating models to survive, and enterprise energy consumers can take advantage of new sources of renewable energy to gain a competitive edge.
So who better than to hire an Amsterdam-based energy expert with a penchant for technology and research? So without further ado, let’s introduce you to our new Managing Director for Research, Derk Erbé…
Welcome, Derk! Can you share a little about your background and why you have chosen research as your career path?
Thanks for the warm welcome. I’m very excited about joining HfS. I feel research, and the role of the industry analyst brings everything I experienced in my career and found to be critical together. I have been in the trenches of technology implementations, business transformations and operating model changes. I’ve managed the backlash of failed implementations on the business, designed business and IT functions. And last but not least, I founded and ran a business, Kea Company. Helping vendors with Analyst Relations, I’ve been on the other side of the table with analysts for years.
As a sociologist, I have an interest in the change management side of transformations. And in the human condition, something we can’t escape from.
As an analyst, I’m able create a helicopter view perspective and dive deep into trends, hypes and powerful forces of change. I love poking around at the underlying dynamics of the things we see happening around us.
Why did you choose to join HfS… and why now?
It feels like the right time and the right place. Analysts are here to find new truths and help buyers and providers of technology and services make sense of the world around them—help them to make the best possible buying decisions. In my years at Kea Company, I have built a deep understanding of the analyst world and the way analyst services are consumed and valued. Not every analyst firm is as forward looking, but in my opinion, this is a critical component of value and purpose.
I have gotten to know HfS as a company that always pushes the agenda and is not afraid to go against the grain. This is what I admired and a big reason for me to join.
Technology and internet services touch so many lives in a positive way. But let’s not forget the darker sides. A deep understanding of both is required to navigate this Technology Revolution, or rather Internet Revolution—the Industrial Revolution was a de facto Technology Revolution as well, of course. In my opinion analysts should play a significant role.
What are the topics and big issues that you will focus on in your analyst role?
My focus is on three big topics. The first is digital. Digital is all around us. A big part of the current disruptions in industries are fuelled by digital technologies. But as every vendor and service provider has a digital transformation story, change is hard, especially if there is a lot to change. So big enterprises have a mountain to climb regarding the adaptation to the digital opportunities and threats. New business models will be born, will envelop or replace old business models, and will challenge the position of incumbents.
I’m fascinated by the strategies, business models and business transformations technologies that cloud, mobile, social and big data analytics have enabled. And it is even more stunning how fast people adapt to this new reality, the new opportunities. Although I have a ton of grey hair, I’m not very old, but I grew up with an old-school telephone in the house, one with a wire and a horn. I see people I never expected to adopt new technology quickly—my parents for example—using Skype, emailing, texting like they’ve been doing it for ages. And on the other side of the spectrum, my 4-year-old son is so savvy and intuitive with technology he probably will never understand the world of just 15 years ago. I see an analogy to “born in the cloud” enterprises and older firms that have their roots in a pre-Internet era.
The second focus is on Energy, Utilities and Natural Resources. This is an industry on the brink of a revolution. We need to change our production and consumption of energy dramatically. Energy companies and their service providers are at the center of this process. And they need help. HfS is expanding the coverage of these industries to be a source of dependable knowledge and insight to energy companies and the service providers.
My third focus will be on custom research projects. The syndicated research agenda of a firm says a lot about its ability to provide guidance to clients about current and future business challenges. For instance, the moment HfS called the As-a-Service Economy shift I knew this was going to be an incredibly powerful framework for enterprises and service providers to guide their journey for the coming decade.
The custom research is a way to push the agenda even more. Clients want to find out how they can find competitive advantage, make the next big thing. Custom research projects are an excellent way to explore the new frontiers. It is a method for HfS and our clients to keep sharpening the axe. I’m excited to contribute to this. And get stuff done.
And what disruptive trends and developments are capturing your attention today—especially with the impact of Digital technology on industries such as energy?
I see a role for all eight ideals of the As-a-Service Economy in the energy transition journey. Many service buyers are still looking around and figuring out what the hell is going on. While the Solution Ideals hold the real promise, the Change Management Ideals can help energy providers and service providers cope in the shorter term. So the ideals that are closest to home in the coming period are Design Thinking, Writing off legacy, Brokers of Capability and Collaborative Engagement.
Digital technologies will be useful in finding answers for disrupting challenges from non-digital forces. Energy providers have to deal with a lot. The plunge in oil prices means oil producers are operating at a loss. The looming departure from fossil fuels will mean finding investments in non-renewable energy becomes next to impossible. I’m carefully looking at whether energy providers and service providers can find each other in collaborative engagements, co-investing in As-a-Service-based platforms that enable new operating models and business models, creating new value.
And what are you working on first for our clients, Derk? Any sneak previews into what we can expect?
I started of with a Point of View about the Paris climate agreement and its impact on energy providers, operating models getting ripped to shreds. This piece is setting the scene for our research in the Energy, Utilities and Natural Resources vertical, such as a new Blueprint Report on Energy Operations. Next month, we will write a Point of View on the top industry processes that are impacted by Digital transformation and the move to As-a-Service.
Welcome to HfS, Derk. We’re delighted you have chosen HfS as your analytical home and can’t wait to see you first Soundbites hit the presses =)
You can reach Derk by email here and follow him on twitter here.


 Revisiting our As-a-Service study from late last year (