Zach Nelson, CEO of NetSuite, a.k.a The Admiral of Cloud BPO
“First gain the victory, and then make the best use of it you can.” Admiral Horatio Nelson, before the Battle of the Nile, 1st August, 1797
“The cost of managing IT infrastructure is four to five, or even ten times the license cost. It’s enormous. We’ve eliminated all the cost to manage this stuff, so that’s a huge advantage for BPOs.” Zach Nelson, CEO of NetSuite, before the Battle of Cloud BPO, 25th May, 2010
So without further ado, let’s do Part II…
Phil Fersht: Zach, there’s been a lot of talk in our industry around business-process-as-a-service, or business as a utility, with an entire business process being accessed by a pay-by-the-drink model, hosted in the cloud. How do you see BPO, SaaS and cloud all coming together? Is it going to be a reality?
Zach Nelson:I don’t think there is any question that service providers will have to move their infrastructure into the cloud just as end users are starting to do. There’s no stopping it from a cost and productivity standpoint. Also – and what I believe is really driving this revolution in how IT services are delivered – is that customers are demanding it. So the Tata’s of the world and the people that are really tied to the SAP boat-anchor will begin to acknowledge that even though they have a lot of business with SAP, the customer wants a cost reduced environment, and something that is faster to deploy, SAP is a bad answer, and they have to transition their business model. We all saw IT budgets shrink during the downturn, and more was spent on the Cloud because of the cost reduction capabilities. Now the Genie is out of the bottle, they saw the benefit they got from the Cloud, so the Genie isn’t going back into the bottle. The customers are beginning to demand services like what Genpact and NetSuite are aligning to provide. That’s the shift you see going on now.
Phil Fersht: We’ve seen a lot of SaaS/BPO partnerships spring up in the last year, but some of them just don’t make sense. We’ve seen, for example, some providers partner with PeopleSoft to deliver it in some form of pay-by-the-drink environment, but it simply doesn’t work because getting to multi-tenant scenario with PeoplSoft is just too challenging. What makes your partnership with Genpact a game-changer?
Zach Nelson:Our model is very different than theirs. We are effectively replacing an on-premises instance of Oracle or SAP with a BPO-enabled offsite version of NetSuite. This is a new and different way to replace those Stone Age on-premises applications.
The reason the other model doesn’t work is that it’s the same model that failed in 1998. You take an application that wasn’t designed to be hosted or managed in a hosted environment and you do it anyway. It’s just too expensive. So you’re just shifting all that from the customer’s premise to the provider’s premise, and now the provider has to deal with the cost. It doesn’t go away. And as you know, the cost of managing IT infrastructure is four to five or even ten times the license cost. It’s enormous. We’ve eliminated all the cost to manage this stuff, so that’s a huge advantage for BPOs.
And from the customer’s standpoint – the challenge with serving the mid-market is how to deliver SAP-like complex functionality with a few zeros missing off the purchase order. We figured out how to do that, and we’re transferring that knowledge to Genpact so they can deliver the same sort of efficient, streamlined implementation that we’re delivering to our customers. That’s a very important part of the equation. By transferring that knowledge, Genpact can take it to the next step of adding BPO capabilities on top of NetSuite.
I can’t really envision a future where this isn’t the dominant way BPO is done, but the legacy approaches and legacy relationships definitely hamper the rate at which this stuff is being taken up by clients. Now with that said, a client that Genpact enables on NetSuite with their business process knowledge built on top of it, will have a mass advantage over someone, such as Tata, may implement with the same old SAP methodology. The cost model will be completely different, the productivity model will be completely different. So what you’ll see is the companies moving to Genpact will have an enormous competitive advantage over their competitors that are stuck in the traditional outsourcing model, and that could accelerate the way in which companies demand a solution that looks more like Genpact’s.
Phil Fersht:One of the biggest issues we’ve seen with the software-to-market channel has been with the value added resellers which see BPO as a threat to their business, where they make all their money supporting finance applications, etc. Are you seeing this dynamic in play where the VARS are very nervous about the BPOs coming into their domain? Is this something you think is going to be a conflict, and will it impact your relationship with the VARs with whom you work?
Zach Nelson:The VARs we deal with are not that worried about it, because most BPOs have not moved down market to the point where they threaten that classic mid-market VAR. Now, with Genpact’s strategy, that collision may happen at some point. But this sort of mid-market VAR spans a 10- person company to maybe a 1,000 person company, so you’re talking about a big market there.
I think the mid-market VAR is more concerned with two things: first is how they make money in the Cloud, and second is who the new competition in the Cloud for that dollar. What they are looking at, is how they transform their model from this on-premise, one-time license to this new sort of recurring revenue model. That’s their big issue today. And we’ve put together a number of programs that assuage that part of the equation so they can first make the transition and then worry about who they compete with.
Phil Fersht: Zach, it’s been a real treat to have you guest on Horses for Sources – our readers will really enjoy hearing your story.
Zach Nelson (pictured above) is President and Chief Executive Officer for NetSuite with more than 20 years of leadership experience in the high-tech industry, where he has held a variety of executive positions with leading companies such as Oracle, Sun Microsystems, and McAfee/Network Associates. Zach has been CEO of NetSuite since 2002. One of top 10 visionary CEOs in the Silicon Valley, he led NetSuite’s successful IPO in 2007.
43% of decision-makers now see it as a critical element of BPO
Half of today’s enterprise buyers are disappointed with the innovation they have currently achieved
The potential to achieve innovation across many core business processes is huge. This was notably cited in industry-specific process and analytics areas, in addition to some maturing BPO domains, namely procure-to-pay, supply chain and recruitment
So why aren’t half of today’s enterprise buyers achieving innovation?
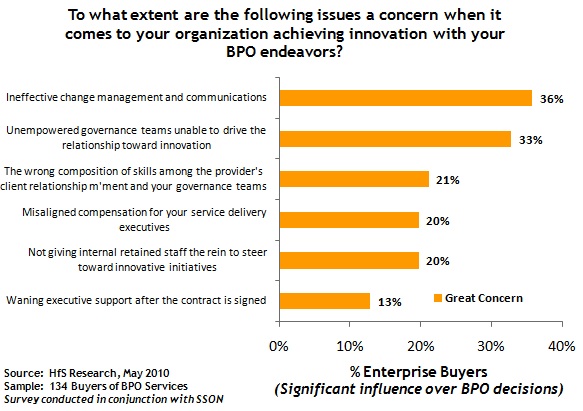
When we asked those executives with significant influence over BPO decisions their prime concerns for failing to achieve innovation in BPO, they cited the following reasons:
It is abundantly clear that enterprises buyers recognize that the blame lies a lot more in their camp than their provider’s, with well over a third citing poor change management and communications as a great concern, coupled with the fact that their current governance team has little juice internally to drive an innovation agenda. If they were going to blame primarily their provider’s lack of innovation prowess, much more than a fifth of buyers would have cited “the wrong composition of skills among their governance team and the provider’s relationship team” as a major concern.
In the next installment of this innovation saga, we will reveal what buyers are planning to do to achieve innovation, but here are a few clear areas they can work on:
Create a aggressive innovation agenda and a plan to keep that agenda fresh over time. Buyers need to stipulate the need to explore new and creative ways to improve productivity and top-line growth as a core element of their BPO endeavor and communicate this aggressively, on a repeated basis, to their entire retained operations organization.
Communicate this innovation agenda to both governance and provider teams. Talk to any buyer beginning to achieve some innovation success with their engagement, and they will tell you the same thing: “We recognized what we needed to do internally, and communicated aggressively with our provider to start delivering it with us”. Until buyers take the bull by the horns internally and communicate to their partners the new direction they are taking, they will never escape from innovation purgatory.
Create an innovative contract with their provider. Buyers need to incentivize their provider financially to help them achieve gains in both productivity and growth. This is already beginning to happen with several recent BPO engagements, where the provider has demonstrated the confidence to insert productivity incentives as high as 20% in some of today’s recent contracts. Providers will step up to the plate with the right approach, if they have the financial incentive to do so.
Stop playing providers off in a low-cost bake-off. If the buyer simply squeezes the life out of their provider with a cost bake-off, they are unlikely to get much in return beyond operational delivery to meet the contracted service levels. Some of the leading BPO providers are now inserting gain-sharing elements into their deals in order to beat off competitors dropping their prices, because it is desperate to win the deal. The better providers now have the advantage of knowing where they can offer innovation incentives to gain ground in tough pursuits. In any case, most of the providers are now operating within a similar price band, so focus needs to move away from simply price, and more to which ones are better prepared to be incentivized financially for driving innovative results.
All-in-all, we are encouraged that many enterprise buyers have recognized the need to get their act together and start driving the innovation agenda. The future for innovation is bright, and many of today’s enteprises are figuring out how to make some progress towards it.
*For the purposes of this study, Innovation was defined as “the customer going beyond transactional / operational work to achieve new productivity gains and /or new revenue streams by implementing new practices through unique, creative methods.”
Aside from airline strikes, ash clouds, oil leaks and Sarah Palin’s plea to “drill baby drill” (what a brilliant faux pas that was), global media attention was briefly diverted to Edinburgh, last week, as some of BPO’s top buyers and providers bravely duked it out under the lilac-neon lighting at SSON’s European Shared Services & Outsourcing Week.
The occasion was the “Thundering Hooves”, where HfS nervously stood between two aggressive teams of buyers and providers eager to prove they could thunder more thunderously. Moreover, with the incentive of a coach-class ticket to tour WNS’ facility in Mumbai, with only a 20 hour-layover in Nairobi and Dakkar (industrial action and political unrest permitting), the tension was akin to a frenzied iPad queue with fast-depleting inventory.
The thundering victorious "Buy Family" (pictured left-to-right): Graham Russell (Astrazeneca), Simon Newton (KimberlyClark) and John Transier (Unilever)
The deliberations began well for the Sell Family, comprised of Genpact’s Smooth Operating Officer Tiger Tyagarajan, WNS’s Chief Mischief Officer, Deborah Kops, and PA Consulting’s Huw Grant-Watkin. Could they come back after their catastrophe in Orlando in February? The vast crowd watched on with baited breath (it had to be with all the haggis and smoked-salmon vol-au-vents floating around) as they second-guessed how hundreds of shared services and outsourcing executives answered the following questions:
The Buy Family: What phrase from your service provider makes your blood boil the MOST?
The Sell Family: What phrase from your clients makes your blood boil the MOST?
The Buy Family: How important is achieving innovation from your service provider in BPO engagements to your operational leadership?
The Sell Family: How much importance are your clients placing on achieving innovation in their engagements beyond cost-reduction?
The Buy Family: To what extent has your primary BPO service provider met your expectations with its provision of quality resources (i.e. personnel and technology) to your current engagement to help you achieve innovation?
The Sell Family: To what extent has your primary BPO client / clients met your expectations with their provision of quality personnel and resources to help them achieve innovation?
It looked like the Buy Family, comprised of the global finance shared services and sourcing leads from Astrazeneca (Graham Russell), KimberlyClark (Simon Newton) and Unilever (John Transier) were struggling to recover from the previous evening’s deluge of bagpipes and sourcing advisors. However, they dug-deep through the cerebral fog and summoned up the inspiration to take the fight back to the Sell Family, by pulling level on points after the remaining questions:
The Buy Family: What is the primary reason your provider thinks is preventing you from achieving innovation?
The Sell Family: What is the primary reason your clients thinks is preventing them from achieving innovation?
To both Families: Which outsourced business processes have the most innovation potential over the next 24 months beyond standard operational delivery?
To both Families: What attributes are enterprises looking for these days when selecting a BPO provider?
The Buy Family: What is the worst clause in your contract?
The Sell Family: What clauses do you hate the MOST among your clients’ contracts?
To both Families: Where can we honestly go for IMPARTIAL, UNBIASED, UNFETTERED, and BALANCED advice?
So it all boiled down to a tie-break question:
Who announced their acquisition of ExcellerateHRO today?
“ACS!” buzzes Deborah Kops. Realizing she’d forgotten to name ACS’ new owner, John Transier, (quicker on the buzzer than a British Airways cabin staffer at an any excuse to take another month off despite the fact we already earn twice what our competitors get paid meeting), added “Xerox”. With this sudden-death deft play it was all over… the Buy Family had, once again, prevailed to thunder over its providers. We did try and get John to comment on how he was celebrating the victory, but a Nigerian prison warden explained he was currently indisposed…
The not-so-thundering Sell Family (pictured left-to-right): Deborah Kops (WNS), Huw Watkin (PA Consulting) and NV 'Tiger' Tyagarajan (Genpact)
It's a Thundering Family Affair, with your hosts (left-to-right): Phil Fersht and Lee Coutler from Horses for Sources
If anyone had told you a few years ago that Wipro would have a market cap of more than $30bn, you would have made a few discreet calls to their doctor, or perhaps their math teacher.
But today, the Bangalore-headquartered firm has firmly shed the tag of That Indian IT firm which makes the vegetable oil, to become a genuine leading global IT services and BPO enterprise, with 105,000 employees. And Wipro has not only become a tough top tier IT services competitor, but it also firmly holds its own in the BPO industry, with some landmark client wins in finance/accounting, HR and procurement/supply chain services, in recent times. The firm loves the process work and getting down to the minutia with its clients – just take a few visits to its delivery centers and you will see metrics you never thought existed.
So when we launched our recent series of Sourcing CEO discussions(more to follow folks), Wipro was on the first round of invitations, and we are flattered that Suresh Vaswani dragged himself away from his beloved TelePresence unit to spend a few minutes talking to us about how the firm has come through the tough times, and what are the plans for the future…
Phil Fersht: Good evening, Suresh, and thanks for your time today. How did Wipro tackle the recession when it first hit, and what measures were taken to ensure it came through the worst times?
Suresh Vaswani: There is always an opportunity in an adversity, the recession provided us with an opportunity to work closely with the clients. We anticipated the slowdown early, with first signs of the impending slow down coming from our Infrastructure business, much before we saw the impact on our IT business. We used this early warning to improve our operations and gear up for slow down and invested in solutions which were relevant to our clients as they looked at minimizing their operating and capital expenses.
The economic crisis called for strategies which could counter the negative effects of the slowdown to get businesses back on track. The challenge is in knowing how to be effective, ascertaining the future of business, learning to thrive under pressure, using techniques to motivate and promote innovation and employing innovative technologies or services to stay competitive.
We invested in Non Linearityand this is a huge movement within the organization and we are driving this initiative across the organization within Delivery as well on the Revenue side. We have created several tools, like Cigma, a tool for Business KPI measurement across application and BPO or in Productized services like the Cloud based mortgage loan origination system.
In difficult times it is even more important to understand the customer challenge and priorities. We put in place a team of people who understood the local market and most importantly the customer better. We are thrilled at the results of this move and continue to further expand this. Today, 56% of our sales force in US and Europe is local.
Phil Fersht: How has Wipro emerged as a company? Is the culture any different? What lessons were learned and what’s the company doing differently as a result with your people and your overall strategy?
Suresh Vaswani: We have emerged stronger than before, confident of our investments in the last two years, ready to reap the benefits of these decisions. Over the last two years we have invested in new technologies that may define the future of IT industry. These are Cloud, Collaboration, Green Technologies, Mobility Force, Social Technologies, Information management and Security.
As we emerge from the recession we are clearly focused on going up higher-up the value chain through our acquisition of domain competency and consulting capabilities. This approach is helping us address and transform customer business processes.
Our strategy now is centered on addressing the needs of the 21st century Corporation. Our view of the 21st century corporation is an organization that is taking a detailed look at core and non-core processes and is working towards value chain models where it optimizes what it does best and partners for the rest. The 21st Century Corporation model provides a roadmap to improve our clients’ speed, productivity, flexibility and financial performance. This model mandates that partners working as part of a customer’s value chain would have the business imperative to drive higher productivity and flexibility in the non-core processes and some core processes.
While we are moving up the value chain, we are also simplifying the ‘run the engine’ work we do by automating several tasks and de-skilling these tasks. These moves impact our people mix. On one side we are hiring extremely talented, high end specialized resources and on the other hand we are working out ways to deploy non engineers for many of the lesser complex tasks. This has impact on our recruitment, training and talent engagement processes.
Phil Fersht: From your perspective, how is the IT-BPO industry different today than it was prior to the downturn and how is Wipro adapting? Where do you see continuing challenges, and what do you see as the prime opportunities for the firm, where you are making your future investments?
Suresh Vaswani: The first 12 months of the downturn clients focused hard to driving down cost. Over the last 6-12 months we are seeing clients make more fundamental shifts to their products and business processes to drastically improve their agility, flexibility and cost variability. When clients do this invariably, they have to look at BPO and IT together. This is the same transformation we have undergone in our go-to-market strategy over the last 18 months.
We have integrated the BPO and IT value proposition, taking a process transformation approach. Given the fact that we are one of the leaders in BPO and have the whole stack of IT, we are in a unique position to deliver that sort of transformation to customers. Our joint HR platform solution (with Oracle, Hackett) simPlify, is delivered on a Software-as-a Service (SAAS) model allowing employers to pay for what they use and reduce complexity, time and investment. Wipro’s next generation service management platform, Cigma, enables the integration of BPO, IT and Device Management Services. Cigma enables customers to manage IT outsourcing engagements through business linked KPI’s.
Clients are now more comfortable with outcome-based contracts, making the non-linearity model stronger. The aim is to double fixed, outcome-based, kind of revenues in the next 12-18 months. Consulting, more than a role of advisory, is giving us downstream revenue. While it’s only about 4% of our topline business, its downstream contribution will be three or four times that.
Our strategy going forward is to invest in our large accounts, is to invest in our growth accounts and when I say invest, we are talking about strong client engagement investments, strong business advisory and consulting investments, co-innovation with them in terms of driving some transformation and the cost structure and the business models.
Long story short, the economy is slowly recovering, Customers have decided to move on, to make the investments, to build their future based on the new reality. Wipro’s opportunity is in delivering lasting value by being a transformation agent and virtual corporation partner of discerning clients worldwide.
Phil Fersht: And finally, what is your advice for today’s young practitioners in the sourcing industry? If you were to start all over again in this business in today’s environment, would you do anything different?
Suresh Vaswani: Young professionals in the sourcing industry should look beyond rates and start thinking about value and the Total Cost of Ownership (TCO). They should build a strong understanding of Business KPIs, Outcome based models. Risk Management frameworks and Governance should be high on the agenda too.
Phil Fersht: Suresh, we thank you so much for your time, at Horses. Our readers will appreciate reading your views.
Suresh Vaswani (pictured top right), is Chief Executive Office of Wipro technologies. He jointly carries the overall responsibility for the strategy and business operations of Wipro’s IT Business. Suresh has been with Wipro for more than 24 years in various leadership positions across differentiated IT Services and has provided a strong platform for growth and leadership in emerging markets for Wipro. He is very passionate about the themes of ‘Green’ and ‘Diversity’ and is the executive sponsor for gender diversity at Wipro. Suresh is married to Sonia and they have two sons. You can also follow him on twitter @sureshvaswani
It can't be… surely not… is that… is that… innovation?
We get some great emailed contributions over here, and “Sumitb” (remaining anonymous for fear of a lynching from the marketing police) has a great perspecitve on some of the realities of today.
While I agree his educated viewpoint represents many of the the realities of today’s innovation “issues”, I do believe our new data reflects operational leaderships’ increasing onus on delivering new and creative ways to find value. The focus on innovation is starting to shift – and shift quickly. Anyway, here’s Sumitb’s viewpoint:
Innovation in BPO is more of a must-have cliché that features prominently in corporate presentations and RFP prefaces rather than as a delivered reality which significantly impacts business performance.
And the reason for this is easy to figure, but hard to fathom:
Neither the Client nor the Service Provider really wants it!
From a client perspective Innovation is fine providing:
a. It’s the Service Provider’s dime and time
AND
b. it delivers the gain without any major internal pain in terms of change management
From a Service Provider perspective, to paraphrase ‘Me and Bobby McGee’:
‘Innovation’s just another word for something left to lose’ since usually the second or third word after ‘Innovation’ in a BPO contract is the dreaded word ‘reduction’
Enlightened clients have often asked me why as a BPO Service Provider I would drive Innovation if meant reduction of future revenues. At this point, I usually assume a beatific expression of sublime bliss and reverently chant the mantra: Gain-share…Gain-share
Unfortunately – like a lot of mantras – Gain-share ain’t the cure it’s cracked up to be because:
a. The Gain is often difficult to identify and measure in terms of realized business value
OR
b. The outcome of the Innovation often does not result in a tangible business gain – a classic example is improvements in C-SAT often do not correlate to Churn/Conversion/Wallet-share.
It is not surprising that Innovation is becoming the major differentiator for the first time BPO buyer not only because he can select proven BPO innovators but more importantly because he is may be inadequately aware of the real implications of the 3 C’s of Innovation: Collaboration – Co-investment – Change Management.
Even today, BPO is perceived as an answer to a problem rather than a solution for a business objective –i.e. reactive and tactical rather than proactive and strategic. Consequently, the selected Service Provider is perceived as a provider of services rather than a co-owner of defined business objectives.
It is this set of initial perceptions that shape the structure and remit of the engagement governance as well as tone and tenor of the relationship between the Client and the Service Provider. Consequently the subsequent value delivery – or the lack of it – in terms of measureable business impact and results is almost a self-fulfilling prophecy.
Bottom line is Innovation is like the Tango – it takes Two.
It can't be… surely not… is that… is that… a proactive bill that encourages businesses to invest in the US?
When is comes to “bringing US jobs back onshore”, we repeatedly seem to get all sorts of legislation that, quite simply, is focused on restricting our busineses’ competitiveness, when we should be looking at helping them invest in new talent and entrepreneurship, rather than penalizing them for trying to be competitive in today’s global environment. (Read our excellent discussion from last year: Who’s looking out for the US business these days?)
Senator Charles Schumer’s proposed new legislation, if passed, would tax U.S. companies that transfer domestic calls (at $.0.25 per call) to foreign call centers and require consumers be informed when their call is transferred outside the U.S. I assume by now most of you know the details of this, so let’s consider what good this does US businesses and the US economy:
1) The cost differential is not enough to warrant routing call center work back onshore. If the offshore call center is charging $18.00 per hour for each agent, who takes, on average, 20 calls per hour, this only knocks their costs up to $23.00 per agent/hour. A US domestic call center would likely charge clients $30 per agent/hour (or higher), so the cost differential still doesn’t warrant pulling the work back. Conversely, offshore providers are more nimble with price flexibility and can easily squeeze rates down if this became an issue. Benefit to US businesses: none, simply higher taxes. Benefit to US economy: additional tax income, but less competitive businesses.
2) There are an estimated 31 million business in the US, according to the latest government stats… er… that’s quite a lot of administration needed? Even the smallest of firms often use offshore call center support. The administrative organization needed to manage and audit this number of businesses to ensure compliance would be massive. You are talking multiple millions of dollars in investment that would likely struggle to be offset by the resulting tax returns. Benefit to US economy: none, simply government money wasted on bureaucracy.
3) Customers will be informed where their call is being taken, which will create negative overtones for businesses. This is probably the only “effective” component of this legislation, solely based on the fact it will educate the US masses that offshore workers are more competitive that they are, and run most of the call center work these days. However, what good will this do beyond stir up anti-offshoring attitudes? Yes, it may encourage a small proportion of businesses to move their work to US call centers, but if all calls are revealing the location, it will simply become an expected procedure and quickly lose its impact (such as the adverse side-effects warnings after pharmaceutical products commercials). Benefit to US economy: none, simply the creation of negative overtones towards companies offshoring.
4) US call centers are very good and becoming increasingly competitive. The Recession has only helped US call centers, with a lot more work being moved to centers in locations such as North Dakota, Michigan and Nebraska. Why not use some of this cash to give the US call centers tax-breaks to be more price-competitive, than penalize the offshore centers? Heaven forbid, why not support new center development in US locations? Benefit to US cell centers: a little more clout and a little more price competitiveness, but likely to be minimal overall.
5) Large enterprises may simply route calls to their offshore captives. Most mid-to-large US enterprises can simply shift call center work back inhouse and run from their own offshore/nearshore locations. Benefit to US economy: none.
6) This legislation also raises the potential of retaliation from other countries, under the recent Uruguay Round of WTO Agreements. Taxing international calls and not taxing domestic calls is a form of discrimination against foreign call center service providers that violates the basic principle of “national treatment”, with the exception of specific situations, such as national security, the environment, local labor, police, etc. Benefit to US economy: zero, and potentially negative.
All-in-all this legislation is reactive, not proactive. The old days of outsourcing backlashes are well and truly over. It’s clear that the way forward is to make the US an attractive location for call center, and other commonly outsourced work-types. Furthermore, it’s clear that the US needs to be an attractive environment where where firms simply want to function, where they can receive government benefits to help then get established, and to hire US-based personnel.
Other economies all aggressively support businesses to invest in their own locations (just go through the countries – they all do it, and some very effectively). This legislation does very little to help US call center jobs and will likely cost the tax payer more in implementing the plan than it can ever accrue from the tax. Government leaders need to be smarter about “protecting jobs”, which means actually helping to create work onshore, as opposed to scaremongering / taxing enterprises into forced activities that do not enhance their competitiveness. For example, the proposed “Entrepreneur’s Visa” is a fine idea – it is encouraging top entrepreneurial talent to set up shop in the US and employ US talent, and they will receive a Green Card. We need to see more schemes that drive the global entrepreneurial agenda for the US economy, not hold it back.
We’ve had a lot of dialog (read here) about why most clients aren’t getting much more than they expected, when they signed an outsourcing contract. And when you have someone one on staff who’s been dealing with the same issues for over three decades, you start to wonder what it’s going to take to drive customers to become genuinely “delighted” with the service they’re receiving.
My personal take, based on our extensive research, is that an increasing majority of clients truly want to see some innovation developing in their agreement, but aren’t prepared to upset the applecart to make changes that could spoil their operational status quo.
Our veteran professor of outsourcing, Mike Atwood, has a simplistic view of what needs to transpire for customers to actually receive regular delights… over to you Mike:
Why aren’t I happy with my outsourcer?
How many times have you heard someone say that all our service metrics are green, but the relationship is red? This sort of non-specific concern about an outsourcer seems to be as old as outsourcing itself. It has certainly existed as long as I’ve been in the field. I recently attended an analyst conference for a major outsourcer andran into an old friend who I’d worked with at EDS andwe got around to discussing a mutual client. This client wasn’t to the point of saying the relationship was red, but he clearly didn’t believe he was getting the value he expected out of his outsourcing relationship.
In this case, the issue wasn’t that the wrong metrics had been chosen, or that some weasel words in the definitions had caused them to be upset. The problem was in the clients expectations. Those expectations are something that I think fits well into the frame work of the KANO model. (If you aren’t familiar Google it and you will be) . The model says that expectations come in 3 types;
The first are “basic” elements, which are things that you just assume everyone knows and you don’t write down.
The second requirements are the “metrics” that outsourcers, consultants, lawyers, andproject teams spend forever trying to nail down.
Lastly, “delights” are those things that you can imagine, but when they happen you are actually excited.
I believe all outsourcers spend most of their time andenergy working on making the commitments around requirements (2ndtype) that they signed up to in the contract. The smart outsourcers have figured out that the basics are real requirements, and long ago stopped asking “Where does it say that in the contract?” But I know of no firm that takes an organized, deliberate approach to developing delights. There are some individual relationship managers who do, but that’s about it.
This seems to me to get to the heart of the issue about “why aren’t outsourcers proactive?” There are also issues of sunk costs and unrealized depreciation, as well as operational risk, but beyond them all is this desire to have some creative thinking and changes beyond what I’m getting today. By the way, the deeper you get into an outsourcing contract the better the good old days will be remembered!
So what is an outsourcer to do? I’d suggest that every account team needs to set itself a goal of at least proposing, but better yet, implementing one delight on some periodic basis. The team out to have regular brainstorming meetings and the implementation of delights ought to be managed. To many of us this seems let basic account management, client partnering, but somewhere it has gotten lost andcustomers are sitting around wondering why they hired their outsourcer, even if things are all green!
In its first industry analyst conference, BPO provider Genpact emphasized its business, today, is much broader than supporting General Electric’s back office and primarily delivering finance and accounting (F&A) services.
“Tiger” Tyagarajan (COO – see earlier interview) and Bob Pryor (EVP for global sales, marketing and business development ) co-hosted on May 18-19 in Cambridge, MA in what Genpact billed as its first analyst and advisor conference. The event was well attended by all thekey analysts and many of the consulting firms which regularly help clients hire BPO firms such as Genpact.
The headline message was that the majority of Genpact’s business is no longer with its former parent GE (currently about 40 percent). In fact, its GE business actually declined last year as a percentage of total revenues. Furthermore, only a third of its business is now in finance and accounting outsourcing (FAO). As demand in other areas grows, Genpact will continue to verticalize its offerings in areas such as back office processing for financial institutions and healthcare companies, in addition to developing its IT services, and knowledge process outsourcing (KPO)/analytics offerings.
Genpact’s front and back office client work supports a wide range of industries; mortgage, commercial and consumer banking, investment and wealth management, insurance (property,& casualty, life, actuarial), automotive and pharmaceutical. Genpact’s pharmaceutical vertical provides a diverse range of services, and its banking, financial services and insurance revenue represented 44% of overall corporate revenues in 2009. Its mortgage business has had some interesting changes, which include a new service line in mortgage renegotiation due to recent U.S. government laws.
In addition to the verticals already mentioned, Genpact has grown its presence in the healthcare vertical, as well providing the whole range of services from call center, F&A, analytics, and procurement to large international automotive companies globally. Many of its clients also utilize Genpact’s KPO offerings, leveraging MBA types to do all sorts of analyses that enable them to assess and evaluate risk in many different business areas. These offerings have become so popular that they account for 10 percent of Genpact’s revenues.
Genpact’s IT business accounts for approximately 16% of revenues, from ERP implementation/support and IT infrastructure services. This capability allows Genpact to respond to a new phenomenon in the market wherein CFOs are looking to make rapid transformational changes in the operations of the finance function, and pay for that change in a manner that doesn’t hit much against any quarter’s earnings. The solution outsourcing providers say they are regularly asked for is an ERP implementation or upgrade along with offshoring of the F&A function. This deal structure is compelling to CFOs since everything but severance packages can be paid for over time, much like a software as a service (SaaS) deal. Several of these deals have been worked on in the last year, and Genpact has the capability to be considered.
Genpact is also growing its source-to-pay/procurement outsourcing business. However, it needs to better clarify its source-to-pay partnership and alliance model with ICG Commerce, a significant provider of procurement services. Procurement outsourcing is clearly a space with a compelling value proposition, not only because of the potential for substantial spend reduction, but also because creative contracting and outcome-based performance pricing, are positioned to allow clients to structure an arrangement with little or no up-front investment or risk to themselves.
Like all businesses, Genpact is working on becoming more efficient and increasing its margin. Its answer is in innovation, productivity, higher-end service offerings, automation, site selection for tax breaks, and spend management. It also has high expectations for its Smart Enterprise Processes (SEPSM) offering, a scientific, and granular proprietary approach to business process management which focuses on optimizing process effectiveness in addition to efficiency.
The HfS Viewpoint: Genpact is addressing critical challenges to standardize processes across its clients, but recognizes the hard work is only just beginning
Genpact has expanded into logically adjacent processes to its core F&A base, and is demonstrating healthy growth. It is saying all the right things from a potential client’s perspective about its willingness to assume risk and make significant process improvements.
In its FAO business, Genpact has been at the forefront of the market in recent years, taking on a host of enterprise clients. However, the main challenge in FAO is to develop process standardization across clients, which will enable further growth and profitability. Genpact, like its main competitors, has not been immune to this challenge, but claims to be gaining leverage by sharing resources across its client base. However, in many instances (like the vast majority of today’s FAO endeavors), Genpact uses its clients’ ERP systems and strictly adheres to clients’ controls and risk environments, thus limiting the ability to implement multi-client process standardization . That is, it has to follow the work sequence, quality checks, data verification rules, etc that the client has always used and they cannot change them with the agreement of the client.
Until it can gain wide acceptance of a largely standardized offering, it will struggle to leverage assets across its FAO clients and make process and cost improvements with multi-client impact. However, Genpact does recognize these challenges and is making concerted efforts to bring – and gain – acceptance of more standardized processes to its clients. One of these opportunities to develop process standardization is to provides IT-enablement of processes by delivering a new ERP system to the client. For example, its recent alliance with ERP SaaS provider NetSuite is targeted at mid-market clients which are willing to move to the NetSuite ERP platform and have Genpact service its business processing. In a similar vein, Genpact has also recently partnered with leading insurance asset provider MajescoMastek. We believe these alliances are a move in the right direction to deliver more replicable processes to its expanding client base, while providing differentiated offerings to their principal competitors, many of which are caught up in the traditional BPO log-jam of delivering customized BPO services around legacy ERP systems.
All-in-all, Genpact clearly recognizes where it needs to focus, but it will take another couple of years for the firm to fully demonstrate real business results from many of its new initiatives. The BPO industry is still largely immature, and Genpact can only move as fast as its clients will allow.
You can download this HfS Research Rapid Insight, by clicking here
Mahindra Satyam recently staged it first analyst conference as a new entity, to announce to industry that its new structure was complete, and was a serious IT/BPO services competitor.
Resurrecting itself from the biggest scandal in Indian outsourcing history, a renamed Mahindra Satyam has quietly been going about its business to rebuild trust and confidence in the firm. In the last year, it expanded business with the base of Satyam customers that remained with the company, despite the scandal, with 54 new customer contracts, although several of these are relatively small-scale engagements. It has also formed a new senior management team by injecting some Tech Mahindra leadership, in addition to hiring liberally from its competitors. This new blood joins the existing Satyam leadership that weathered the storm to form an energized and dynamic leadership team.
Noticeably absent was much of the sales glitz that Satyam was famous in the Raju days, with the presentations communicating a more down-to-earth and fact-based approach to services, indicating the engineers are now in charge.
The team was quick to point out that Deloitte has been retained as the new auditor (Satyam was previously using PwC), with KPMG performing the detailed work on restating the financials, which are scheduled be completed by July. Clearly, the newly merged provider is trying hard to clear the air and start on a new footing, firmly based on solid metrics and hard facts.
All of the employees were very much “on message” that most of its critical staff and clients stayed with them throughout this problem period, despite a few notable terminations, for example, State Farm Insurance. There weren’t a lot of auditable facts to back up that claim, but clearly most of the employees and clients that remain at Satyam are there because they wanted to be. There were also representatives from five clients at the conference, all of which had glowing things to say about the company and the service they had received without interruptions. This is consistent with our experience from the crisis days, when many customers were happy with their service provision, and opted against contract termination, despite having the opportunity to do so.
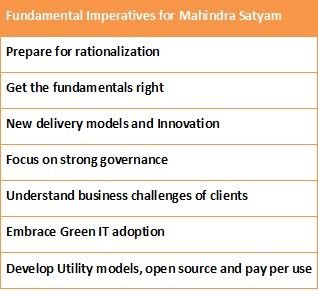
The new team has developed an organization structure that has a matrix centered on functional areas and industry verticals. It has also focused on those areas where it believes it has specific domain knowledge and expertise leveraged from both Satyam and Tech Mahindra. For example, its engineering services (Satyam) and embedded systems (Tech Mahindra) expertise build on the strengths of both firms. Furthermore, the newly-merged provider demonstrates a list of “fundamentals” that it is concentrating on achieving, which include the following tenets:
Table 1: Fundamental areas core to Mahindra Satyam’s strategy
Satyam Mahindra does not yet have very clear messaging regarding its competitive differentiation, but it did push its strategy that it is highly proficient in enabling the mobile enterprise. This dovetails well with Tech Mahindra’s expertise in the telecomm vertical and will allow it to expand into other industries , where enterprise mobility is becoming increasingly important. This will be a powerful differentiator, as the enterprise becomes more and more distributed, provided the firm can demonstrate real client success in mobility.
It also showcased its Bridge Consulting acquisition, made in January 2008, emphasizing how management consulting is now a standard capability through which it intends to lead client engagements, as opposed to positioning it as a specialist offering, such as HCL’s positioning of its acquisition of SAP implementer Axon. This is concerning, since the industry has several examples of other firms that have struggled with a similar strategy, such as EDS with its acquisition of AT Kearney, or the IBM with PWC Consulting. Mahindra Satyam will have to solve the problem of having Bridge recommend its clients increase its investments with Mahindra Satyam without losing its perceived objectivity.
The three industries it has chosen to concentrate on are BFSI, Telecomm, and Manufacturing, but it also has a unit concentrating on a conglomerate of CPG, Retail Travel, and Logistics. The horizontals are the IT basics of infrastructure and applications, a unit looking at Integrated Enterprise Business Solutions, and Engineering Services which includes programming for imbedded devices.
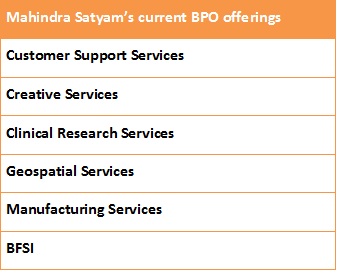
With regards to BPO, Mahindra Satyam has selected six offerings where it has domain experience, developed offerings and IP, and a competitive position in the market. It is noticeably gaining some traction, for example, creating and delivering knowledge process services, where it has been performing some notably commendable KPO work with global pharma giant GSK. This is in addition to other KPO services it currently delivers to many of its current IT clients, as adjunct service offerings.
It has pulled back somewhat from the old days of SatyamBPO, where it was gearing up for competing on multiple horizontal G&A (general and administrative) BPO processes, namely procurement, supply chain and accounting. These are:
Table 2: Mahindra Satyam’s current BPO offerings
HfS Research believes this is a sensible strategy for the interim, as several of the newer BPO entrants are struggling to compete on horizontal BPO services with the likes of Accenture, Capgemini, Genpact and IBM. Focusing on KPO work, and some specific vertlcal BPO is clearly a smarter move, as Mahindra Satyam consolidates its position in the market.
The HfS viewpoint: Mahindra Satyam has weathered the storm, but now it needs to focus on being distinctive, as opposed to following the crowd
The main issue that seem to be of interest to many people, is what Mahindra Satyam has to achieve to return to the ranks of the Indian tier one IT services suppliers , namely Cognizant, HCL, Infosys, TCS, and Wipro. We believe Mahindra Satyam runs the risk of getting stuck as second tier to these companies if it follows the crowd and attempts to replicate very similar offerings to its larger competitors, without genuine differentiation, beyond operational capability. It needs to convince customers of its culture and distinctiveness in areas it already has real credibility (for example enterprise mobility, BFSI and life sciences), and how it has harnessed these capabilities to venture into related functions and markets where the firm seeks to gain a foothold.
Currently, the signs are encouraging for the firm: it has not only stemmed, but stopped the bleeding, and stabilized the very serious situation that threatened the future of the whole Indian offshore industry – and not only Satyam’s. It has decided to concentrate on the functions and industries where it has valuable domain knowledge and IP, and the enterprise mobility theme has real potential whereby to differentiate itself. What it must do now is develop its sales, marketing, and customer interface functions with the same intensity that is has placed on delivery and operations. Beyond that, it will eventually have to move into the horizontal G&A BPO areas if they are going to get invited to the bigger multifunction deals, which will necessitate future acquisitions and partnerships.
All-in-all, the signs are encouraging, but this is only the start of a long journey to establish the newly merged provider.
You can download a copy of this HfS Research “Rapid Insight” by visiting our Published Research page