One of our greatest anomalies has been to run a blog on global outsourcing dynamics for three years and never actually feature a single contribution from anyone at IBM.
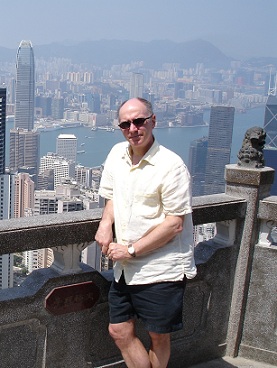
A surreal sourcing paradise: IBM's Bill Payne takes it all in on the Peak in Hong Kong
Well, the cycle had to be broken at some stage… and with who better to do it, than the most down-to-earth and outspoken IBMer you’re ever likely to meet: step up Bill Payne. Bill is IBM’s Vice President for Global CRM and Industries for Managed Business Process Services (that’s IBM speak for “vertical BPO”).
Anyhow, we managed to drag Bill away from tendering his beloved vegetable patch to share with us his current experiences of the market and why he’s having another day in paradise, despite the surreal experiences he has when someone stries to sell him their captive center…
Phil Fersht: Bill, how on earth has the global sourcing world changed since the recession? From a macro-level, what is different these days?
Bill Payne: Isn’t there a song and a movie called “Another Day in Paradise”? 😉
Lets not forget that in q4 2008, and q1 2009, the market was the proverbial rabbit in the headlights and deals basically dried up. We all had our doubts about what the future held . At the same time, the Indian and Chinese economies never went near a recession!
The biggest change in h2 2009 and 2010 so far is more opportunities in both IT and BPO and more urgency in the US market. I also think in the companies that have found success in outsourced processes are going to go a lot further: more scope, newer processes, bigger plays. This is really a market where we’ve barely scratched the surface of potential and the smarter guys will keep pushing boundaries.
I think we are now at the wave front of a lot more process outsourcing
Phil Fersht: Are sourcing decisions being made any faster? Are processes being evaluated for outsourcing different?
Bill Payne: Sadly, it seems that there is little real change in decision velocity. We still see some very protracted procurement schedules. Intuitively, you’d think the recession would have driven some dynamism into the procurement process! What greater lesson could there be to teach companies that they need to be able to quickly reduce costs, quickly scale, and really take control of their bottom lines?
Unfortunately, there is still a cultural barrier in many companies opposed to Outsourcing process. Maybe we’ll finally see some real change when there is an SVP of Services in every client whose job is to manage Internal service across the board. Then you will have service strategy as part of a company’s DNA. I think that will change the culture faster than any other single impetus.
Overall, despite a lot of good momentum and energy, we still haven’t quite built a Smart Planet just yet!
Phil Fersht: Being in the UK, what specifically have you seen change over there? How is this contrasting with US firms and other regions?
Bill Payne: I may reside in the UK but given my global role in IBM, I’m able to take a pretty comprehensive view of the dynamically changing world outsourcing markets. I see more urgency in the US to get cost out, and move to “on demand” contracts that allow flex in up and down turns. I see more balanced shore decisions for location of service centers and more interest in industry solution outsourcing.
In the UK, I see Public Sector as the area with some huge opportunities and contracts on the horizon. There is a crushing need to gain efficiency in both local and national government. In other European countries I see no real change in consideration or speed of BPO execution right now. In Asia, we see trends similar to the US. In the Growth markets of Brazil, Middle East, China, India, and Africa we see some very large potential opportunities across BPO, especially in wider Industry solutions that have a transformation agenda.
Phil Fersht: How does this altered landscape impact a giant provider such as IBM? What opportunities and challenges does it present to the firm?
Bill Payne: In many ways it’s Business As Usual, but in many ways it’s a new BAU.
In our traditional view, I think the BPO market is still there to grow substantially whether it be in the traditional BPO towers or in the traditional BPO markets. Where the market has changed however is in both what clients want and where they want it.
I think the winners will need a balanced shore strategy: @home, on shore, near shore and far shore. We will need to take an industry solutions perspective to deliver service value, and we will be able to provide a long-term secure strategy and financial platform for clients.
There are new spaces in emerging markets and many new processes to outsource.
I think the biggest challenge we have is to be selective and choose our service growth areas and markets with care. We have to drive a “Smarter” agenda with our Smarter Process and Smarter Tools initiatives.
We have to choose which deals to pursue. We have to be able to show clients that we deliver value long-term and we are committed to them. We do not want to engage in badly shaped deals that either can’t be delivered or give poor value to the client or break our financial model. We take pride in doing things right. It serves none of us well in this business to have deals fail for either poor execution or poor commercial arrangements. I think all providers have a duty to their clients and the profession we are in to behave in a controlled and never reckless way!
Phil Fersht: How do you see the competitive landscape across both ITO and BPO playing out with the impact of the crisis? Do you see more M&A between providers, or more cautious investments?
Bill Payne: Undoubtedly there are many M&A opportunities. There are many captive acquisition opportunities. Investment cash talks in the market. However, the financials of a number of IT and BPO providers make sobering reading if you go deep into their P&L and some have made some very expensive acquisitions
I think its tough to realize the benefits of cost reduction/efficiency in an acquisition case, but that’s generally small beans to the ‘miss’ on the revenue growth lever on most acquisitions in this market. It is all too tempting in the heat of an acquisitive pursuit to show an exponential growth curve based on the market size and estimate of the impact of the transaction. It rarely turns out that way.
So, given that there are a number of burnt providers out there, caution may prevail on the A side. On the M side it’s quite possible that a merger will take place within the mid-size provider group. It’s not surprising as they are generally the most cash strapped.
Phil Fersht: You mentioned in the G8 summit at SSON that many captives are currently being shopped on the market – and many unsuccessfully. How do you see those unsuccessful captive sales being resolved – will customers phase them out and move onto BPO models, or just stick with what they’ve got and eliminate more cost out of them?
Bill Payne: I’ve always thought the selling the captive debate to be slightly surreal! The purpose of creating a captive in most companies was to reduce cost and increase service to an internal organisation. Only the really good corporations have tried and tested their business case to ensure they got what they wanted, i.e., a very efficient shared service environment!
However, now try to translate this into a saleable asset somebody else would want. In many cases the captive SSC has been built on internal processes not necessarily ‘industry standard’ or even optimised processes. This leaves all the providers in a dilemma: what value is there in someone else’s processes, buildings, desks chairs, computers, and people? It doesn’t take much of a spreadsheet jockey to calculate that the vast majority of captives warrant little or no cash premium in a deal to the client, and actually if you are a major global player already, you probably don’t need the infrastructure.
There may be a case for a platform acquisition and the inherent IP, however, never underestimate the work and cost required to convert an in-house tool into a market ready application.
If you are a medium sized or regional player it may make sense but buyer beware: I don’t see many pronouncing that they met their growth target by buying a captive in BPO world!
Phil Fersht: And finally – what advice would you give to young executives today looking to develop their careers in global sourcing?
Bill Payne: Learn about Transition and Delivery. Do the hard yards! Go work in a delivery centre, learn the ropes, learn the processes, tools techniques, and metrics. That way you can add value to every client.
Most importantly: always act with integrity. Deliver what you say you can, deliver and show the benefits, and give the client what they want. These attributes are how you make your own company successful. Be candid, open, and straight.
Phil Fersht: Bill Payne, thanks for your time: our readers will appreciate reading your views
Bill Payne (pictured above) is VP for Global CRM and Industries Managed Business Process Services at IBM
Due to unprecedented demand for research, (plus the fact we’re kinda new and trying to do some), we’re actively looking to bring on some additional analyst talent.
If you have some excellent experience in global sourcing, love to write, have an opinion and a bit of an attitude, we’d love to hear from you, whether it be as a contributor or full-time analyst.
Drop us an email if you’d like to be considered. All resume submissions will be treated with the utmost discretion.
We’re delighted to announce two new experts who will be adding their tuppence to the HfS agenda.
As part of our new research alliance with EquaTerra, Stan Lepeak will be contributing on a broad array of global IT and business process areas (view Stan’s bio here). Stan leads global research for EquaTerra.
In addition, Andy Milroy, already famous for his recent blog contributions (see here and here) joins us to add his spin on Asia/Pacific IT and BPO dynamics. Andy currently leads Frost & Sullivan’s Australia and New Zealand ICT Practice (view Andy’s bio here).
Whenever you mention the world “Cloud” to an experienced IT infrastructure professional, he or she will likely talk up the dreaded “S” issue as a major obstacle that will derail Cloud ever really being widely adopted across enterprise processes.
Quite simply, Cloud computing represents one of the biggest opportunities and threats to IT professionals today. However, spend some with the CTOs at the likes of eBay, Amazon, Salesfore.com etc., and their eyes will light up talking about their intense development programs, where they are training young IT talent to learn how to Cloud-enable applications that can underpin many different types of business processes.
Cutting to the chase, where industries such as IT services are rapidly commodotizing, don’t they need a new wave of innovation to drive new development, new thinking and new energy to create new levels of productivity and top-line growth into enterprises? Having business processes enabled to be provisioned on-demandin the Cloud is a massive disruptive opportunity for both providers and buyers of global business/IT services. Our forthcoming research wave on Business Process as a Service (BPaaS) is fleshing out the potential versus the reality of this happening (stay tuned).
Anyhow, we did want to get the “S” issue firmly on the table for discussion, so asked our new expert contributor, Andy Milroy, to weigh in with some of his perspective here…
Cloud Security – A Pleonasm?
The IT industry successfully generates billions of dollars each year by selling us security products and services. Security always plays a major role in any corporate IT purchasing decision. But, we are still a very long way from securing our IT environments.
Most security breaches are caused internally by employees or other authorized users of corporate systems such as contractors. It is these groups that are most likely to compromise the integrity of our systems, not external hackers. In spite of this, much more focus tends to be placed on external threats. Each time I work on a client’s site, I am struck by how easy it would be for me to compromise their systems. All I would need to do is insert a thumb drive with malicious code into a USB port and, hey presto, I’ve undermined hugely expensive security investments.
It is reckless to allow employees and contractors to carry highly sensitive data around with little consideration of the consequences of losing the laptops and smart phones that house the data. Amazingly little focus is placed on addressing this particular security threat.
Indeed, enterprises do not sufficiently focus on changing the behaviour of their users by making them aware of security policies and the reasons for those policies. Few ensure adequate control of basic access to their physical premises and to end points that form part of their network. As mentioned earlier, it also seems as though few enterprises track the location of sensitive data that physically moves around with employees and contractors.
Ensuring that everybody who accesses enterprise networks is trained to follow appropriate security policies is an extremely challenging task. For this reason, it is necessary to consider other ways of mitigating the risk of an employee or contractor from compromising security.
One way of doing this is to source as much of the enterprise’s computing resources from the cloud as possible. Managing the security of heterogeneous on-premise IT environments is a highly complex and almost impossible task. Minimising the amount of on-premise resources that a corporation manages mitigates risk associated with security breaches enormously. Ensuring that data is stored in a secure environment (in the cloud) rather than on portable devices such as laptops and smart phones also enables corporations to mitigate risk.
Cloud computing, and I mean public cloud computing, allows us to mitigate risk and in many cases offer greater security that can be provided by spending millions of dollars in an attempt to secure on-premise resources.
Multitenancy and virtualization do indeed add a lot of complexity to providing levels of security that many enterprises require. However, public cloud services providers such as Google, Amazon, Microsoft and Salesforce.com focus heavily on ensuring that their datacenters follow best practice security policies and are using the most up to date security tools. Security can also be tied into service levels.
So, using public cloud services can offer more security than keeping data and other computing resources on-premise. These services can also reduce the amount spent on security massively. Perhaps this is the reason why many in the IT industry are keen to dissuade us from using cloud computing.
Andy Milroy
Security is always a challenge. But, there is little evidence to suggest that using the public cloud is less secure than the traditional on-premise form of computing. In fact, there is more evidence to suggest that using public cloud services can, in many cases, mitigate security risks that exist with on- premise computing alternatives.
The cloud model of computing is much better positioned to address today’s security challenges and concerns than alternative models. So, will the term cloud security soon be considered to be a pleonasm?
Andy Milroy, pictured here, is Expert Contributor for Horses for Sources Research. You can access his bio here. He likes to be tweeted at @andy1994
Forgive me father, for I hath missed gain-share opportunities…
While there’s a lot of puff coming from several providers, expectations are not being met when it comes to the actual achievement of innovation within many Business Process Outsourcing (BPO) engagements. Consequently, this improves the options for the first-time BPO buyer to select a provider that can demonstrate a proven track record of innovation, but what about the second-time buyer, firmly-rooted in BPO purgatory?
Our brand new survey* of 588 shared services and outsourcing executives, studying the current achievements of innovation within BPO, serves up a major does of realism to the global sourcing industry: buyers want it, but they are not working effectively with their providers to achieve it. And many buyers and providers are pointing the finger at each other. So why should we care?
Innovation is becoming a critical component when it comes to BPO
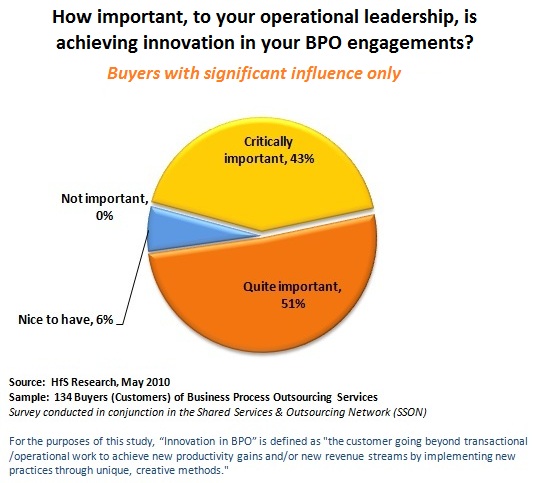
In the past, many buyers shied away from innovation because they were so laser-focused on achieving operational stability within their BPO environment. Many claimed that they would have to sacrifice meeting service levels if they tried to tinker with their processes to find new ways of achieving better outcomes. However, when we look at how those buyers with significant influence over BPO decisions are viewing innovation today, the importance being placed on innovation is distinct:
Close to half of enteprises’ operational leadership today now view the achievement of innovation as a critical component of their BPO strategy. With most providers operating within a similar price-band today, this is clearly becoming the major differentiator for the first-time BPO buyer, as we first discussed in our “New Normal in Outsourcing Delivery” study, ealier this year.
First time BPO buyers can select proven innovators, but the second-time buyers have a challenge on their hands to escape BPO purgatory
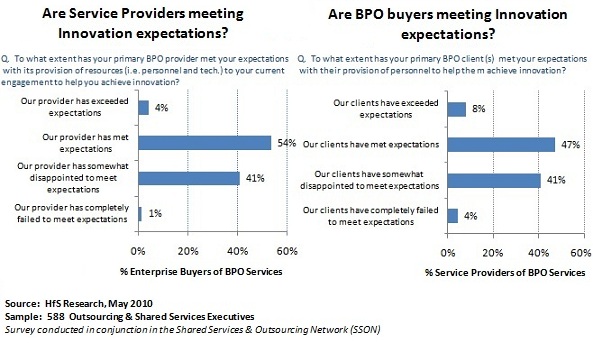
As the following data illustrates, both buyers and service providers of BPO services are equally disappointed with each others’ provision of resources and technology to meet their expectations of achieving innovation. Considering 38% of enterprise customers view innovation in BPO as critically important to their operational leadership, with a further 50% viewing it as quite important, this is becoming a major concern for the future of BPO services:
While the present disappoints, hope for future innovation is abundant
While buyers are clearly not seeing a lot of business value beyond operational delivery today, they see abundant potential for innovation in both generic processes and industry-specific domains.Major findings, which will be featured in a forthcoming HfS Research report, include the following dynamics:
More innovation has currently been achieved across industry-specific, analytics, supply chain and general accounting processes. Customer care, recruitment, payroll and management reporting are noticeably failing to meet customer expectations.
The potential to achieve innovation across many core business processes is huge. This was notably cited in industry-specific process and analytics areas, in addition to some maturing BPO domains, namely procure-to-pay, and payroll and recruitment.
Major impediments to buyers achieving innovation included unempowered governance teams, and ineffective change management and communications.
The Bottom-line: escape-plans from BPO purgatory are bring hatched, but the hard work starts now
All-in-all, an increasing majority of buyers are aware they can achieve innovation, and know the potential is there to do exactly that. Moreover, most realize the blame doesn’t always sit with their service provider – it rests with both parties to work together to a well-crafted plan that introduces innovative goals and milestones over time, that do not derail from meeting service levels that actually matter. This involves developing more partnership-oriented relationships with their service providers, increased IT-enablement of business processes, and developing gain-sharing metrics based on business outcomes.
Stay tuned for Part II, which will take a look at the specific processes where innovation is currently being achieved, and – perhaps more importantly – where their is real innovation potential in the future…
* The survey, entitled “Are you Achieving Innovation in BPO”, was conducted in May 2010 by HfS Research, in conjunction with the Shared Services and Outsourcing Network’s (SSON) network of senior finance and operations executives. It received 588 participants that encompassed senior decision-makers within buy-side enterprises, BPO service provider executives and outsourcing advisors.
For the purposes of the study, “Innovation in BPO” was defined as “the customer going beyond transactional / operational work to achieve new productivity gains and /or new revenue streams by implementing new practices through unique, creative methods.”
Sue Marks, Chief Executive Officer, Pinstripe Talent Acquisition Solutions
Without any doubt, the best known figure in the world of Recruitment Process Outsourcing is the all-tweeting, i-pad-wielding, champagne-supping, serial entrepreneur herself, Sue Marks, CEO of high performance talent acquisition solutions firm, Pinstripe.
As we ready ourselves to produce the results of our new RPO study in conjuntion with Human Resources Executive magazine, who better to have a conversation about the future state of RPO than Sue herself? So we sent our roving HRO analyst, Mindy Blodgett, out to catch up with Sue the other day…
Here at Horses, our research reveals that C-level executives are showing heightened interest in the potential of Recruitment Process Outsourcing (RPO). Prior to the deep economic downturn, many enterprises resisted handing over their recruiting functions to a third party to manage – many saw recuiting as something they could manage better themselves. However, the demands of a fast moving, post-recession economy are nudging business leaders towards exploring RPO as a means to add talent acquisition expertise and flexibility in a fast, cost-effective way. Many are faced with the need to scale their operations faster than they had envisaged, and they simply to do not have the internal resources to cater for these requirements in this market.
However, misconceptions about what RPO actually is continues to muddy-up the marketplace and confuse the buyer. We talk with Sue Marks, the CEO of RPO provider Pinstripe, about trends in this slice of the HR universe and whether it might even be time to retire the phrase “RPO” in favor of something that might better describe what companies get when they outsource their recruiting process in all or in part.
An unabashed workaholic and gadget geek (she loves her new iPad, we at Horses can attest to that) – Sue Marks is the founder and CEO of Pinstripe, Inc., a privately held, venture backed HR and Recruitment Process Outsourcing firm serving large and mid-sized domestic clients, as well as the Global 5000. She sits on several profit and not for profit boards and is President of Competitive Wisconsin, Inc. She literally grew up in the recruiting business, as her Dad was a recruiter for Management Recruiters (now MRI). She is an evangelist for the RPO model, a thought leader and frequent speaker and can honestly be called one of the industry’s pioneers. Take it away Sue!
Mindy Blodgett: Is the increased interest in RPO due to the new realities of the financial explosion and the slow recovery?
Sue Marks: It’s certainly a big factor. What we are experiencing now is a period of relentless change. This economy compels organizations to adopt very agile structures. I think that when you dissect some of your functions into components, and are able to plug those pieces into a service delivery model, you can be more flexible and scalable – up as well down. This allows the operating cost structure to better align to the customer’s business needs. You can also respond better to market forces That is what well-designed RPO does the best – rather than being a monolithic outsourcing model that does not allow users to use the pieces they need, when they need it – a good RPO deal,provides flexible, scalable components.
Mindy Blodgett: While there is increased interest in RPO, there is also a good deal of confusion out there about what RPO means and what it does. Why is that?
Sue Marks: What we call RPO (and what I like about the term) is that it distinguishes us as firms that are reengineering the process with technology, rather than just providing volume recruiting services. Unless the combined BPO and technology piece is there, it’s not truly RPO. A lot of people confuse RPO with volume recruiting. In reality, though, I think we should be talking about HR and Talent Acquisition Service Delivery Models that are architected to be “plug and play”, or componentized, both domestically and globally. Because in today’s world of relentless change, we have to be architects of flexible, rather than one sized fits all, monolithic service delivery models.
This gets me back to the right “components” of a company’s Talent Acquisition Service Delivery Model. I think the suppliers who will be successful in this RPO space are those that have flexible modules with some capacity for customization. One size doesn’t fit every client but there has to be an effective way to customize within that service delivery platform while also retaining consistency at a high level.
Mindy Blodgett: Back to the term: RPO…should we be coming up with a better phrase or acronym?
Sue Marks: I am hearing more strategic thinking on the part of companies looking at their recruiting needs. It’s not just about “this project” and the need to get human resources support– it’s about “resourcing” and the supply chain of talent. Perhaps we could call it Human Capital Supply Chain or Talent Sourcing Supply Chain… but then you wouldn’t have RPO fitting nicely in with the other ‘O’s’.
Mindy Blodgett: What else are you thinking about these days?
Sue Marks: I’m disappointed by little process improvement has occurred in our space. Think about recruiter requisition loads … most people I talk to still have about 20 reqs per recruiter as their standard. If American manufacturing and service industries had spent the last decade with zero productivity gains, we’d be at the bottom of the global food chain. If you think about HR and look at “broadbanding” in terms of talent acquisition, that may help. You also have to look at the entire system and not just the applicant-facing pieces of it. How do you reduce demand on the system the way you reduce pressure on a call center by not having software that breaks down? We need to be working on these things.
I’m also hearing a lot of “change fatigue” from all levels of staff. The best organizations are really worried about how they can help their employees to recharge. This gets us back to the pace of relentless change: how do you help your organization regenerate now that things seem to be improving? People are also talking about the “invisible competition”, which refers to the unpredictability of competitive forces in every aspect of our profession and our business. One of our roles is to help our clients “think around the corner” to be anticipatory, rather than reactive. To get ahead of the wave, instead of being drowned by it. It’s what keeps me up at night on one hand, and keeps me excited and optimistic about our business and our future on the other.
Mindy Blodgett: Thanks so much for your time, Sue.
Sue Marks (pictured above) is Chief Executive Officer for Pinstripe. You can access her full bio here, and follow her on Twitter at @SueMarks.
If you’re an HR practitioner with recruiting responsibility, your opinion is vital for our research. Horses for Sources and HRE have teamed up to run the following survey assessing whether HR departments are using RPO, your current experiences and attitudes towards RPO, and whether you plan to explore RPO as a recruitment enabler in the future. Please click on the following link to share your views and experiences with us:
493 posts, 2386 comments, about 3 million visits and THREE YEARS in the making… Horses for Sources enters a fourth year of thunderous frolics… thanks for all your support and comments. Keep ’em coming!
“Gentlemen, when the enemy is committed to a mistake we must not interrupt him too soon”.Admiral Horatio Nelson, 1795
“This is a new and different way to replace those Stone Age on-premise applications.”Zach Nelson, CEO of NetSuite, 2010
Hot on the heels of its recent alliance annoucement with Genpact, we caught up with NetSuite CEO Zach Nelson to get his take on Business Process Outsourcing delivery, and how he intends to leverage that channel to oust incumbent ERP platforms from midmarket businesses with his Cloud Computing business management software suite.
Zach is a legendary figure in Silicon Valley, where he held exec positions with Oracle, Sun Microsystems, and McAfee/Network Associates, before taking NetSuite to IPO in 2007. He now finds his firm at the forefront of this new movement to leverage on-demand applications in a BPO model, or what we term at HfS “Business Process as a Service” (BPaaS). Anyhow, we dragged Zach away from the love of his life (his job, not the golf course) to get a few soundbites on how they are approaching the BPaaS model…
Phil Fersht: Good morning Zach. Let’s get straight to the point here…Fill us in on your alliance with Genpact.
Zach Nelson: The real starting point of our relationship revolves around enabling Genpact to take NetSuite and customize it to provide a platform for clients’ financial business processes around procurement and some of the other core processes Genpact is really proficient at. Our target market is upper mid-market companies, or divisions of large enterprises, which are legacy version-locked on ERP platforms such as SAP or PeopleSoft. And I believe that’s how we came together with Genpact. I think Genpact realized the inefficiencies of the traditional BPO model for the mid-market, and had a vision to change the market and the delivery model with a rich, cloud-based enterprise management platform on which other applications can be built.
Phil Fersht: Which of you will lead discussions with prospects? You with an outsourcing-interested client, or Genpact with a client it feels may benefit from the NetSuite platform?
Zach Nelson: Due to our joint target market, Genpact will be pulling us in, more than we will be pulling it in. While our companies have some overlap in the mid-market, Genpact will have more opportunities to court organizations that want to outsource their business processes. NetSuite, as a separate provider, will continue to secure opportunities from companies that want to deliver their services in-house.
Phil Fersht: One of my philosophies in BPO is that if you are focused purely on running processes at lower-cost labor, another provider will always come along and do it cheaper, and yet another cheaper, and you ultimately get down to the lowest cost denominator. We’ve seen it with some service providers offering SAP BPO services, for example, where they were simply processing invoices and paychecks at lower prices than their competitors. My stance has been if you can build some underlying software IP into your service delivery, that’s going to give you a whole new level of value capability. So,Genpact pushing NetSuite sounds great to me on paper, but my concern is what happens if you get every Genpact competitor doing the same? Is Genpact protected with any form of exclusivity in this alliance, or will you work with any provider that comes along?
Zach Nelson: Genpact has a “natural” exclusive in that I don’t think most BPO providers actually want to change their business model to give their clients a more efficient and cost-effective cloud-based solution. They want to stay on the SAP gravy train and keep harvesting that revenue. But again, I think Genpact has a different vision and strategy which will be able to deliver three-fold client value from NetSuite…cost reduction due to cloud-based delivery, the ability to embed existing IT software into the NetSuite SuiteCloud platform, and multi-country consolidations that can be achieved in as little as three months.
Phil Fersht: How will licensing of your software work?
Zach Nelson: Customers will have a single contractual touch point with Genpact. Genpact will in effect pay us for the NetSuite application and build it into the service it provides to the customer. Our initial implementations will likely be jointly managed to ensure successful knowledge transfer. But since Genpact is an extremely high quality organization, NetSuite will very quickly become part of its packaged offer.
Phil Fersht: How many client engagements are currently in discussion or underway with this partnership at this point, and what sort of energy are you sensing with the alliance?
Zach Nelson: Today, at the beginning of our alliance, we have about 10 active, big, opportunities. And of course we have to get the first ones under our belt and successfully service them. We’re seeing a lot of energy on Genpact’s side. It’s seeing great opportunity in the cloud/BPO-marriage space, and is betting on us to get them there. A great thing you’re going to see, and we’ve seen it in the mid-market VAR channel, is the companies who bet on this early have a huge competitive advantage over those who join in later. There is no stopping SaaS as the future of the way all applications will be delivered, including outsourced applications. The faster you engage, the sooner you’ll gain an insurmountable competitive advantage.
Phil Fersht: When you look down the road at your own go-to-market strategy, are you hoping the outsourcing services channel will be your next big outlet, or do you still think it will be primarily through direct sales, and this alliance with Genpact is just a little incremental play?
Zach Nelson: NetSuite has always believed the channel would be important to deliver our application’s value to the customer. When we started the company we created a program that enabled service providers of all types to deliver NetSuite as we felt strongly about giving others the ability to gain from recurring revenue. That said, the services channel has historically been reticent to fundamentally transform how they run their businesses. The direct channel is something we had to build early on because the channel was not very excited about SaaS, but we have always had in place a rich series of partner programs, and we’re very flexible in terms of how we deal with partners. Genpact is a one-off relationship in which we felt we could both alter how we market to our mutual advantage, and that of our shared customers.
In the second part of this interview, Zach will discuss how this new BPaaS model will be a game change in the industry. Stay tuned.
Zach Nelson (pictured above) is President and Chief Executive Officer for NetSuite with more than 20 years of leadership experience in the high-tech industry, where he has held a variety of executive positions with leading companies such as Oracle, Sun Microsystems, and McAfee/Network Associates. Zach has been CEO of NetSuite since 2002. One of top 10 visionary CEOs in the Silicon Valley, he led NetSuite’s successful IPO in 2007.