Main Street is operating in a very different reality to deliver on Wall Street’s lofty AI expectations, and it’s playing havoc with the current state of IT services.
Valuations are plummeting, many heritage services firms are suddenly looking like bargain-basement buys, and services firm leaders are under unprecedented pressure to convince the investor community that their firms are still relevant in the wake of the AI onslaught.
Moreover, many enterprises, seeing this carnage unfold, are greedily demanding increasingly cheaper rates from their services partners, citing AI as the new lever to deliver the same for even less, despite having little clue how to adopt AI themselves. All of today’s services firms are in full AI obsession mode, desperately positioning themselves as AI evangelists and technology implementers, when the reality is that they need to focus on being the foundation-fixers enterprises desperately need to avoid massive AI failure.
Net-net, Wall Street will soon feel the agony of this AI balloon bursting if today’s smartest services firms are not deployed to prepare Main Street for this AI future our whole economy is gambling on. Folks, services-as-software needs to be valued as the balance between success and failure.
The Wall Street Narrative: AI will replace the IT Services Sector
On June 18, Accenture reported what most companies would consider a solid quarter. Revenue grew 6%, EPS increased 9%, margins expanded, and the company generated $3.6 billion in free cash flow. Yet none of that mattered to investors, who sent the stock down almost 18% in its worst single trading day on record.
The selloff quickly spread across the sector, pulling down TCS, Infosys, Cognizant, Capgemini and every other major IT services provider. As a result, leading IT services firms now trade at roughly 1.5x revenue, while AI-native companies such as Anthropic, OpenAI, Palantir and SpaceX command valuations ranging from 20x to well over 100x revenue. Wall Street has clearly decided that IT services belong to the past while AI belongs to the future.
Despite all the excitement around generative AI, fewer than one in ten enterprise AI pilots make it into production because organizations remain buried under an estimated $18 trillion of accumulated technology, data, process and talent debt. Until that debt is addressed, the AI future investors are pricing into these companies simply cannot be realized at scale.
Ironically, the firms with the expertise to help enterprises overcome those barriers are the very ones the market is punishing today. That widening gap between Wall Street’s expectations and Main Street’s reality is becoming one of the defining investment stories of 2026, and unless those two worlds begin to converge, this could well be the year AI hype collides with enterprise execution.
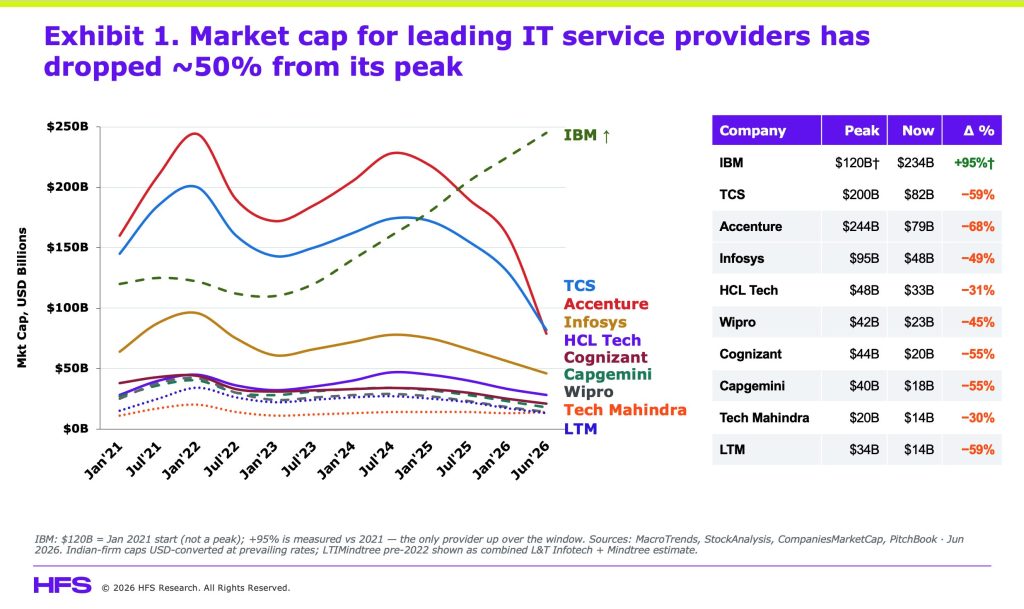
Since reaching their peak in 2021, the world’s ten largest IT services firms have collectively lost more than $600 billion in market value. That collapse wasn’t triggered by a collapse in revenue, profitability, or cash generation. Instead, it reflected Wall Street fundamentally changing its view of the sector, re-rating IT services on the belief that AI-native companies represent the future while traditional services firms have become yesterday’s story (see Exhibit 1).
One company largely escaped that fate. While the rest of the sector saw their valuations steadily compress, IBM has roughly doubled its market capitalization over the same period, not because it suddenly started growing dramatically faster than its peers, but because it successfully repositioned itself as a hybrid cloud and AI platform company whose consulting business increasingly revolves around software, automation and proprietary assets rather than people. The market wasn’t rewarding IBM for what it had delivered. It was rewarding what investors believed it could become, a software and AI business that happened to own a consulting arm rather than a consulting business trying to sell AI.
That distinction matters because Wall Street no longer values IT services firms primarily on what they earn today. It is valuing them on whether investors believe they can become something fundamentally different tomorrow.
Wall Street is pricing two completely different futures
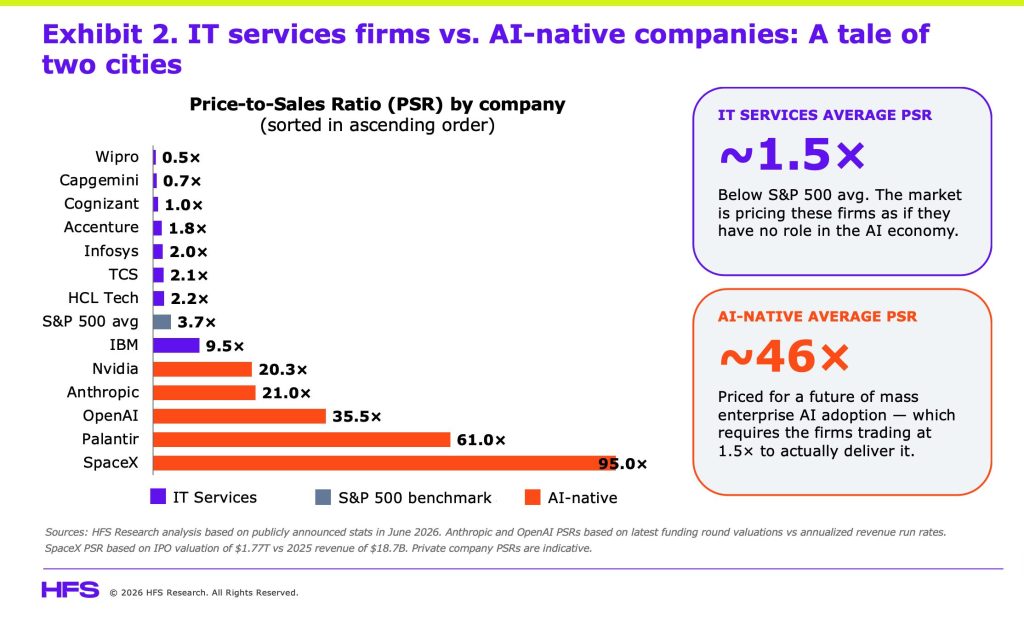
The numbers make the disconnect even starker. The largest IT services firms now trade at an average price-to-sales ratio of around 1.5x, less than half the S&P 500 average of 3.7x. Yet these are businesses generating tens of billions of dollars in annual revenue, serving the world’s largest enterprises under multi-year contracts, growing at roughly 5% a year, and consistently delivering operating margins in the 15% to 20% range. They are highly profitable, generate significant cash, and sit at the heart of the global economy. Wall Street is valuing them as though those advantages are rapidly becoming irrelevant.
The companies on the other side of the AI divide tell a very different story. Palantir trades at roughly 60x revenue, OpenAI’s implied valuation equates to around 35x, and newly public SpaceX commands close to 95x revenue. Across the leading AI-native companies, the average price-to-sales ratio now exceeds 45x. Investors aren’t buying today’s financial performance. They are paying for a future in which AI has moved beyond experimentation, every enterprise workflow is AI-enabled, and autonomous systems have become the operating model for business itself (see Exhibit 2).
The gap between 1.5x and 45x isn’t simply a valuation spread. It reflects two completely different beliefs about where value will be created over the next decade. One assumes today’s services model is headed for structural decline. The other assumes AI will scale seamlessly across the enterprise. The question this paper explores is whether both assumptions can really be true at the same time:
The Main Street Narrative: AI Is Hard to Adopt and Even Harder to Scale
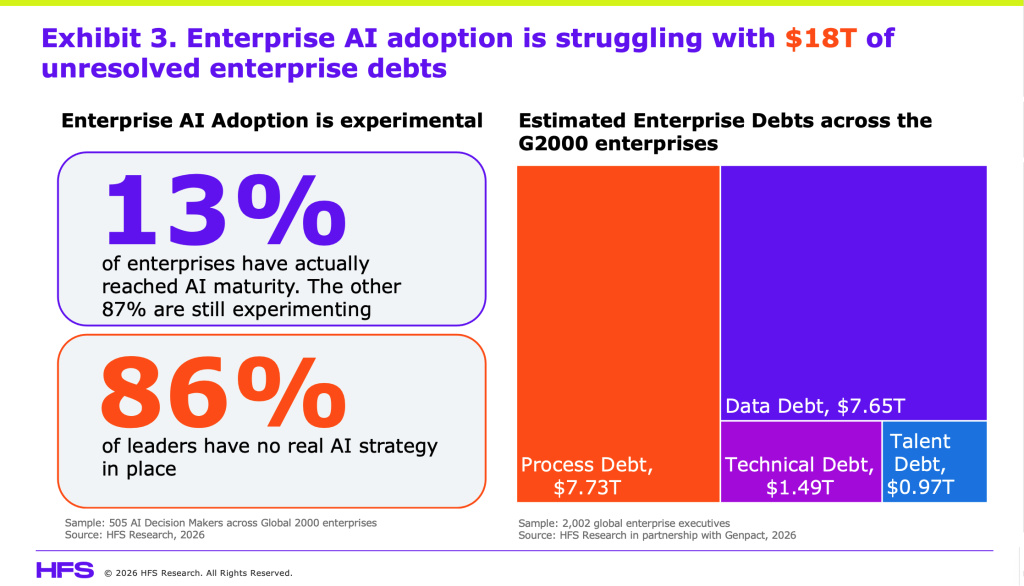
While Wall Street is pricing AI as though the enterprise transition has already happened, Main Street tells a very different story. Enterprises are enthusiastic about AI, but only 13% of Global 2000 organizations have reached any meaningful level of AI maturity, leaving the other 87% still experimenting. Even more telling, 86% of enterprise leaders admit they still lack a coherent AI strategy (see Exhibit 3).
In other words, the AI future investors are valuing at 20x, 50x, or even 100x revenue, which still exists largely in the lab for most enterprises. It hasn’t been deployed at scale, it isn’t fundamentally changing operations, and in most cases, it isn’t yet generating meaningful business value.
The technology isn’t the problem. Enterprise readiness is. Decades of accumulated debt have left organizations structurally unprepared to absorb AI at scale, and until that debt is addressed, even the most powerful models will struggle to deliver meaningful business outcomes. We see this debt falling into four distinct categories:
Technology debt: Aging infrastructure, technical complexity, and years of underinvestment leave enterprises maintaining legacy systems instead of building new capabilities. Many core platforms simply weren’t designed to support modern AI workloads.
Data debt: Critical information remains fragmented across disconnected systems, while weak governance, poor data quality and inconsistent ownership force employees to spend enormous amounts of time cleaning and reconciling data before AI can use it effectively.
Process debt: Too many organizations have introduced new technology without redesigning how work gets done. Siloed processes, inconsistent governance, and manual handoffs create friction that no AI model can remove on its own.
Talent debt: Many organizations still lack the skills, operating models, and leadership needed to embed AI into everyday work. Capability gaps, limited AI readiness, and shortages in critical roles continue to slow adoption even when the technology is available.
Taken together, these four forms of enterprise debt represent an estimated $18 trillion challenge across the Global 2000, which our deep research across more than 2000 Global 2000 enterprise leaders reveals. More importantly, they explain why AI adoption has stalled and this isn’t primarily a technology problem. It’s an implementation problem, a transformation problem, and ultimately a leadership problem:
So, Wall St, who resolves this adoption nightmare? We’ll give you a clue… it’s not the AI-native startups, the model providers or even the infrastructure hyperscalers. It is the Accentures, the TCSs, the Infosyses, the Cognizants, the Wipros and HCLs of the world. The firms that know the client’s ERP, the data architecture, the institutional processes, and the change management levers. The very same firms you’ve written off as irrelevant players from a bygone era where actual expertise mattered and humans needed humans to fashion solutions and outcomes.
The HFS Narrative: The lines between Services and Software are blurring giving rise to a new category we call Services-as-Software
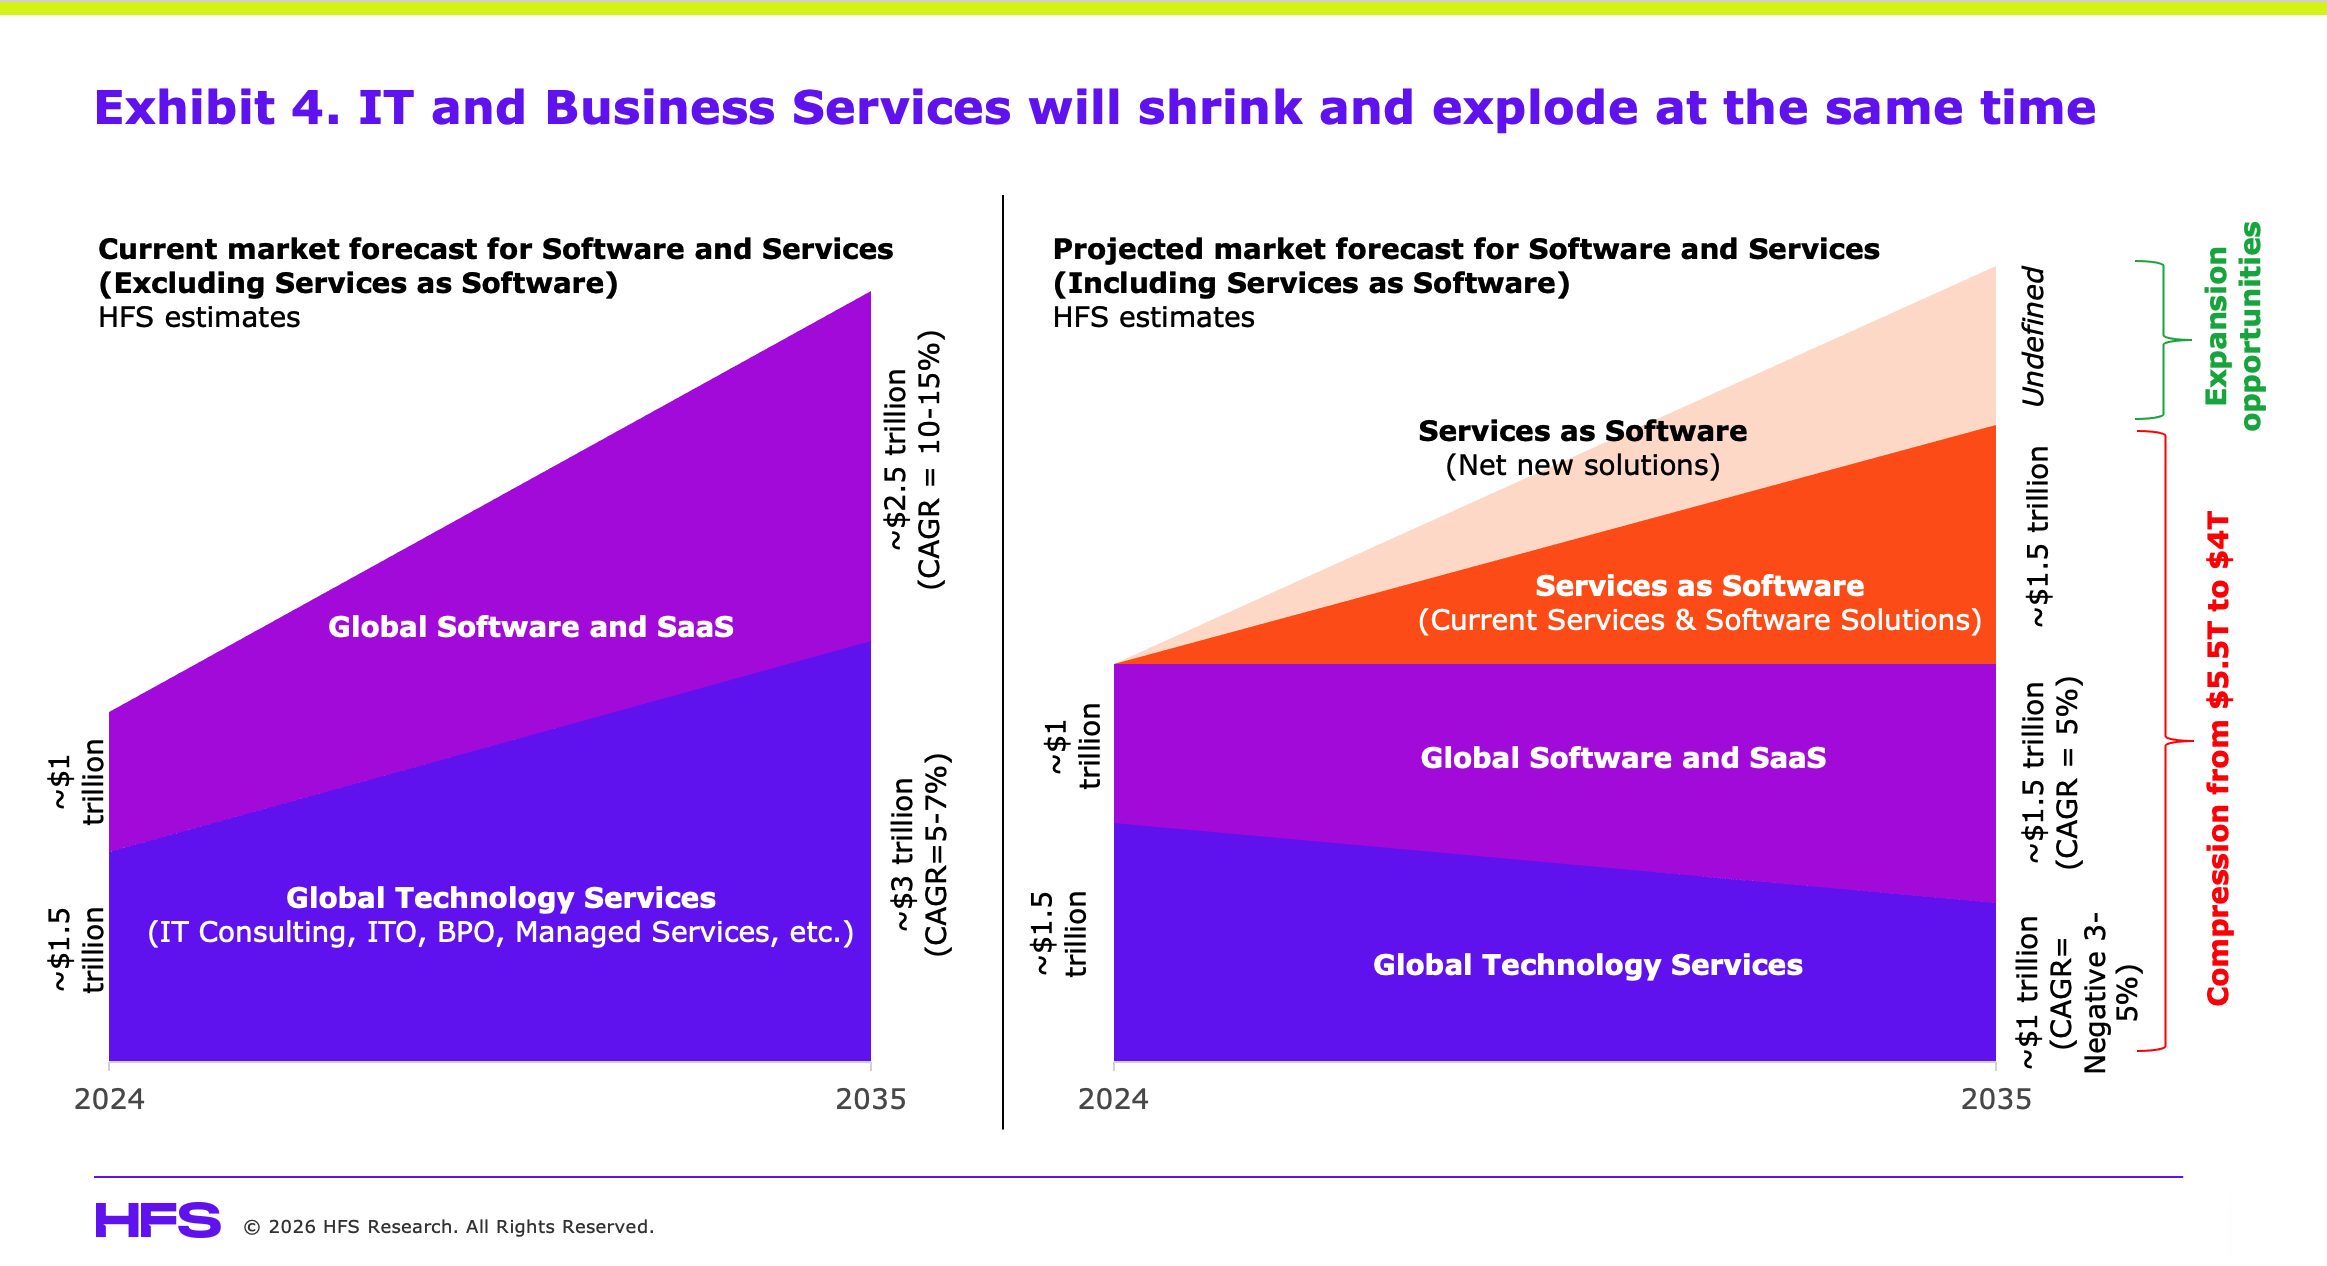
Wall Street isn’t wrong to expect disruption. More than a year ago, HFS forecast that the combined IT services and software market, which was on track to reach roughly $5.5 trillion by 2035 under the old delivery model, would instead compress to around $4 trillion as Services-as-Software fundamentally changes how enterprises consume both technology and services. That compression comes from eliminating value trapped in two legacy models at the same time, which are labor-intensive services that charge for effort and software businesses that continue to monetize static licenses rather than business outcomes.
In other words, the traditional billable-hour model will shrink, and so will the bloated SaaS licensing model that has dominated enterprise software for the past two decades. That part of Wall Street’s bear case is not only credible, but it is also already starting to play out (see Exhibit 4).
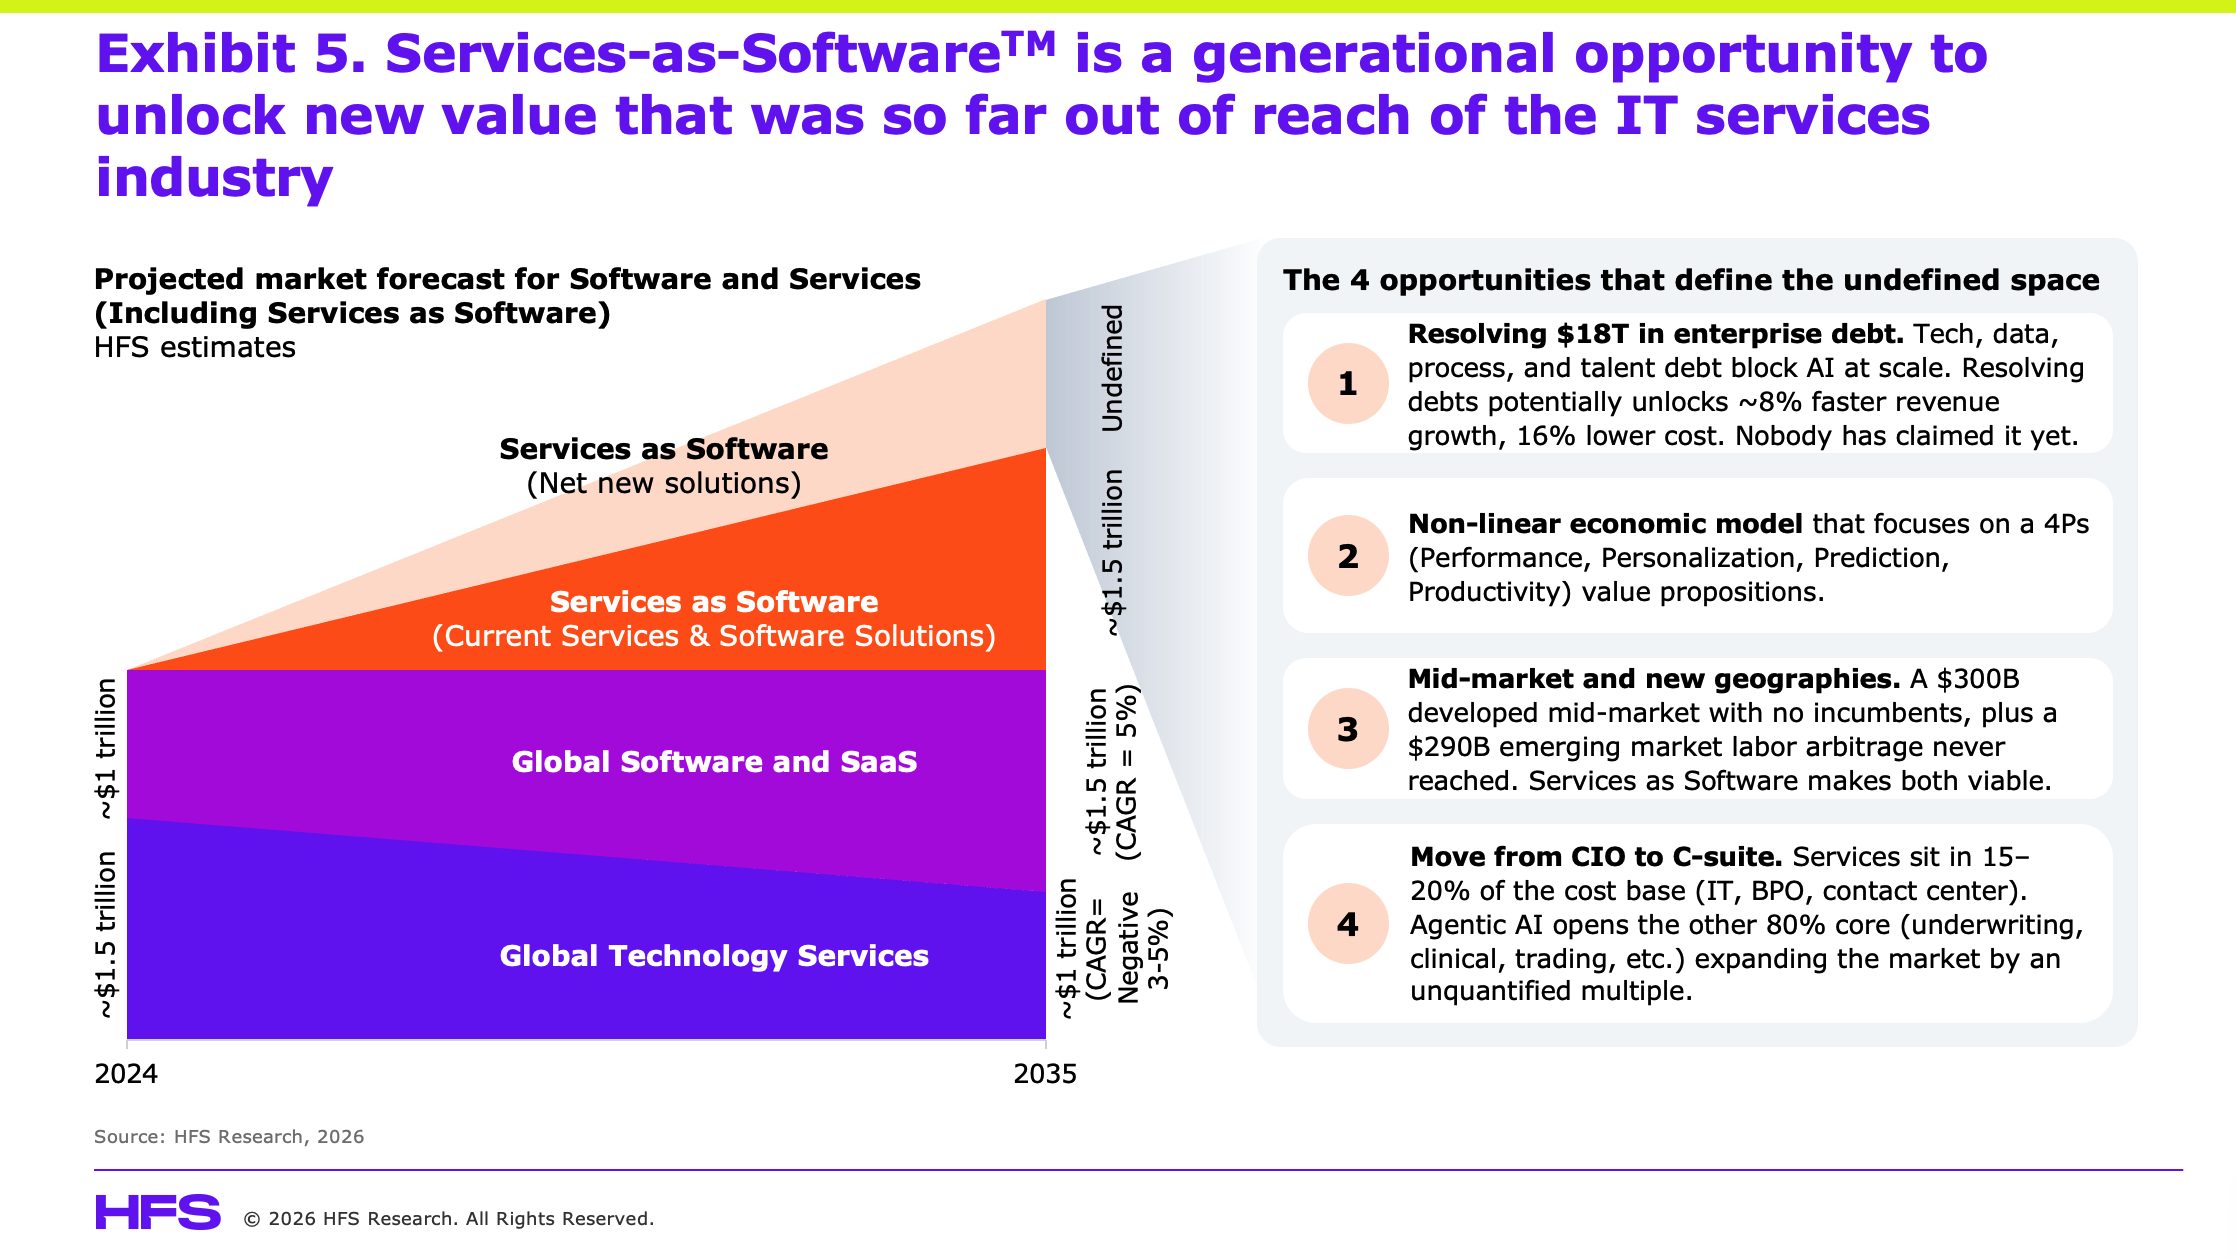
But that is only half the story. While Wall Street is focused on the value being destroyed in the traditional labor-based services model, it is largely ignoring a new triangle of value emerging above it. This is net new opportunity that the old headcount-driven model was never capable of capturing, and it falls into four distinct areas (see Exhibit 5).
Resolving $18 trillion of enterprise debt. Technology debt, data debt, process debt and talent debt are the biggest obstacles preventing AI from scaling across the Global 2000. Traditional FTE-based delivery keeps those problems under control but rarely eliminates them. AI-native remediation changes the economics completely, allowing providers to remove debt rather than simply manage it. The firms that combine AI with deep client relationships, transformation expertise and privileged access to enterprise systems will be uniquely positioned to unlock this opportunity. For enterprises, the prize is significant, with the potential for around 8% faster revenue growth and a 16% reduction in operating costs. Remarkably, no provider has yet established a clear leadership position in this market.
A non-linear economic model. For decades, IT services have priced effort by the hour, tying revenue directly to headcount. AI breaks that relationship because value no longer scales linearly with labor. The next generation of services will increasingly be priced around four sources of business value: Performance, Personalization, Prediction and Productivity. The providers that successfully monetize these four Ps instead of billable hours will build businesses with fundamentally different economics.
The mid-market and emerging economies. Traditional delivery models made it uneconomic to serve companies with revenues between $100 million and $1 billion, leaving a vast addressable market largely untouched. Services-as-Software dramatically lowers the cost to serve, opening a developed-market opportunity worth roughly $300 billion across the US, Europe, Japan, South Korea and Australia. Beyond that lies an even larger opportunity across emerging markets, from regional banks in India to manufacturers in Vietnam and logistics providers in Brazil. AI agents do not require visas or large delivery centers, making markets commercially viable that labor arbitrage could never profitably reach. Together, these opportunities represent an additional addressable market approaching $290 billion.
Expanding from the CIO to the C-suite. Most IT services firms have historically operated across only 15% to 20% of enterprise spending, concentrating on IT, business process services and customer operations. Agentic AI opens the remaining 80% by embedding intelligence directly into core business functions such as manufacturing, supply chains, underwriting, healthcare, finance and trading operations. That dramatically expands the addressable market beyond technology budgets into the heart of enterprise value creation.
The compression of the traditional market is real, but so is the expansion of the market that is replacing it. One opportunity is shrinking while another is only beginning to emerge, and the firms best positioned to capture that growth are the very ones Wall Street has decided to write off.
The Bottom-Line: AI and services need each other far more than Wall Street thinks
Wall Street has drawn a remarkably clear line between winners and losers, with AI-native companies representing the future and traditional IT services firms increasingly seen as part of the past. One side now commands price-to-sales multiples of 60x to 100x, while the other is steadily drifting towards 1x as investors bet that AI will replace the labor-intensive services model that has dominated enterprise technology for the last three decades.
The problem with that narrative is that it only works if enterprises can actually deploy AI at scale, and today they simply cannot. Until organizations resolve their technology, data, process, and talent debt, AI will remain trapped in pilots and proofs of concept rather than fundamentally changing how businesses operate, which means the AI balloon won’t burst because the models fail, but because enterprise adoption never catches up with the expectations already baked into today’s valuations.
This is precisely where Services-as-Software changes the equation, creating an entirely new category that sits between traditional services and enterprise software, blurring the distinction Wall Street still uses to justify a 60x multiple on one side and a 1x multiple on the other. Services firms are increasingly becoming software businesses, software companies are moving deeper into implementation and business transformation, and both are converging on the same outcome-based economic model, even if investors have yet to recognize it.
Ultimately, AI-native companies will have to come back to earth because their valuations depend on enterprise adoption that does not yet exist, while services firms have to convince investors they can escape the economics of selling labor and build businesses that scale through software, platforms and outcomes. Neither side gets where it wants to go without the other, and the companies that figure out how to combine AI innovation with enterprise transformation will define the next era of enterprise technology.
What should you do?
If you’re an enterprise leader…
Treat enterprise debt as a board-level issue. Technology, data, process and talent debt are now strategic liabilities, not operational inconveniences. Measure them, prioritize them and fund their resolution with the same discipline you apply to capital investments.
Stop celebrating pilots and start measuring business outcomes. If an AI initiative cannot demonstrate meaningful commercial impact within 90 days, question whether it deserves further investment. Every failed pilot delays the transformation you’re actually trying to achieve.
Buy outcomes instead of effort. Whether you’re purchasing software, AI or services, the conversation should begin with business value, not licenses, tokens or full-time equivalents. If a supplier cannot explain how they improve your P&L, they are selling technology rather than transformation.
Align your AI and services partners. The AI platform and the implementation partner are solving the same problem. If they are working independently, you will pay for the disconnect.
If you’re a services provider…
Stop selling labor and start eliminating enterprise debt. Clients don’t need more people. They need measurable improvements in performance, productivity and business outcomes.
Give investors a Services-as-Software story they can believe. Markets are no longer rewarding headcount growth. They are rewarding recurring platforms, proprietary IP and software-like economics. Show how your revenue mix is changing or accept that your valuation won’t.
Take the conversation beyond the CIO. AI is no longer an IT discussion. It is an operating model discussion that belongs with the CEO, CFO and business leaders responsible for growth and profitability.
Move aggressively into the mid-market. AI has fundamentally changed the economics of serving companies that were previously too small for global providers. This window will not remain open for long.
Stop talking endlessly about AI and refocus on yourself as a foundation fixer with Services-as-Software. Clients already know AI matters. What they need is a partner that can fix the foundations, preventing AI from delivering value. Become known for resolving enterprise debt through Services-as-Software, not for producing another AI presentation.
If you’re an AI-native company…
Sell business outcomes, not tokens. Enterprises don’t want to buy compute. They want faster decisions, lower costs and new sources of growth. Your commercial model should reflect that.
Get closer to implementation. A model working in a demo is very different from a model operating inside complex enterprise systems. The services firms understand those environments. Work with them rather than around them.
Earn trust before expecting scale. Every enterprise deployment that delivers measurable value strengthens your long-term valuation far more than another funding round. Sustainable enterprise adoption will ultimately matter more than benchmark scores or headline valuations.
The future doesn’t belong exclusively to AI-native companies or to traditional services firms. It belongs to the organizations that combine the strengths of both. That is the real opportunity emerging from this market correction, and it is why Services-as-Software may prove to be the most important category the enterprise technology industry creates this decade.
Our industry has become obsessed with building ever more capable AI models, while enterprises have become equally obsessed with gaining access to them.
Every week brings another benchmark, another frontier model, and another announcement that promises to reshape the AI landscape. Just recently, Moonshot AI’s Kimi 3 was the latest reminder that intelligence at the model layer is becoming more capable, more affordable, and increasingly interchangeable.
That’s great news for enterprises, but it also raises a more important question: If every enterprise rents increasingly powerful intelligence from the same handful of providers, from where will lasting competitive advantage actually come?
The answer is not yet another foundation model, but building intelligence that is unique to the enterprise.
Every organization possesses decades of accumulated expertise that no public model can replicate. It exists in the judgment of experienced employees, the way critical decisions are made, the nuances of customer relationships, industry-specific operating practices, and the battle scars and countless lessons learned through years of execution. That knowledge has always been the real differentiator, yet most organizations have never treated it as a strategic asset. Instead, it remains scattered across people, processes, applications, and documents, becoming increasingly difficult to capture, improve, and retain. As we recently researched, there is $18 trillion in trapped value just wasting away in our Global 2000 organizations. Are these really enterprise debts, or is this the value that needs to be unleashed that keeps them unique?
Services-as-Software™ defined: transforming human expertise into enterprise intelligence
This is precisely why HFS has evolved the concept of Services-as-Software™ (SaS). What began as a way for services and software providers to transform expertise into scalable digital capabilities has become something much broader:
Services-as-Software™ is the HFS operating framework that enables enterprises to build Sovereign Enterprise Intelligence by capturing and codifying human expertise, then continuously improving it through execution.
Net-net, SaS combines AI, business context, enterprise data, and governance to create continuously learning digital capabilities that remain owned by the enterprise rather than becoming part of someone else’s intelligence.
Three principles underpin the SaS approach
Capture and codify human expertise. Organizations must transform human expertise into reusable digital capabilities rather than allowing critical knowledge to remain trapped within individuals, documents, or consulting engagements.
Retain sovereignty over enterprise intelligence. AI should be informed by enterprise context without enterprises surrendering the knowledge, operating logic, and business expertise that differentiate them. Enterprise intelligence must remain an enterprise asset, not become part of someone else’s competitive advantage.
Continuously learn from execution. Every workflow, customer interaction, and business outcome should strengthen the enterprise itself. SaS creates a continuous learning cycle in which execution improves the operating model, enriches enterprise intelligence, and elevates the skills and judgment of the people who work within it.
Traditional software automates transactions, and traditional services apply human expertise. Services-as-Software™ continuously transforms that expertise into enterprise intelligence that grows increasingly valuable through execution:
Building Enterprise Intelligence requires a new enterprise operating model
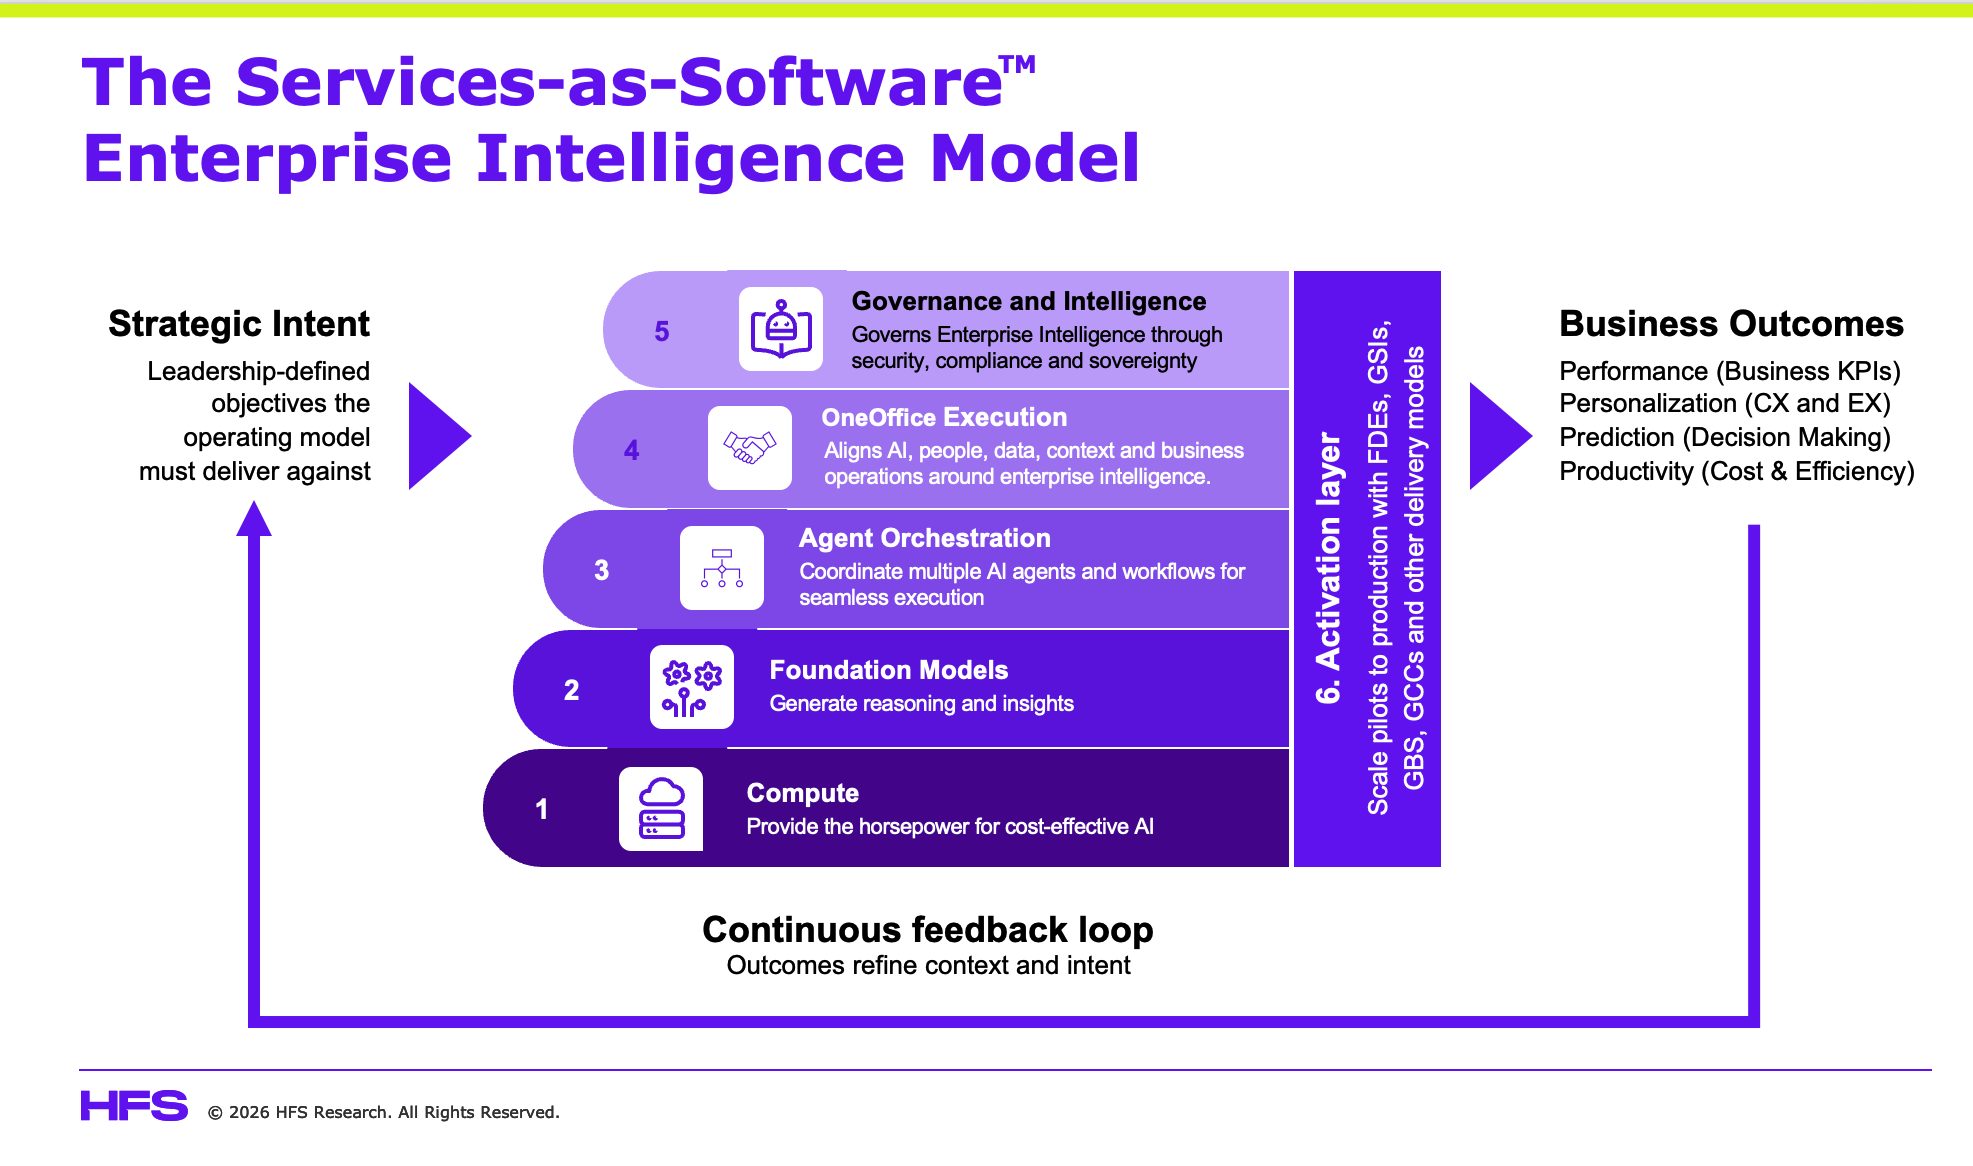
Every operating model begins with intent because AI must never determine enterprise priorities. Leadership defines the strategic outcomes the organization wants to achieve, whether that is revenue growth, customer intimacy, operational efficiency, or innovation. The Services-as-Software Operating Model exists to continuously translate that strategic intent into business execution.
For example, a global retailer defines its strategic intent as improving customer loyalty while reducing fulfilment costs. Rather than deploying AI opportunistically across individual functions, that objective guides every layer of the Services-as-Software Operating Model, ensuring infrastructure, AI models, workflows, and OneOffice Execution all align around delivering measurable improvements in customer experience, inventory optimization, and profitability.
Layers 1 and 2: Compute and Foundation Models
At the Services-as-Software model foundation sits Compute, because every AI capability ultimately depends on accelerated infrastructure running across hyperscale clouds, sovereign environments, or enterprise data centers. Sitting above that are Foundation Models, which continue to improve at extraordinary speed and provide the reasoning, language, and multimodal capabilities that power enterprise AI. Those models remain essential, but they are increasingly becoming interchangeable components of the architecture rather than the architecture itself, allowing organizations to select whichever models best suit a particular workload without fundamentally changing how the enterprise operates.
Fo example, an automotive manufacturer deploys NVIDIA-powered compute across its private cloud and hyperscale environments while selecting different foundation models for engineering design, supply chain optimization, and customer support. Compute provides the horsepower, and foundation models provide the reasoning, but neither creates lasting differentiation because competitors can build a similar technology stack. The real advantage comes from how the enterprise applies those capabilities through its operating model.
Layer 3: Agent Orchestration
The next layer is Agent Orchestration, where multiple models, AI agents, and business workflows are coordinated into a single operating environment. As enterprises increasingly deploy specialized models and autonomous agents, this layer becomes the control plane that governs workflow execution, policy, security, and model selection, allowing organizations to evolve their AI estate without becoming permanently dependent on a single provider.
For example, a customer complaint triggers one agent to verify identity, another to retrieve account history, a third to recommend a resolution, and a fourth to complete the transaction, all coordinated automatically under a single governance framework.
Layer 4: OneOffice Execution
OneOffice Execution is where enterprise strategy becomes enterprise action because this is the layer where AI finally understands the context in which the business operates. Foundation models can reason, summarize and generate extraordinary outputs, but they have no inherent understanding of an organization’s customers, operating policies, regulatory obligations, commercial priorities or risk appetite. Those elements of context are what allow intelligence to become execution, which is why we believe OneOffice Execution becomes the most strategically important layer in the Services-as-Software™ framework.
This is where AI, people, enterprise data and business operations converge into a single execution model that continuously aligns strategic intent with operational delivery. Rather than allowing AI to operate inside disconnected functions or individual applications, OneOffice Execution connects the entire enterprise by orchestrating agents, workflows, business rules, governance and enterprise context across every customer interaction and operational process. Every decision is therefore made with an understanding of how it contributes to broader business objectives, while every process continuously enriches the Enterprise intelligence that makes the organization more competitive over time.
Context becomes the defining capability of this layer because enterprises do not compete on access to AI. They compete on how well AI understands their business. Every organization has unique operating policies, customer relationships, regulatory requirements, commercial priorities and decades of institutional knowledge that no foundation model can infer on its own. OneOffice Execution continuously injects that business context into every AI interaction, ensuring the intelligence being generated is relevant to the enterprise rather than generic to the model. This is also where Enterprise intelligence begins to compound because every workflow, customer interaction and operational decision feeds new knowledge back into the organization instead of enriching the external platforms providing the underlying AI.
Forward Deployed Engineers (FDEs) become the architects of this environment because their role extends far beyond building prompts or configuring AI agents. They work alongside business leaders to understand how work is actually performed, capture institutional knowledge, codify business policies, design AI-native operating workflows and continuously refine how AI executes across the enterprise. Their responsibility is to transform human expertise into reusable operating capabilities that improve through execution, ensuring the organization becomes progressively more intelligent every time the business runs.
This is fundamentally different from both traditional software and traditional services. Traditional software automates transactions inside predefined processes, while traditional services rely on people to interpret context and apply expertise. OneOffice Execution brings those two worlds together by allowing AI to execute work with the same business understanding that previously existed only inside experienced practitioners. The result is not simply faster execution, but an enterprise operating model that continuously learns, adapts and improves while retaining sovereignty over the intelligence it creates.
Consider an insurance provider where, historically, claims processing, underwriting, fraud detection and customer service have operated as separate functions, each supported by different systems, data and teams. Through OneOffice Execution, AI no longer optimizes those activities independently. Instead, it coordinates the entire customer journey by combining policy information, customer history, fraud indicators, underwriting rules, regulatory obligations and settlement decisions into a single contextual operating model. Every claim reaches a faster, more consistent and more accurate outcome, while every interaction simultaneously strengthens the Enterprise intelligence that informs every future underwriting decision, customer conversation and fraud investigation. The organization is therefore not simply processing claims more efficiently, it is continuously becoming a smarter insurer.
Layer 5: Governance & Intelligence
As AI becomes embedded across the enterprise, Governance & Intelligence becomes the capability that ensures enterprise intelligence remains trusted, secure, explainable, and continuously improving.
Enterprise intelligence is the accumulated institutional knowledge, business context, operating logic, and domain expertise continuously created through business execution, governed by the enterprise, and owned as a strategic asset.
Every workflow, customer interaction, and operational decision governed through OneOffice Execution contributes to enterprise intelligence, while governance ensures that intelligence remains trusted, secure, compliant, and uniquely owned by the enterprise.
Unlike traditional governance, which focuses primarily on managing risk and enforcing policy, Governance & Intelligence continuously strengthens the enterprise’s operating model. Security, compliance, digital sovereignty, explainability, and human oversight are embedded directly into AI execution, ensuring that Enterprise intelligence evolves responsibly while remaining protected from external platforms. Every governed interaction enriches the organization’s institutional knowledge, business context, and operating logic, allowing AI to become progressively more accurate, more contextual, and more valuable over time.
This transforms governance from a control function into a strategic capability. Foundation models may provide reasoning, but Governance & Intelligence ensure that reasoning is continuously refined through enterprise knowledge, protected through robust governance, and converted into a proprietary strategic asset that competitors cannot simply license or replicate.
Consider a global pharmaceutical company that continuously governs AI-driven clinical research, regulatory submissions, and manufacturing decisions through OneOffice Execution. Every governed interaction strengthens its Enterprise intelligence while ensuring regulatory compliance, data sovereignty, and patient safety, allowing the organization to innovate faster without compromising trust or control.
Layer 6: Activation
Most enterprises already know how to pilot AI. Very few know how to operationalize it at enterprise scale. That is the role of the Activation Layer. The Activation Layer bridges the gap between experimentation and production by combining Forward Deployed Engineers, Global Capability Centers, business leaders and services partners to industrialize AI across the enterprise. It is where isolated pilots become repeatable operating capability.
A successful AI pilot is only the beginning. For example, a global logistics company uses the Activation Layer to transform an AI scheduling pilot into a global operating capability by combining Forward Deployed Engineers, Global Capability Centers, business leaders and services partners to standardize workflows, governance, training and adoption across more than 50 countries. The result is not simply wider deployment of AI, but a continuously improving operating model that becomes smarter with every shipment.
Business Outcomes become the feedback loop that continuously strengthens Enterprise intelligence
Business Outcomes are not simply the final layer of the Services-as-Software™ operating model because they provide the evidence that the operating model itself is learning. Traditional software measures success by whether a transaction was completed or a process was automated, while Services-as-Software measures success by whether every outcome improves the Enterprise intelligence that drives the next decision. Every customer interaction, operational workflow and business result feeds back into the operating model, refining business context, strengthening governance, enriching Enterprise intelligence and continuously improving future execution.
This creates a fundamentally different way of operating because the organization is no longer just executing work more efficiently. It is learning from execution itself. Success is therefore measured not only by faster cycle times, lower costs or higher productivity, but by whether the enterprise becomes progressively smarter every time the business runs. Over time, that learning compounds into a strategic asset that competitors cannot simply replicate by licensing the same foundation models.
For example, a healthcare provider reduces patient waiting times by 40%, improves clinical outcomes and lowers operating costs because its Services-as-Software operating model continuously learns from every diagnosis, treatment pathway and patient interaction. Clinical decisions become more consistent, care pathways become more personalized and operational bottlenecks are identified earlier because every patient journey strengthens the Enterprise intelligence guiding the next one. The result is not simply better healthcare delivery. It is a healthcare organization that becomes progressively more intelligent every day it operates.
The Continuous Feedback Loop: Where the operating model continuously learns
Unlike traditional operating models, which optimize static processes, the Services-as-Software Operating Model continuously improves itself. Every business outcome feeds back into the operating model, refining enterprise context, improving governance and strengthening Enterprise intelligence. Success is therefore measured not only by today’s performance but by how much smarter the enterprise becomes tomorrow.
For example, a manufacturer deploys AI to optimize production scheduling across dozens of factories. As production outcomes improve, data on quality, machine performance, supply chain disruptions and customer demand continually feeds back into the operating model. Those insights refine business context, improve agent decision-making and strengthen Enterprise intelligence, allowing every production cycle to perform better than the last.
Bottom line: Enterprise Intelligence is becoming the defining strategic asset of the AI era
Phase 1 of enterprise AI was about gaining access to intelligence. Phase 2 is about creating intelligence that your competitors cannot access because it is built from your organization’s own expertise, operating context, and continuous learning.
Services-as-Software™ provides the operating framework for making this possible. It transforms human expertise into Enterprise Intelligence, protects the knowledge that differentiates your enterprise, and ensures every business outcome strengthens your organization rather than an external platform.
Every enterprise will soon have access to increasingly capable AI. The organizations that are already leading their industries are those that continuously build enterprise intelligence through Services-as-Software™, because that is the one asset their competitors can neither license nor replicate.
The services industry has arrived at its most uncomfortable inflection point yet, with too many service providers competing for deals and greedy enterprises exploiting AI to squeeze them to the limit. In short, too many enterprises are outsourcing their downsizing and their lack of AI acumen to services firms, and avoiding having to deal with the internal transformation themselves. If this continues to escalate, the result will be a broken industry, deeply short of talent, and a cutthroat culture that few will want to work in.
And while we definitely get some vibes from the late ’90s and early 2000s from those massive “take the people” deals, which kick-started the whole global outsourcing industry, the difference this time is the elimination of roles to machines, as opposed to a redistribution of talent to lower-cost locations. What we used to call “you mess for less” is fast becoming “your debts for less”…
Buyers want the AI savings before the AI works, and providers are volunteering to be the patsies
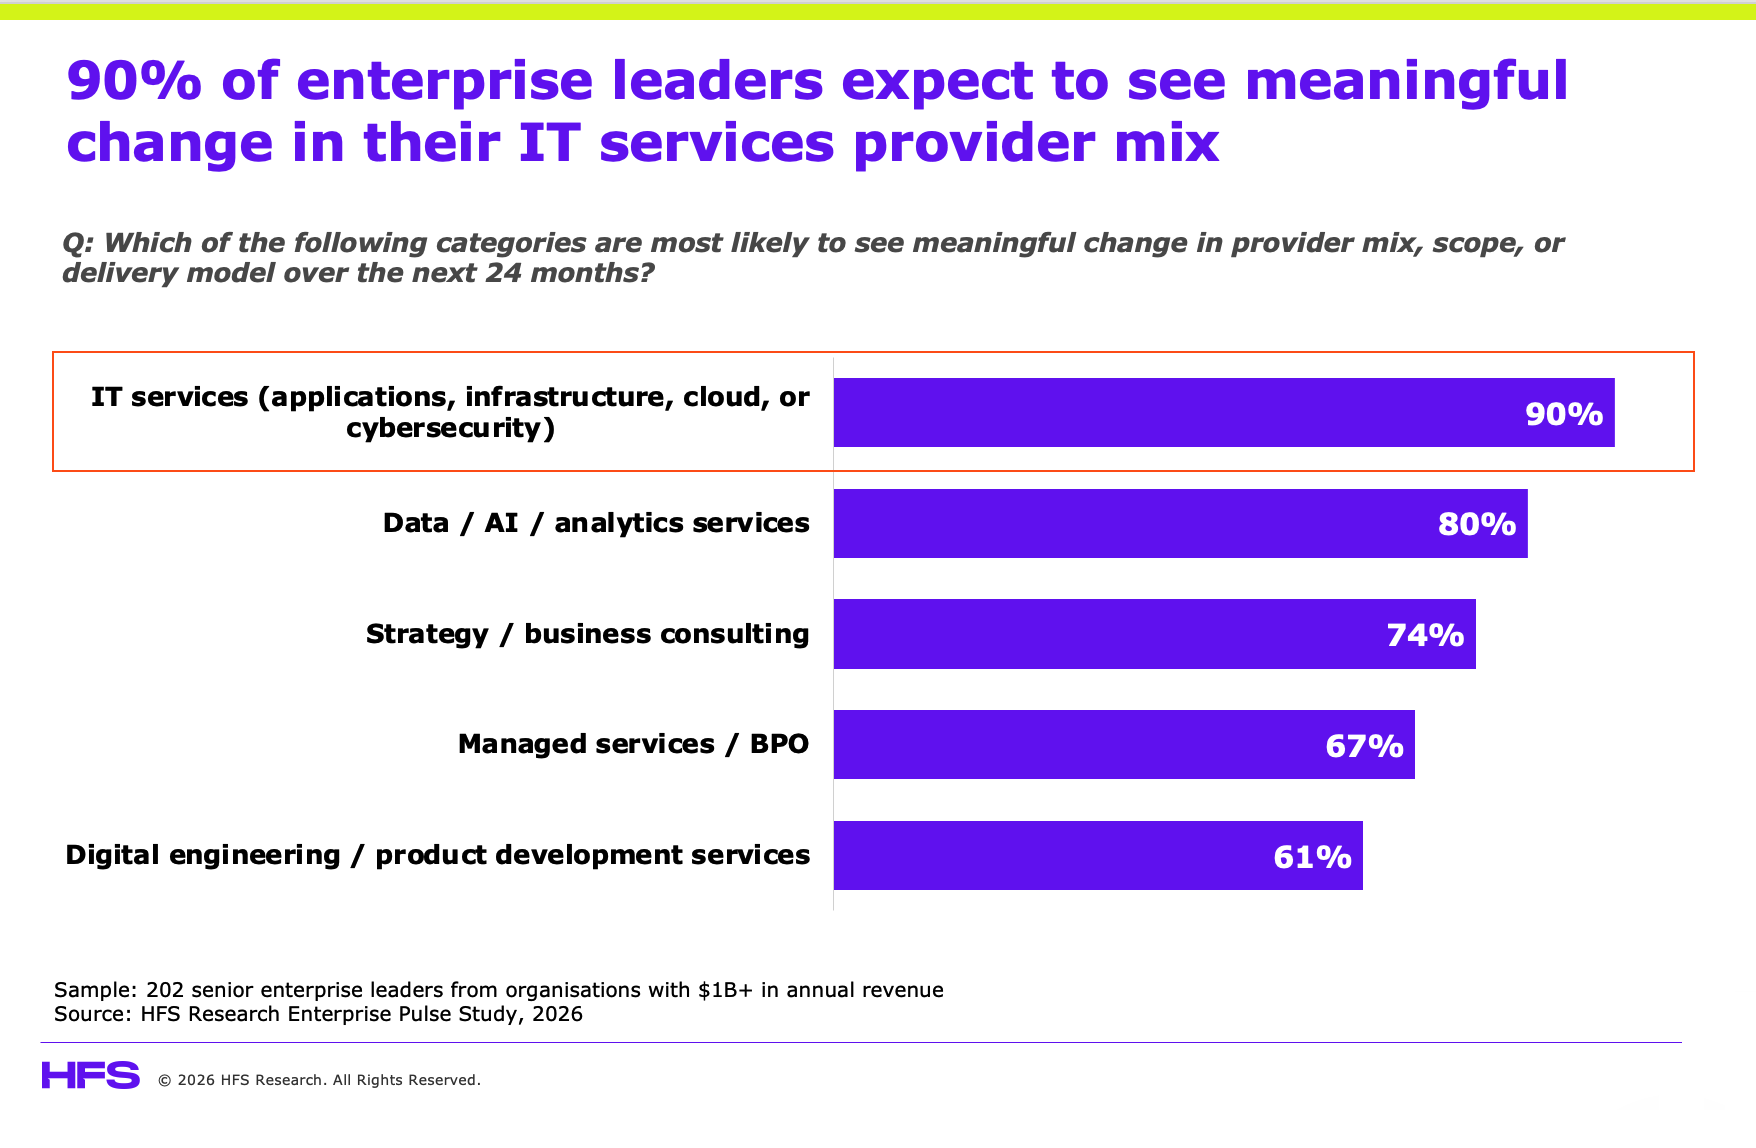
90% of enterprise leaders expect meaningful change in their IT services provider mix, scope or delivery model over the next 24 months, according to our 2026 HFS Enterprise Pulse Study. Meanwhile, we recently saw one competitive deal where an enterprise demanded its provider write it a check upfront worth 40% of the transformation value on MSA signing. And one provider went for it.
Put those two converging issues together and you can see the threat to the health of our entire industry. When practically every contract is in play, desperate providers will accept economics that would have been laughed out of the room five years ago. When those economics require buying the business upfront, the only way to fund the deal is to fire your way to the savings.
And this 40% check is not an outlier. Picture a bank rebadging 2,000 finance and operations staff to a provider that guarantees a 40% run-cost reduction by year three, funds the transition itself and absorbs all the severance costs. Or picture an insurer running a reverse auction where the contract goes to the provider willing to halve the inherited service desk within 18 months, with penalties tied to headcount targets rather than service outcomes. These are just examples of the aggressive enterprise behavior seriously impacting the services industry.
A provider that has bought the business and inherited the client’s employees cannot carry those people indefinitely, hoping a magical AI productivity dividend appears. It has to automate aggressively and cut the workforce fast enough to fund the commitments it made to win the deal. Beneath the legitimate automation and AI story sits a much uglier unwritten objective: the enterprise gets the provider to do its firing. Welcome to Firing-as-a-Service…
The buyers’ market has become dangerous because every contract is now in play
The HFS Pulse data shows why providers are accepting these terms. Beyond the 90% churn intent in IT services, data and AI services sit at 80%, consulting at 74%, managed services and BPO at 67%, and even embedded engineering teams at 61%. Only 17% of enterprises expect to renew with limited change, while 77% plan to renegotiate pricing, 48% plan to shift work to another provider, and 34% expect to consolidate with fewer firms.
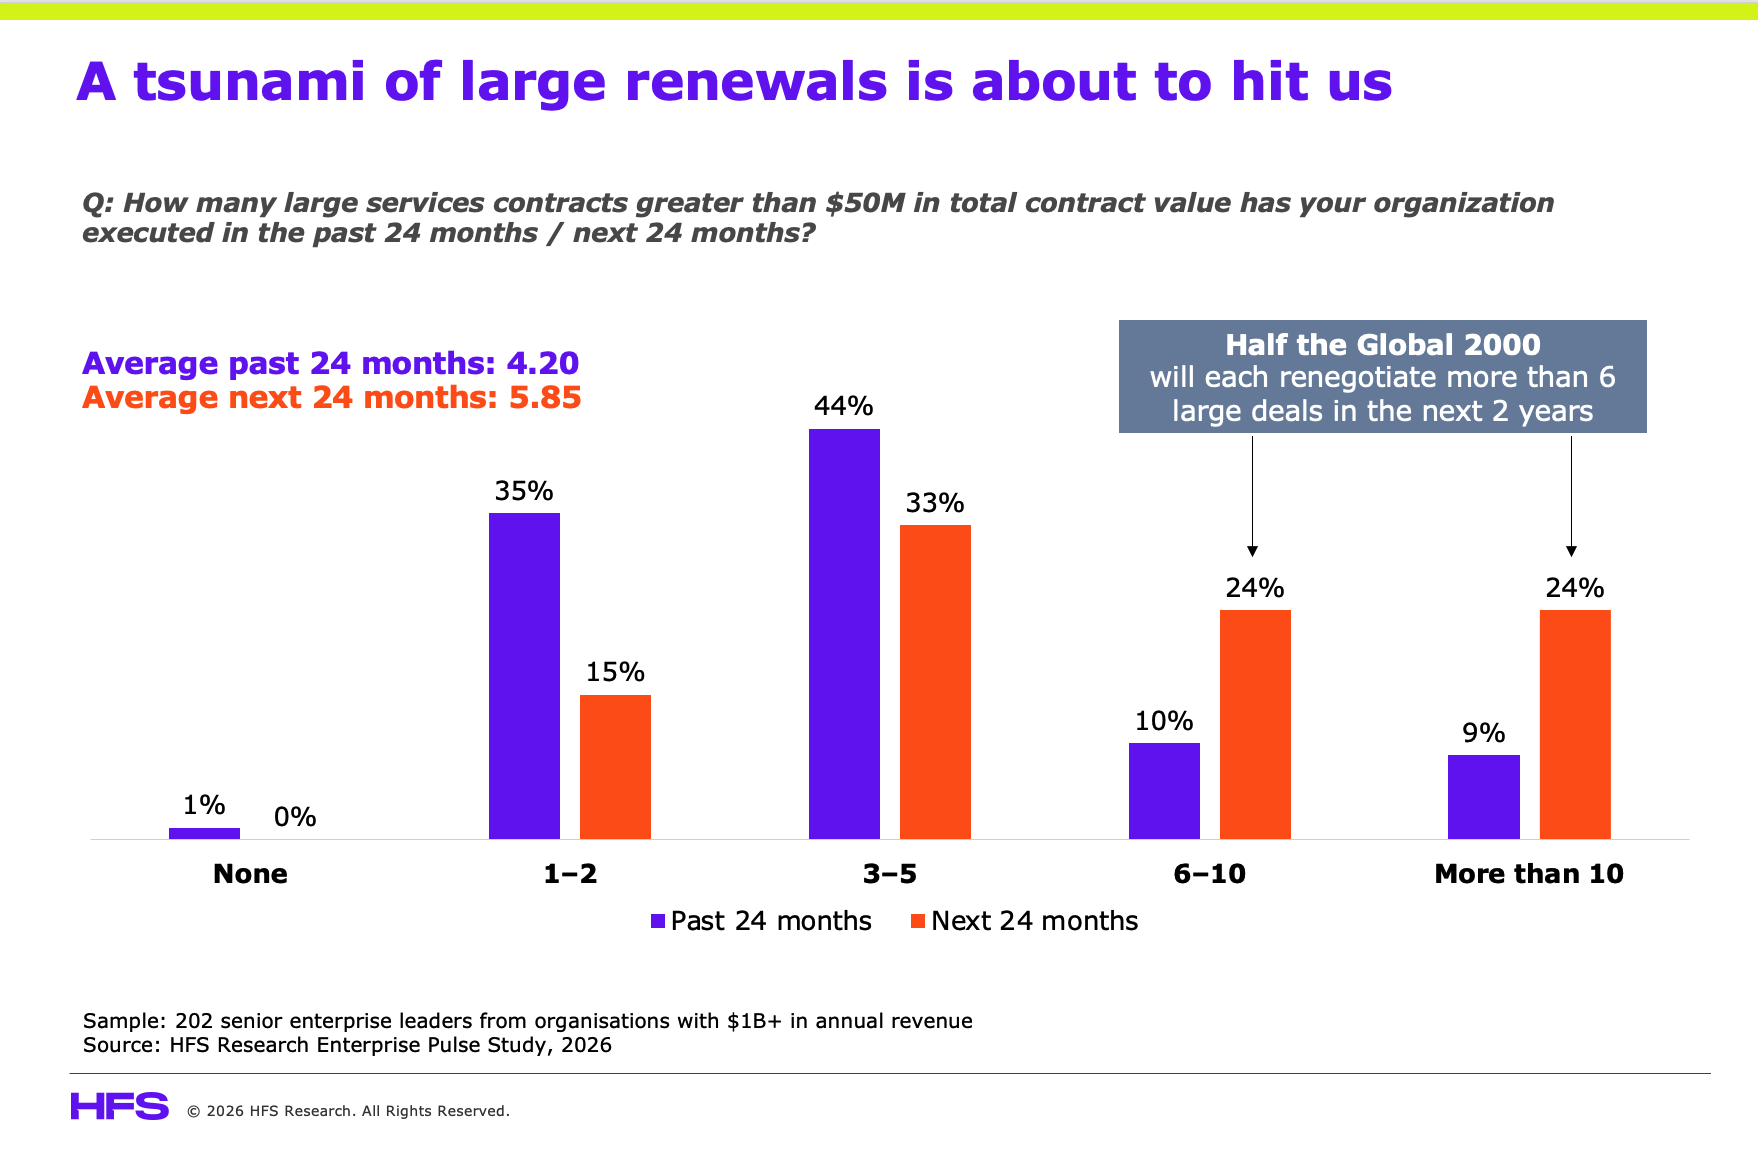
The volume is accelerating too, from an average of 4.2 contracts worth more than $50 million over the past 24 months to an expected 5.85 over the next 24. In fact, nearly 50% of major enterprises will each be evaluating over 5 large services contracts in the next 24 months:
And the desperation cuts both ways, because 73% of enterprise leaders say their providers have not yet delivered AI-led services meaningfully. Buyers feel entitled to punish that capability gap, and providers feel compelled to promise whatever it takes to prove they belong in the AI era.
So imagine sitting inside a major provider whose legacy business is barely growing, where Wall Street wants an AI growth story and losing one $500 million client wipes out years of smaller wins. Someone eventually decides to buy the revenue, and that is when a competitive market becomes a dangerous one.
Once you buy the revenue, you have to find the bodies to fund it
We have seen buy-the-business economics before. The mega-deal era of the 2000s left the industry unwinding write-downs and broken relationships for a decade, and the difference today is that buyers want future AI productivity priced into the contract before the productivity exists.
Rebadged employees instantly become a liability on the provider’s P&L. The transformation team is no longer asking only how much work AI can truly improve. It is also asking how many people must disappear for the spreadsheet to work.
The provider gets handed the dirty work the enterprise does not want to do itself
This gets particularly ugly in process-heavy areas such as finance operations and indirect sourcing, where agents can absorb much of the workflow but success still requires the client’s own people to change how they work. Our Pulse data shows 60% of the friction preventing AI from scaling sits inside the enterprise across integration, data and talent. So providers inevitably start measuring adoption: which analysts route invoices through the new agentic workflow, and which managers quietly rebuild the manual checkpoints the agent was supposed to eliminate.
But there is a nasty line between telling a client where its process is resisting change and identifying which employees are resisting change. Once providers report individuals by name, knowing those names feed workforce decisions, the transformation partner has entered a very different business.
The client no longer has to be the bad guy policing adoption and deciding who no longer fits. It becomes a dirty little snitching game where the provider identifies the resistance, the client approves the restructuring, and everybody points to AI as the reason it had to happen.
AI did not create this behavior. It industrialized it
Outsourcing has always involved displacement, rebadging and offshoring, but AI lets leaders question every process, role and contract simultaneously, and it provides convenient cover. Cut 5,000 jobs because you missed your numbers and you have a morale problem, but cut 5,000 jobs because you are becoming an AI-first enterprise and suddenly it sounds like innovation.
The hypocrisy shows up in our data. Enterprises cite innovation speed as their top sourcing driver at 49%, ahead of AI-led productivity at 45% and cost at 44%, yet they structure deals whose economics reward headcount removal above everything else. You cannot claim to buy innovation while paying for elimination.
Not every provider can stomach this model
The Big Four have spent decades running restructurings, so aggressively reshaping a client’s organization is familiar territory. For firms such as TCS and Infosys it is far more uncomfortable, because their cultures were built as enormous employment engines with an implicit social contract around long-term careers. Competing this way does not simply challenge their pricing, it challenges what kind of companies they want to become.
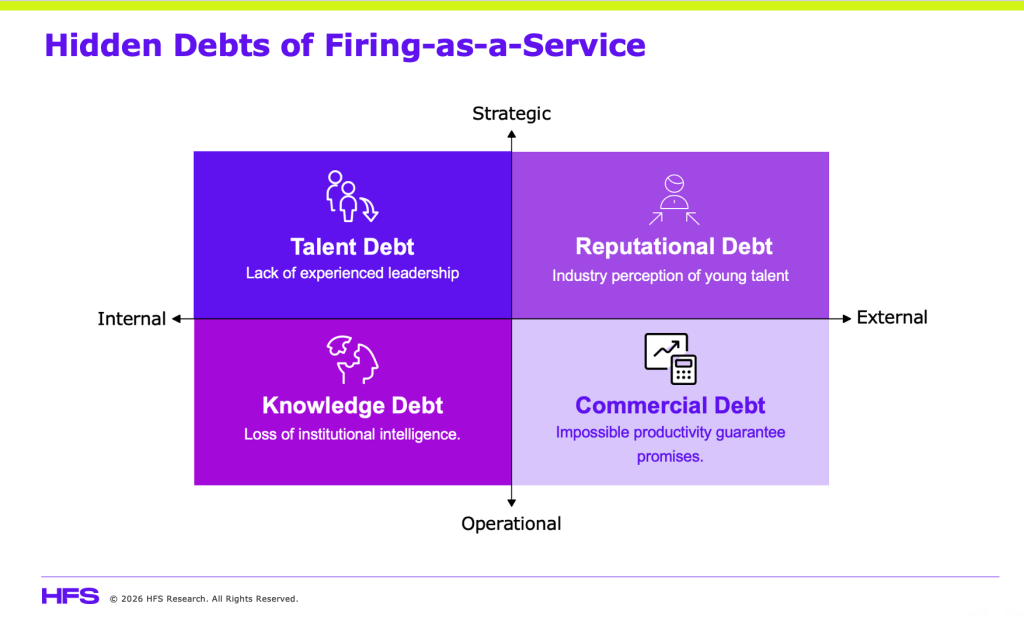
Firing-as-a-Service creates four debts nobody is pricing into these deals
Talent debt arises when providers cut graduate intake, only to discover years later that they lack people experienced enough to lead complex transformations. Knowledge debt follows, because veteran employees hold the institutional intelligence around exceptions and how processes actually behave, and eliminating them before capturing it creates automated amnesia rather than an autonomous enterprise.
Commercial debt builds as one provider promises 25% productivity, a rival promises 35%, and somebody desperate for the logo promises 45%, until some guarantees prove impossible to deliver without destroying margins or quality. Reputational debt completes the set, as employees learn who built the technology that measures them, and young talent decides whether this industry deserves their careers. None of these debts appear in the business case on MSA signing. Instead, they arrive later:
The firing paradox: only 24% of enterprises expect AI to shrink labor demand
Here is the paradox that demolishes the firing narrative. Just 24% of enterprise leaders expect model-driven modernization to reduce labor demand, even though 42% believe it will reshape IT services entirely.
Model-driven modernization means rebuilding the IT estate around foundation models and agents rather than around people and their processes. Instead of armies of engineers manually migrating applications, documenting code, and testing releases, models increasingly perform the modernization work itself, and enterprises are taking this seriously, with 51% now viewing their primary foundation model as mission-critical, and agentic AI topping their technology priorities. This is the biggest change to how services are delivered since offshoring, which is exactly why the labor finding matters so much.
Even with that scale of change, most enterprise leaders expect demand to shift toward higher-value work, not disappear. The mass workforce reductions being priced into these deals rest on an outcome most buyers do not even believe in. Eliminating obsolete work is progress, while selling the elimination of workers is Firing-as-a-Service.
Investing in young talent is the real antidote
The graduate pipeline is already being cut at the source, with the Big Four trimming UK intakes citing AI and recent US graduates facing unemployment around 7%. We destroyed a pipeline once before when the BPO wave stripped out the entry-level accounting work where graduates cut their teeth. Ten years ago these kids competed with offshoring, and now they compete with software.
Yet the fundamentals have not changed. Services has always been built on skills-at-scale tied to common technology platforms, and Services-as-Software runs on the same principle with AI platforms and domain-centric skills. A provider that hires AI-native graduates and turns them into augmented doers has something to sell beyond headcount elimination.
So make the antidote practical and redeploy rebadged employees into adoption coaching, data stewardship and exception handling rather than making termination the default output of automation, and commit a fixed percentage of every guaranteed saving to reskilling so procurement can compare it across bidders. Talent is a services firm’s identity, and firms that sacrifice it to fund these deals will wake up as faceless corporations united under a logo.
Bottom line: Stop turning AI transformation into an outsourced firing machine
Providers should be extremely cautious about deals whose economics require workforce reductions that have not been technologically proven, and they should insist that employment decisions remain with the enterprise whose people are being transformed. CEOs need to stop celebrating every massive AI deal without asking who actually pays for these economics. If the answer is the provider upfront and thousands of employees later, we are consuming the very talent base on which this industry depends.
The promise of AI is to eliminate the work humans should no longer perform and to create a new generation of professionals who combine judgment, domain expertise, and machine intelligence. The danger is that a desperate industry buys revenue with its own cash, rebadges its clients’ employees, and fires enough of them to make the economics work, while the enterprise stands at arm’s length and calls it AI transformation.
That is not Services-as-Software. That is Firing-as-a-Service, and if it becomes the defining business model of the AI era, we will have turned the most powerful technology revolution of our careers into an extraordinarily sophisticated way for enterprises to get somebody else to do their dirty work.